[ADC12 Daily Price Review] Aluminum alloy futures bottom out and rebound; spot prices remain stable awaiting guidance

Published: Nov 20, 2026 11:48 (GMT+8)
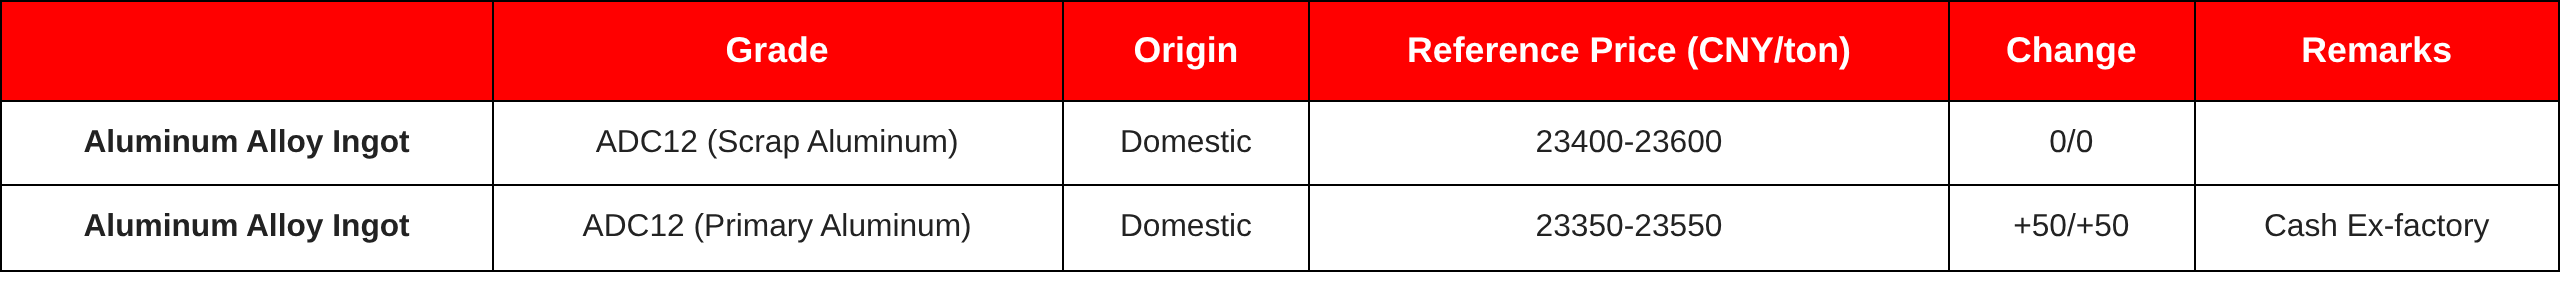
[ADC12 Price Daily Review: Aluminum Alloy Futures Bottom Out, Spot Prices Hold Steady Awaiting Guidance] ADC12 market quotes remained largely stable today, with the SMM ADC12 price flat from the previous trading day at 23,500 yuan/mt. After the recent consecutive declines, the pace of price adjustments in the market has slowed somewhat. As primary aluminum prices and futures rebounded slightly, downward pressure on the market eased temporarily, and some quoting parties began to turn to a wait-and-see stance, with reduced willingness to proactively lower their quotes.

Futures: The most-traded AD2701 cast aluminum alloy contract opened at 21,220 yuan/mt today, plunged to 20,895 yuan/mt in early trading on heavy volume, then consolidated and recovered. It rebounded to 21,300 yuan/mt intraday and met resistance, closing the morning session at 21,240 yuan/mt, up 90 yuan, or 0.43%, from yesterday’s settlement price.

Spot: ADC12 market quotes were largely stable today. The SMM ADC12 price was flat from the previous trading day at 23,500 yuan/mt. After consecutive declines earlier, the pace of market price adjustments slowed. With primary aluminum prices and futures rebounding slightly, downward pressure on the market eased temporarily. Some sellers turned to a wait-and-see stance, and willingness to actively cut offers weakened. However, the current price rebound has not yet shown clear sustainability. End-use demand remained relatively mediocre, with purchases mainly just-in-time procurement, and improvement in transactions was limited. Against the backdrop of a short-lived rebound in the cost side and futures, the market has temporarily entered a phase of halting losses and observing. In the near term, ADC12 prices are expected to move sideways, with the subsequent trend still dependent on aluminum price performance, aluminum scrap price changes, and the recovery of downstream orders.

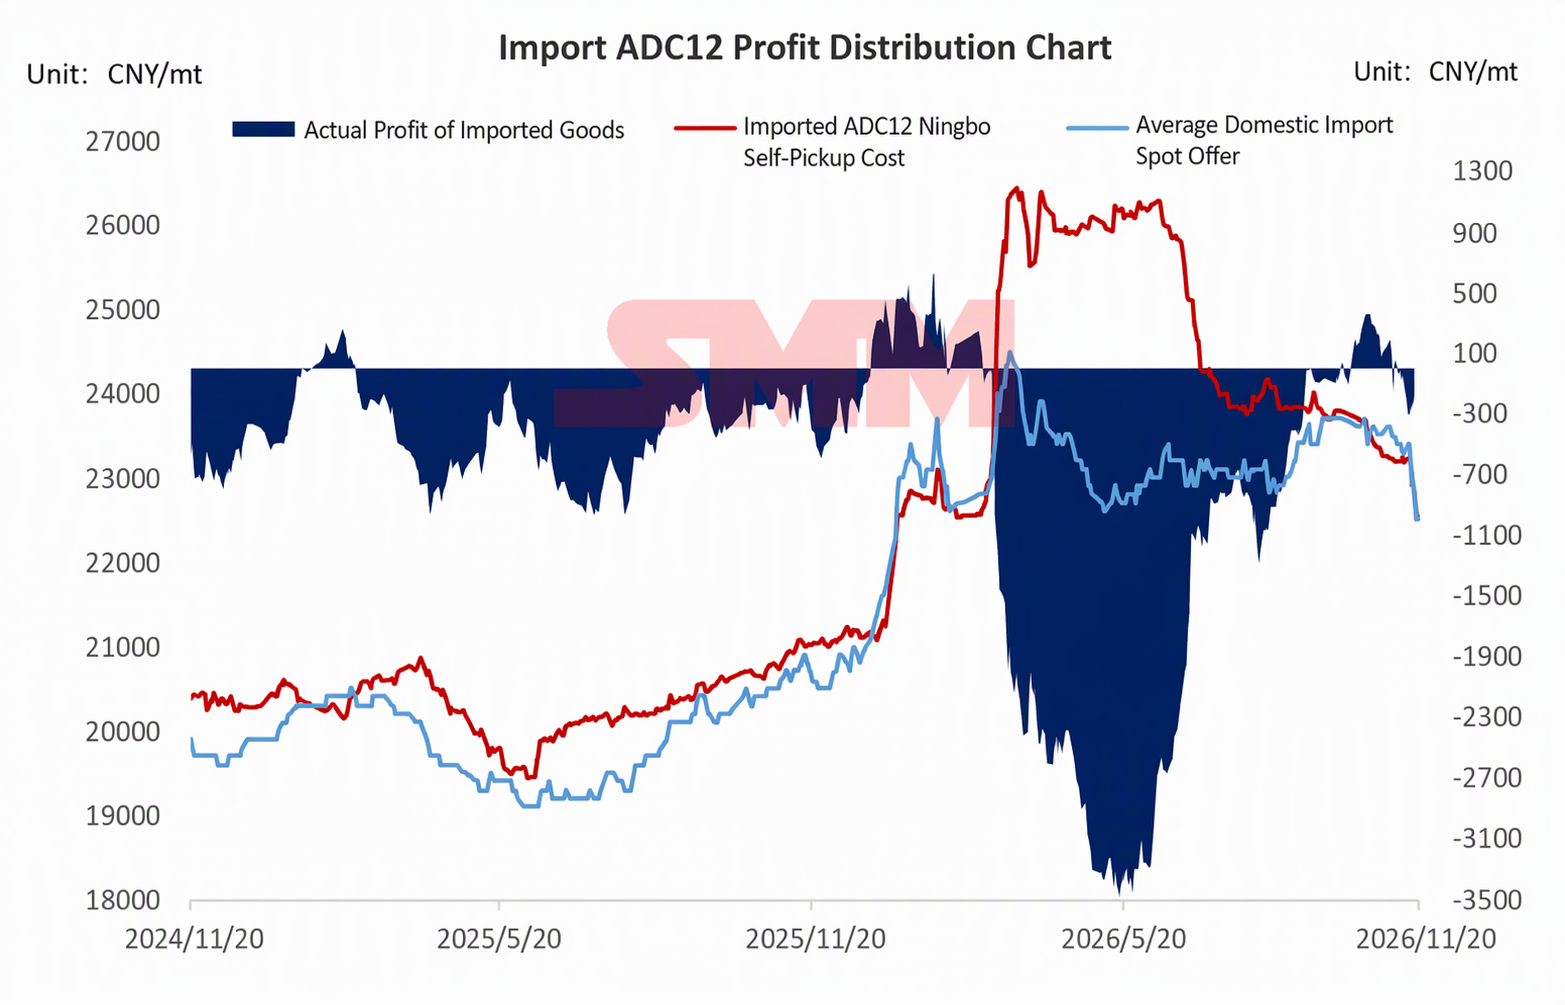
Imports: Ex-China ADC12 offers fell to $3,000–3,020/mt. As domestic prices declined by a larger margin, import parity turned slightly negative again.

Data Source Statement: Except for publicly available information, all other data are processed by SMM based on publicly available information, market communication, and relying on SMM's internal database model. They are for reference only and do not constitute decision-making recommendations.

Images in this article contain AI-translated captions for reference only.

For any inquiries or for more information, please contact: lemonzhao@smm.cn
For more information on how to access our research reports, please contact:service.en@smm.cn
Related News
PMET Resources Adds Tantalum Production to Québec Project, Targets 635,000 Pounds of Annual Contained Ta₂O₅
13 hours ago
PMET Resources Adds Tantalum Production to Québec Project, Targets 635,000 Pounds of Annual Contained Ta₂O₅
Read More
PMET Resources Adds Tantalum Production to Québec Project, Targets 635,000 Pounds of Annual Contained Ta₂O₅
[SMM Tantalum Flash] PMET Resources published an updated feasibility study on 11 November 2026 for its Shaakichiuwaanaan lithium project in Québec, Canada, incorporating tantalum recovery into the proposed development of the CV5 deposit. The revised study forecasts average annual production of approximately 635,000 pounds of contained Ta₂O₅ in tantalite concentrate over the project's life, with Phase 1 alone expected to produce up to 455,000 pounds annually. The project has a proposed processing capacity of 2.2 million tonnes per year in Phase 1, expanding to a combined 5.1 million tonnes per year in Phase 2. A maiden probable tantalum reserve of 83 million tonnes grading 148 ppm Ta₂O₅ was also reported. The addition of tantalum recovery is expected to generate an estimated US$108 per tonne operating-cost credit, improving the project's overall economics. PMET is targeting plant commissioning from the latter part of 2029, with a final investment decision expected in late 2027. The feasibility study represents a more advanced development milestone for the company.
13 hours ago
Australasian Metals Advances Drilling at Côte d'Ivoire's Atex Lithium-Tantalum Project
13 hours ago
Australasian Metals Advances Drilling at Côte d'Ivoire's Atex Lithium-Tantalum Project
Read More
Australasian Metals Advances Drilling at Côte d'Ivoire's Atex Lithium-Tantalum Project
[SMM Tantalum Flash] Australasian Metals is advancing exploration at its Atex Lithium-Tantalum Project in Côte d'Ivoire, where it holds an exclusive option to acquire a 75% interest. The company has commenced auger drilling at the Tindara South and Tindara East target areas to investigate additional pegmatite systems. Its exploration programme also includes near-surface sampling to assess tantalum and niobium mineralisation, with composite samples from the upper two metres of drill holes intended for laboratory analysis. The programme follows earlier preparations for an approximately 3,000-metre diamond drilling campaign at Spodumene Hill and regional targets. The exploration work is intended to establish the extent of lithium-bearing pegmatites while assessing the potential for associated tantalum and niobium mineralisation. Priority targets identified through the auger programme may progress to further diamond drilling. However, the latest exploration information does not establish a new tantalum resource or commercial deposit, and the company has not announced any expected concentrate production.
13 hours ago
Review of Tantalum & Niobium Markets — 19 November 2026
13 hours ago
Review of Tantalum & Niobium Markets — 19 November 2026
Read More
Review of Tantalum & Niobium Markets — 19 November 2026
China Market: SMM's assessment for 30% tantalum ore CIF China on 19 November stands at US$220–225/lb, averaging US$222.50/lb, down US$2.50/lb, or 1.11%, from the US$225/lb average recorded on 18 November. The latest decline extends the downward movement in China's assessed tantalum ore import prices, with the average falling from US$242.50/lb on 3 November. This represents a cumulative decrease of US$20/lb, or approximately 8.25%. The continued decline indicates weaker assessed import price levels, although the available quotations do not independently establish whether reduced purchasing activity, increased supply offers or other market factors are driving the adjustment. East Africa FOB Tantalum Ore: SMM's assessment for 19 November stands at US$4.00–4.40/kg per 1% Ta₂O₅, averaging US$4.20, down US$0.20, or 4.55%, from the US$4.40 average recorded on 12 November. The assessment covers tantalum ore grading 28%–38% Ta₂O₅ from the DRC, Rwanda and Burundi, on an FOB Dar es Salaam basis. Market quotations remain relatively firm at the upper end, with some sellers holding back material in anticipation of better prices. However, lower indications around US$4.00/kg per 1% Ta₂O₅ reflect softer selling offers, while quotations towards US$4.40 indicate continued resistance among some sellers to further declines. Confirmed transactions remain limited, and buying interest is cautious. The latest assessment marks a second consecutive weekly decline and indicates continuing downward pressure on East African export prices. African Tantalum and Niobium Developments: In Namibia, Atlas Metals Group announced on 17 November that it had signed heads of terms for the proposed acquisition of 100% of B1 Metals, which holds an effective 80% interest in a lithium, tin and tantalum project in the Erongo region. The project operates under Mining Licence ML129, with the remaining 20% interest held by the Government of Namibia. The proposed consideration is approximately £54 million in new Atlas shares, while the agreement provides exclusivity until 28 February 2027 for due diligence and negotiations. The transaction remains subject to technical, legal and financial assessments, definitive agreements and the necessary approvals. The proposed acquisition indicates continued corporate interest in Namibia's tantalum-bearing mineral assets, although no new tantalum production capacity or output timetable has been confirmed. Meanwhile, in Côte d'Ivoire, Australasian Metals announced on 16 November that auger drilling had commenced at the Atex Lithium-Tantalum Project, where the company holds an exclusive option to acquire a 75% interest. Initial drilling is focused on the Tindara South and Tindara East targets to investigate additional pegmatite systems beyond Spodumene Hill. The exploration programme also includes near-surface sampling to assess tantalum and niobium mineralisation, with composite samples from the upper two metres of drill holes planned for laboratory analysis. The company is separately preparing an approximately 3,000-metre diamond drilling programme targeting Spodumene Hill and regional prospects. Niobium Market: SMM's 19 November FOB niobium pentoxide assessments remain unchanged. The assessment for 99.5% Nb₂O₅ stands at US$55–60/kg, averaging US$57.50/kg, while the 99.99% Nb₂O₅ assessment remains at US$66–68/kg, averaging US$67/kg. Both are unchanged from 18 November. The stability of these FOB assessments contrasts with the continued decline in tantalum ore prices. Tantalum Refined Products: SMM's 19 November FOB assessment for 99.5% tantalum pentoxide remains at US$630–640/kg, averaging US$635/kg, while the 99.99% grade remains at US$670–680/kg, averaging US$675/kg. Both assessments are unchanged from the previous day. In contrast, China's domestic assessments show small downward adjustments, with 99.5% tantalum pentoxide averaging US$565.05/kg and 99.99% tantalum pentoxide averaging US$654.86/kg. The relative stability of FOB refined tantalum oxide assessments contrasts with the sharper decline in assessed tantalum ore prices, although differences in product specifications, trading locations and assessment methods limit direct comparisons. Market Outlook: Decline in the East African FOB tantalum ore prices follows the continued downward movement in China's assessed import prices. Although the two assessments have different pricing bases, their recent movements indicate downward pressure in both markets. Limited confirmed transactions and cautious buying interest suggest that market participants remain selective, while resistance among some African sellers to lower offers may moderate further adjustments.
13 hours ago
Register to Continue Reading
Gain access to the latest insights in metals and new energy
Already have an account?Sign in here