Nov 6 Morning Meeting Notes
Market hot topics:
The Indonesian government's special task force on combating illegal forest land occupation stated that Indonesian authorities are taking immediate enforcement action against enterprises controlled by or associated with Arif Kurniawan, a former Glencore nickel ore trader. Preliminary investigations found that the relevant enterprises had committed violations in mining activities, permits, and forest land use, but specific enforcement measures have not yet been announced. Kurniawan is a major figure in Indonesia's nickel ore industry. More than a decade after leaving Glencore, he rapidly grew into one of Indonesia's largest nickel ore traders. A previous industry survey report showed that in 2024, his nickel ore trading volume accounted for about one-third of Indonesia's total national nickel ore supply. In addition, he and his core business partners jointly hold mining interests in at least 20 mining areas in Indonesia.
Macro:
(1) The US midterm elections delivered a "blue wave," with Democrats regaining control of both the Senate and the House. Multiple US media outlets projected that Democrats secured at least 54 seats in the Senate (flipping seven Republican seats including Texas and Ohio, with Texas electing a Democratic senator for the first time in 38 years), and the House is expected to ultimately exceed 245 seats; Trump stated he accepts the results and acknowledged that the Iran conflict weighed on the election outcome. Democratic leaders have already signaled they will seek to repeal Trump's tariffs and end the war against Iran, and the market expects the shift in Congress to constrain Middle East military operations and increase the probability of a US-Iran diplomatic resolution.
(2) International oil prices plunged nearly 9%. The market is betting on a rapid cooling of geopolitical risks, with WTI closing down 8.66% at $87.49 per barrel and Brent down 9.43% at $94.01 per barrel, both hitting their lowest closes since August 31; combined with EIA data showing US crude oil production rising to a record high and the UAE considering building a third pipeline bypassing the Strait of Hormuz, supply expectations have shifted toward easing.
(3) The US dollar posted its biggest drop in three weeks, while US stocks surged. The US dollar index fell 0.33% to 101.53, the 10-year Treasury yield dropped 8 basis points to 4.884%, and the 2-year yield hit a two-month low, as market bets on further Fed tightening weakened; the Dow rose 3.03%, the S&P 500 gained 1.58%, the Nasdaq advanced 1.44%, and the Nasdaq Golden Dragon China Index climbed 3.48%. COMEX gold rose 3.34% to $4,072 per ounce.
(4) Indonesia: According to an SMM flash report on November 4, Indonesia's National Economic Council (DEN) supports the Ministry of Energy and Mineral Resources (ESDM) in cutting nickel production through the Mining Work Plan and Budget (RKAB) to ease the global oversupply and support nickel prices. DEN member Septian Hario Seto noted at the Minerba Convex event on November 3 that Indonesia's continued growth in nickel production has exacerbated the global oversupply and put pressure on nickel prices. Energy and Mineral Resources Minister Bahlil Lahadalia also stated that Indonesia plans to draw on the coal industry's supply management model to regulate nickel ore production through RKAB. DEN's support indicates that tightening nickel ore supply has gained more policy-level backing, further reinforcing market expectations for a slowdown in supply growth in 2027. Given that the adjusted RKAB quota for 2026 is approximately 295-300 million wmt, there is potential for further cuts to the 2027 quota, though the specific reduction remains to be clarified.
Spot market:
On November 5, the average price of SMM #1 refined nickel was 121,950 yuan/mt, up 3,850 yuan/mt from the previous trading day. In terms of spot premiums, the average premium for Jinchuan #1 refined nickel was 3,500 yuan/mt, down 200 yuan/mt from the previous trading day, while mainstream domestic electrodeposited nickel brands ranged from -300 to 600 yuan/mt.
Futures market:
The most-traded SHFE nickel contract (2612) opened higher and continued to rise in early trading, closing the morning session at 122,250 yuan/mt, up 4.86%, with open interest down by about 5,400 lots.
Short-term outlook:
The Democrats regaining control of Congress has reshaped the macro direction of the market, and combined with Indonesia's quota stance, this "Davis double play" drove concentrated short covering by bears. Going forward, attention should be paid to the actual extent of Indonesia's quota cuts to determine the sustainability of the rebound. In the short term, the most-traded SHFE nickel contract is expected to trade in the range of 118,000-124,000 yuan/mt.
Nickel sulphate
On November 5, the average price of SMM battery-grade nickel sulphate edged up slightly.
Cost side, the US midterm election results and Indonesia's quota statements resonated, driving nickel prices sharply higher today and pushing up spot production costs for nickel sulphate. Supply side, some producers are holding relatively high inventory levels and seeking production cuts to destock, and with nickel prices rising today, they have some willingness to hold prices firm. Demand side, given expectations of reduced end-use demand, downstream enterprises are showing weak sentiment toward building spot order inventories and have relatively low acceptance of nickel salt prices. Today, the Willingness to Sell Sentiment Factor for upstream nickel salt smelters was 2.1, the procurement sentiment factor for downstream precursor plants was 2.0, and the sentiment factor for integrated enterprises was 2.1 (historical data can be queried in the database).
Looking ahead, spot order market activity is expected to remain weak in the short term, with nickel sulphate prices under overall pressure. Attention should be paid to the sustainability of the rise in nickel prices.
NPI
November 5 news: SMM's high-grade NPI market sentiment factor was 1.71, up 0.05 MoM. The upstream sentiment factor for high-grade NPI was 1.81, up 0.09 MoM, and the downstream sentiment factor for high-grade NPI was 1.62, up 0.02 MoM. Nickel-iron market sentiment recovered notably today, with inquiries becoming more active and a shift in market mentality, from downstream caution and reluctance to purchase in the earlier period to upstream holding back from selling and unwillingness to ship. Some cargo offers were raised, and traders turned relatively optimistic about forward prices, especially for Q1 next year, mainly supported by macro tailwinds and expectations for tighter Indonesian policies. However, divergences within the market remain prominent, with some participants believing the basis for the short-term recovery is weak and sustainability is questionable, while resistance to high-priced spot order transactions persists. Current transactions are clearly differentiated, with forward average-price premium deals relatively active and fixed-price deals scarce. Steel mills are releasing limited rigid demand, and nickel-iron inventory still needs to be absorbed. Year-end two-fund management factors brought periodic shipment disruptions, and the stronger stainless steel futures also led some suppliers to turn bullish, intensifying the tug-of-war between longs and shorts.
Stainless steel
According to SMM on November 5, SS futures consolidated higher today and continued to shot up. With the US midterm election results largely settled and news of further tightening in Indonesian nickel ore approvals providing a catalyst, SHFE nickel prices shot up sharply, and SS extended its previous gains, moving higher in tandem. As of the close, the most-traded SS contract settled at 14,155 yuan/mt. In the spot market, driven by the sharp rise in SS futures, stainless steel spot offers continued to move higher. Although downstream end-user clients were generally cautious due to high prices and showed weak purchase willingness, speculative demand drove increased inquiry and trading activity among futures and spot institutions and traders.
SS most-traded futures contract. At 10:15 a.m., SS2612 was at 14,045 yuan/mt, up 335 yuan/mt from the previous trading day. Spot premiums for 304/2B in Wuxi were in the 225-625 yuan/mt range. In the spot market, the average price of Wuxi cold-rolled 201/2B coil was flat; for cold-rolled uncut edge 304/2B coil, the average price in Wuxi rose 150 yuan/mt and the average price in Foshan rose 150 yuan/mt; the price of cold-rolled 316L/2B coil in Wuxi was flat; for hot-rolled 316L/NO.1 coil, Wuxi offers were flat; cold-rolled 430/2B coil in both Wuxi and Foshan was flat.
This week, the stainless steel market showed a consolidating tug-of-war pattern of “news-driven rebound followed by giving back gains, weak supply and demand, and passive inventory destocking.” Last week, futures strengthened at one point on expectations for Indonesian nickel-iron production cuts; this week, the US Fed released a hawkish signal, year-end rate hike expectations rose, and the actual implementation of Indonesian nickel production cuts was limited, gradually falsifying bullish factors. SS futures consolidated around the 13,400 yuan/mt level, and the earlier rebound sentiment cooled notably. From a macro perspective, although the Fed did not implement a rate hike at its October meeting, its stance was hawkish, and market expectations for a year-end rate hike rose, continuing to pressure risk appetite in the nonferrous metals sector. Meanwhile, expectations for tighter Indonesian nickel supply that had driven the futures rebound lacked substantive verification this week, and the bullish driver weakened marginally, becoming the core reason for the pullback in futures. Spot market, last week, the Indonesia nickel production cut news drove prices higher in phases, leading to a concentrated release of transactions. However, as the bullish news was gradually digested, the market returned to the main theme of weak demand. Trading remained sluggish, with downstream buyers only making just-in-time procurement. The market generally expects steel mills to still hold certain profits, leaving room for price concessions to boost sales. Coupled with rising shipment pressure near month-end, some traders proactively cut prices to stimulate transactions. Spot prices were in the doldrums, and end-use demand showed no real improvement in procurement. Inventory side, despite persistently weak spot transactions, this week's arrivals were low, and phased month-end cargo pick-up demand provided support, allowing stainless steel social inventory to continue destocking. However, this round of destocking was not driven by a recovery in end-use demand, but rather by low arrivals and month-end cargo pick-up disruptions. Demand fundamentals have not materially improved, and the sustainability of destocking remains weak. Cost side, nickel pig iron prices continued their weak trend, while stainless steel scrap weakened further due to rising risk-aversion sentiment and tight tax invoices, widening the cost gap between stainless steel scrap and nickel pig iron processes. Meanwhile, TISCO and Tsingshan announced November ferrochrome tender prices, down 200 yuan MoM. Although finished steel prices also pulled back under pressure, raw material prices fell more sharply, allowing steel mill profit margins to be maintained. Supply side, steel mills still have profit buffers and room for price concessions, but social inventory remains at relatively healthy levels, reducing the incentive for aggressive price cuts. Additionally, some mills undergoing maintenance and production cuts have resumed normal operations, lifting planned production. Overall, this week's stainless steel market showed a game of hawkish macro pressure, bullish news being disproven, weak spot demand, month-end price concessions to boost transactions, weaker raw materials supporting steel mill profits, and passive inventory destocking. The weak fundamental backdrop for stainless steel remains, with profit recovery coming solely from raw material declines, making it difficult to drive a sustained price uptrend.
Nickel ore:
Philippines market:
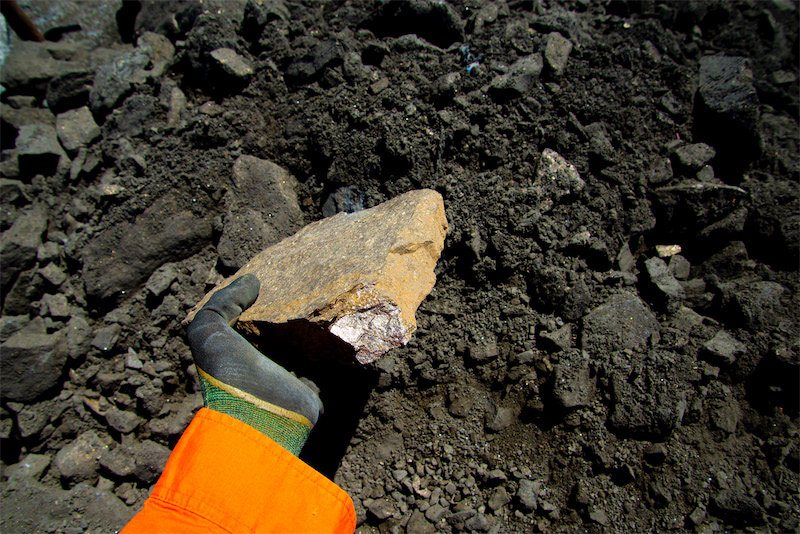
This week, Philippine nickel ore prices continued to decline, with prices across all grades generally weakening. As of October 30, on an FOB Philippines basis, Ni 0.9% (Al 7% max) was $21-22/wmt, averaging $21.5/wmt; Ni 1.3% averaged $26/wmt, Ni 1.4% averaged $36/wmt, Ni 1.5% was $42-45/wmt, averaging $43.5/wmt, and Ni 1.8% was $70-72/wmt, averaging $71/wmt, with all grades down $1/wmt from the previous period. On a CIF China basis, Ni 0.9% (Al 7% max) averaged $34/wmt, while Ni 1.3%, 1.4%, 1.5%, and 1.8% were $39.5, $50, $58.5, and $86.5/wmt, respectively.
Weather-wise, the Philippines' main nickel ore producing areas remain affected by the ITCZ and seasonal rainfall, with Zambales seeing relatively heavy rainfall. Mining, land transport, and port loading at some mines are restricted, and actual shipping capacity has declined. Palawan still maintains a certain level of shipment capability, and overall supply has not yet experienced a full-scale shortage. Additionally, a strong typhoon is moving toward northern Philippines and Taiwan, with its projected path north of the main nickel ore producing areas, but rough sea conditions may still affect port operations and loading.
Demand side, downstream raw material inventories in China are expected to last about two months. Spot purchases are mainly need-based restocking, with limited buying interest. The supply restrictions in Zambales have yet to provide clear support for prices. Ocean freight rates from the Philippines to China remain at a relatively high level, limiting the landed price competitiveness of Philippine ore. Weakening local ore prices in Indonesia have also eroded the price advantage of Philippine ore entering the Indonesian market. Port-wise, nickel ore inventories at the seven major ports rose to 5.8 million wmt (October 30), up 170,000 wmt MoM, while total inventories across all ports in China reached 9.99 million wmt, up 70,000 wmt MoM.
Philippine nickel ore prices are expected to remain in the doldrums in the short term. With the downward revision of Indonesia's HPM in the second half of October, the regional nickel ore price center has shifted further down. If local Indonesian ore prices remain under pressure, Philippine miners may further lower FOB quotes to secure deals. Going forward, attention should be paid to the recovery of Zambales shipments, actual Palawan shipments, and changes in ocean freight rates from the Philippines to China.
Indonesia market:
Price-wise, Indonesian nickel ore prices stabilized this week after earlier declines. As of October 30, at main Indonesian ports, the average price for Ni 1.2% limonite ore was $24.5/wmt, and Ni 1.3% limonite ore was $26.5/wmt. Ni 1.4%, 1.5%, and 1.6% saprolite ore were $47.1, $52.5, and $57.1/wmt, respectively. Previously, the decline in medium- and high-grade saprolite ore was notably larger than that of low-grade limonite ore. The tight supply of high-grade ore has eased somewhat, and market bargaining power has gradually shifted toward buyers.
Policy price-wise, the nickel HMA for the second half of October was $15,847.67/mt, down $475/mt or 2.91% from the first half. HPM was revised down accordingly, with Ni 1.2% at $22.44/wmt, Ni 1.4% at $50.05/wmt, Ni 1.5% at $54.48/wmt, and Ni 1.6% at $59.12/wmt, further lowering the reference for miner quotes. Looking ahead to next year, Indonesia's Directorate General of Mineral and Coal stated that potential nickel ore production reflected in 2027 RKAB applications has exceeded 500 million mt. When setting quotas, the Ministry of Energy and Mineral Resources will take into account global nickel market supply and demand as well as domestic smelter demand. The revised production quota for 2026 is approximately 290 million to 300 million mt, higher than the 260 million to 270 million mt set at the beginning of the year.
In terms of supply, the supplementary RKAB quotas were gradually released in 2026. Mines that obtained new quotas still need to carry out equipment allocation, road maintenance, inventory preparation, and logistics arrangements. An increase in quotas does not mean an immediate increase in spot supply, but nickel ore supply still has room for further growth in Q4. On the demand side, Indonesian smelters' raw material inventories can sustain operations for about two months, limiting the incentive for concentrated short-term restocking. Persistent dry conditions brought by El Niño and insufficient industrial water supply have affected some smelting facilities in Morowali, with some RKEF production lines operating at about 30%–40% of normal capacity since September 22, reducing ore consumption accordingly.
The Indonesian nickel ore market is expected to remain weak in the short term. On the supply side, attention should be paid to the pace at which newly approved RKAB quotas translate into actual production and shipments. On the demand side, focus should be on smelter inventory drawdowns, industrial water supply in Morowali, and the recovery of affected RKEF production lines. If new supply continues to be released while smelter purchases remain constrained, Indonesian nickel ore spot prices will face further downward pressure.