[SMM Hot Rolled Arrivals] Arrivals in Mainstream Markets Near Trough This Week

Published: Nov 03, 2026 18:32 (GMT+8)

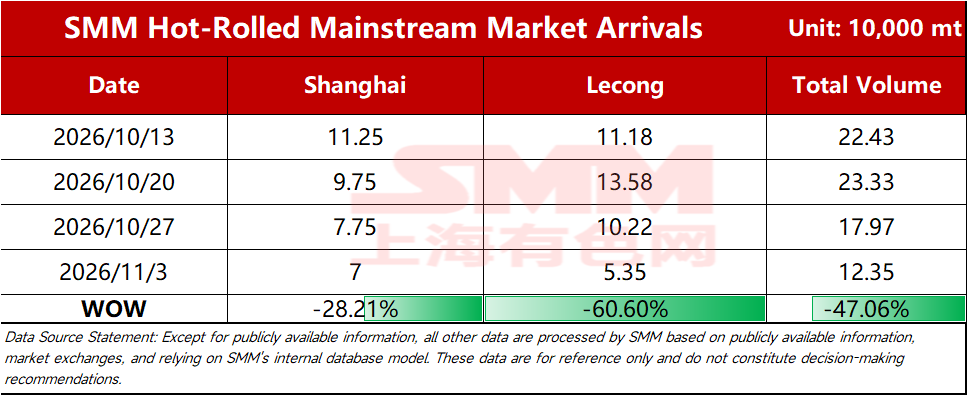
SMM Steel, November 3: According to SMM statistics, total resource shipments to mainstream markets this week are estimated at 123,500 mt, down 31.27% WoW. By market:  

Table 1: Arrivals Comparison Across Mainstream Markets  
Source: SMM Steel  

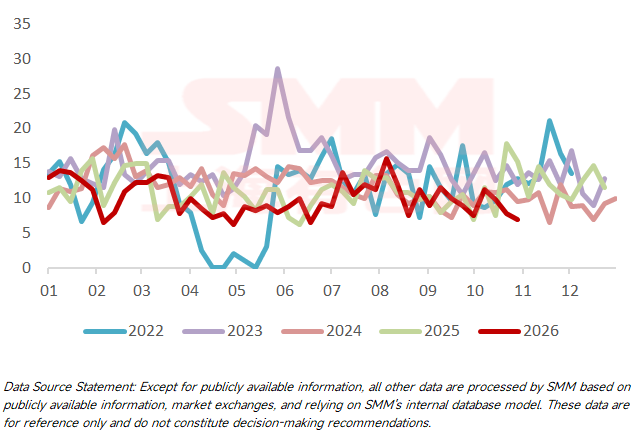
Shanghai Market: HRC shipments to the Shanghai market changed narrowly this week. Specifically, shipments of resources from both north and south China were basically flat WoW; resources from south China continued to focus on special steel production, with arrivals remaining low. Looking ahead, the price difference between north and south China lacks attractiveness, making it difficult for northern resources to see significant growth in the short term, while southern resources are expected to see some supply increase. Therefore, SMM expects shipments to the Shanghai market to rebound in the short term.  

Chart-1: Arrivals in Shanghai Market  
Source: SMM Steel  

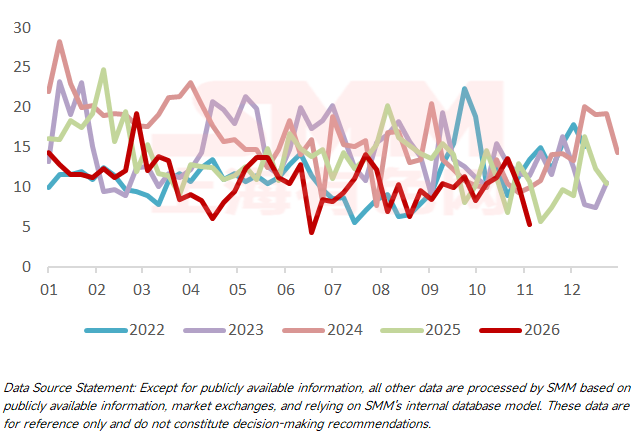
Lecong Market: Arrivals to Lecong continued to weaken this week. Specifically, arrivals of northern resources edged up, but arrivals of the two major mainstream resources continued to decline: DDH was dragged down by shipping disruptions, while WG remained focused on producing special steel. Under the combined effect of multiple factors, overall arrivals to Lecong continued to pull back WoW. Looking ahead, constrained by regional price spreads, profits for shipping northern resources southward are limited, and arrivals of northern resources may remain low; local mainstream resources have room for growth. Overall, arrivals to the Lecong market are expected to rebound in the short term.  

Chart-2: Arrivals in Lecong Market  
Source: SMM Steel  

SMM releases HRC shipment data for mainstream markets every Tuesday. To subscribe or follow more data, please scan the QR code below. 
Data Source Statement: Except for publicly available information, all other data are processed by SMM based on publicly available information, market communication, and relying on SMM's internal database model. They are for reference only and do not constitute decision-making recommendations.

For any inquiries or for more information, please contact: lemonzhao@smm.cn
For more information on how to access our research reports, please contact:service.en@smm.cn
Related News
[SMM Sheets & Plates Daily Review] Cost decline vs.supply contraction expectations, futures pulled back again intraday
3 hours ago
[SMM Sheets & Plates Daily Review] Cost decline vs.supply contraction expectations, futures pulled back again intraday
Read More
[SMM Sheets & Plates Daily Review] Cost decline vs.supply contraction expectations, futures pulled back again intraday
[SMM Sheets & Plates Daily Review] Cost decline vs.supply contraction expectations, futures pulled back again intraday
HRC futures remained weak and fluctuated today, with the most-traded HC2701 contract closing at 3,147 yuan/mt, down 0.54% intraday. Spot market transaction prices fell 10 yuan/mt from the previous session, with intraday deals generally on the weak side. News flow was mixed. Intraday reports said Mongolian coal customs clearance resumed, leading coking coal lower. Meanwhile, talk that coke producers would stabilize prices and ensure supply, and that the three major mills would make additional production cuts of 5%-8%, both underpinned finished steel prices and capped the upside. In terms of supply, HRC impact from maintenance this week was 144,400 mt, up 17,100 mt WoW. Next week, HRC impact from maintenance is expected at 218,300 mt, up 74,000 mt WoW, with production continuing to pull back. On the demand side, northern regions are gradually entering the construction off-season, outdoor project procurement volume is seeing a seasonal pullback, and the slower pace of manufacturing order recovery is keeping sheets and coils under pressure. With cost decline offsetting supply contraction expectations, HRC prices are expected to remain in the doldrums in the near term, with focus on whether market news actually materializes.
3 hours ago
[SMM Steel] Vietnam HRC Import Prices Edge Higher as Domestic Offers Exceed Indonesian Cargoes
3 hours ago
[SMM Steel] Vietnam HRC Import Prices Edge Higher as Domestic Offers Exceed Indonesian Cargoes
Read More
[SMM Steel] Vietnam HRC Import Prices Edge Higher as Domestic Offers Exceed Indonesian Cargoes
[SMM Steel] Vietnam HRC Import Prices Edge Higher as Domestic Offers Exceed Indonesian Cargoes
[Vietnam] HRC import prices rose by 2 USD/tonne to 531 USD/tonne CFR Vietnam. Two Indonesian mills reportedly sold substantial volumes of SAE1006 HRC at 532 USD/tonne CFR Vietnam last week, for December–January delivery. A major Vietnamese steelmaker announced December-delivery offers for SAE1006 and SS400 HRC at approximately 559–560 USD/tonne CIF Vietnam. While prices remained unchanged in Vietnamese dong, their USD equivalents increased due to exchange-rate movements. With domestic offers significantly higher than Indonesian imports, Vietnamese buyers remained cautious about placing orders.
3 hours ago
[SMM Steel]
3 hours ago
[SMM Steel]
Read More
[SMM Steel]
[SMM Steel]
[Sheets & Plates] Today, export prices for HRC and some other sheets & plates fell $2-3/mt WoW, with HRC transaction prices concentrated in the $478-485/mt range. Steel mills in north China, with order books extending far ahead and severe port congestion, maintained relatively high offers; some second-tier export producers lowered prices, with offers at $480/mt. Overseas conditions remained subdued, with a strong wait-and-see sentiment.
3 hours ago
Register to Continue Reading
Gain access to the latest insights in metals and new energy
Already have an account?Sign in here