Concentrate Output Eases as Purchased Feed Recovers From Q2
The 804,300 ounces of metal in concentrate (M&C) comprised 511,900 ounces from Valterra’s own mines and 292,400 ounces from purchased concentrate. Against Q3 2025, the two sources fell 5% and 7%, respectively. Yet total M&C rose 4% from Q2 2026: purchased feed increased by 17% quarter on quarter while mine output fell 3%. M&C is the metal contained in the intermediate concentrate, before final refining. Valterra reports it on a 5E+Au basis: platinum, palladium, rhodium, ruthenium and iridium plus gold.[2]
The longer view is less weak than the quarter alone suggests. For January to September, M&C reached 2.323 million ounces, essentially level with 2.320 million ounces a year earlier. Own-mined output increased 4% to 1.524 million ounces, offsetting a 6% decline in purchased concentrate to 799,500 ounces. Valterra also concluded two new concentrate purchase agreements with Tharisa during Q3, although this report does not quantify their future deliveries.[2]
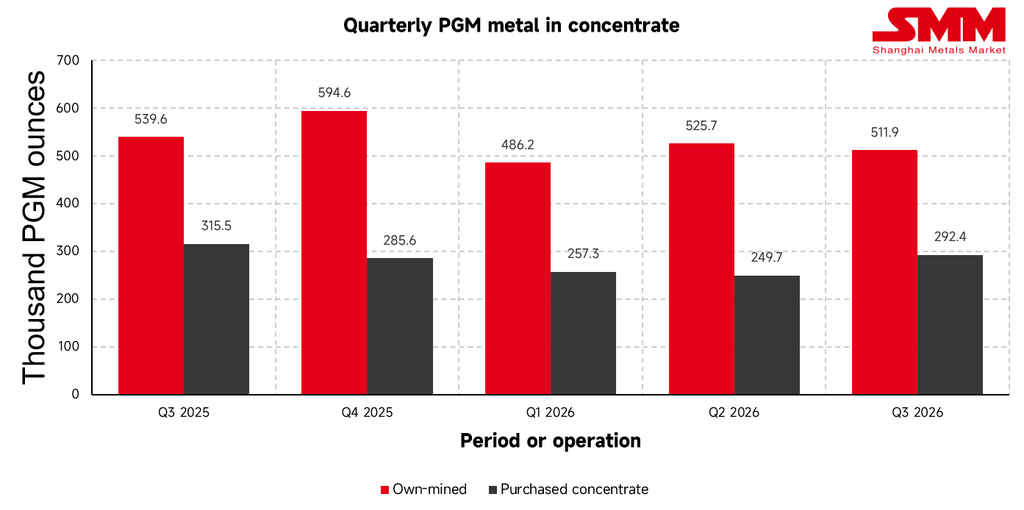
Figure 1. Own-mined and purchased concentrate, Q3 2025 to Q3 2026. Source: Valterra Platinum Q3 2026 production report [2].
Safety Stoppages Weigh on Amandelbult and the Mine Mix
A fatal fall-of-ground incident at Amandelbult’s Tumela mine in July was followed by regulatory and company-imposed safety stoppages. Amandelbult produced 137,900 PGM ounces, down 10% year on year. Valterra says the operation returned to steady-state production by quarter-end, with a step-up expected in Q4. That expected improvement remains a company outlook, rather than reported production.[1]
Mogalakwena remained the largest mine at 217,600 ounces, down 4% as milling throughput fell after the Baobab concentrator lease expired at the end of 2025. Mototolo rose 7% to 70,800 ounces on stronger Borwa shaft performance and the Der Brochen ramp-up. Unki in Zimbabwe fell 12% to 50,600 ounces as lower grade, waste dilution and planned plant maintenance affected output. Valterra’s 50% own-mined share of Modikwa declined 5% to 35,000 ounces. These quarter-on-quarter and year-on-year comparisons should not obscure Amandelbult’s 33% nine-month increase against the flood-affected 2025 base.[2]
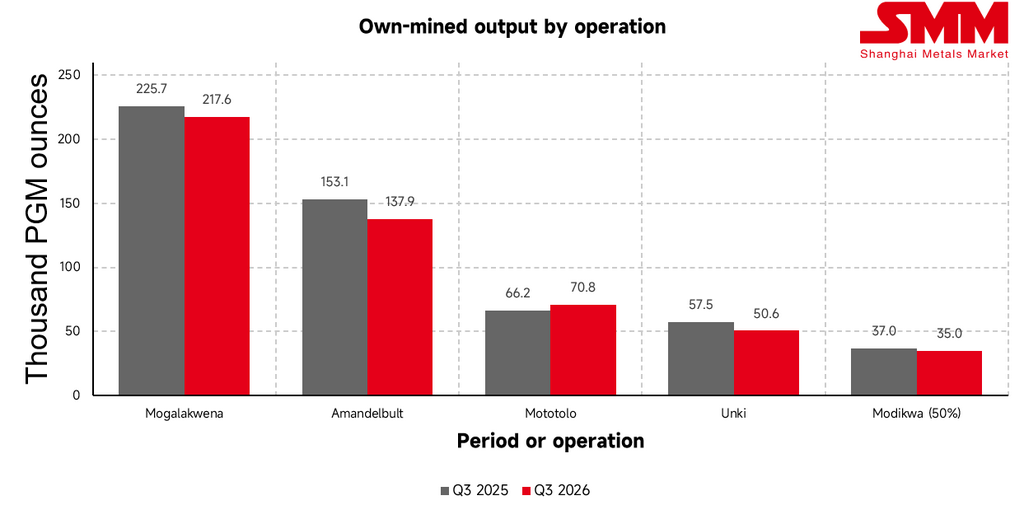
Figure 2. Q3 output at the five operations. ¹ Modikwa shows Valterra’s attributable 50% share. Source: Valterra Platinum Q3 2026 production report [2].
Refining and Sales Reflect the Maintenance Calendar
Owned refined production, excluding toll refining for other owners, dropped from 981,500 ounces in Q3 2025 to 576,900 ounces in Q3 2026. It was also 40% below Q2. Valterra moved scheduled processing maintenance and annual stock counts from the first quarter into Q3. Processing plants had fully ramped up by the end of August and operated at unconstrained rates in September, according to the company. The quarterly fall in finished metal therefore measures plant timing as well as mine supply.[1]
Sales declined to 683,300 ounces, 27% below a year earlier, with a drawdown of refined inventory partly cushioning the lower refinery output. For the nine months, owned refined output was 2.319 million ounces, down 2%, while sales of 2.420 million ounces were broadly in line with 2025. The realised PGM basket price averaged R38,815 per ounce, up 15% year on year, or US$2,383, up 24%. Both measures fell from Q2 2026 (R44,708 and US$2,710). The basket price is the average realised price across the metals sold, so its increase cannot by itself establish quarterly revenue or profit.[2]
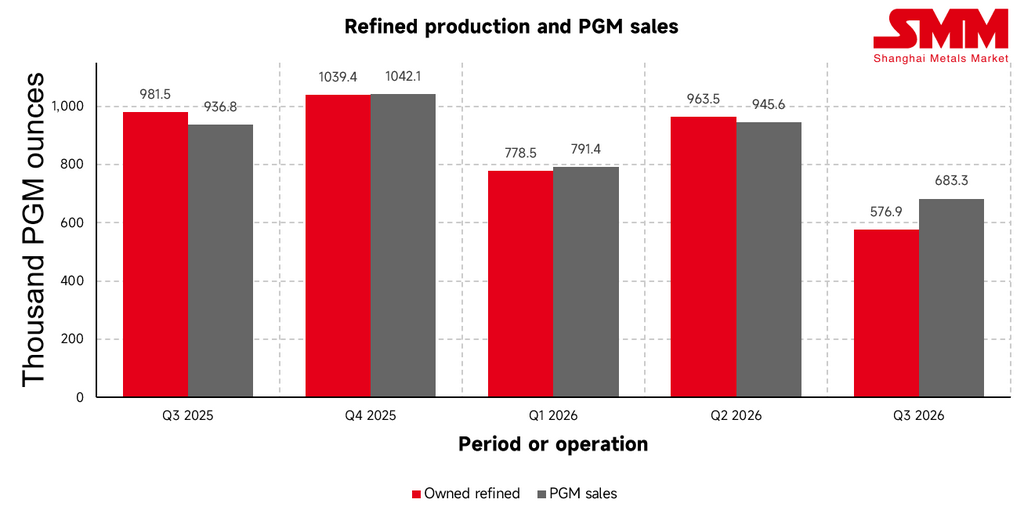
Figure 3. Owned refined PGM production and PGM sales; the two series are distinct from M&C supply. Source: Valterra Platinum Q3 2026 production report [2].
Guidance Holds, With Costs Near the Upper End
Valterra kept its 2026 M&C and owned refined production guidance at 3.0–3.4 million ounces for each measure. Given the nine-month totals, the lower end requires roughly 677,000 ounces of M&C and 681,000 ounces of refined metal in Q4. These are arithmetic thresholds, not company forecasts. Reaching the lower refined threshold would require a recovery from Q3’s 576,900 ounces; the company’s September processing run rate and Amandelbult’s return to steady production are relevant to that prospect.[2]
Cash operating unit costs are expected at or around the top of the R19,000–R20,000 per PGM ounce guidance range as consumables inflation and safety stoppages put pressure on volumes. The separate all-in sustaining cost target remains approximately US$1,050 per 3E ounce, on a different metal and currency basis. The final quarter will show how much of the lost refined output was a shift in timing and how fully the mines recover while safety measures remain in force.[1]
Sources and Chart Notes
[1] Valterra Platinum. Production report for the third quarter ended 30 September 2026, 23 October 2026. Company announcement
[2] Valterra Platinum. Q3 2026 production report, JSE SENS announcement and operating tables, 23 October 2026. Full announcement
All figure values are company-reported. Volumes are thousand PGM troy ounces and may differ by 0.1 when rounded.