Mineral Resources (MinRes) released its quarterly activity report for Q1 FY27 (July-September 2026) on 23 October 2026. Its flagship Onslow Iron project produced 10.26 million wmt on a 100% basis, up 17.2% quarter on quarter and a quarterly record. Shipments were 9.22 million wmt, down 3.9% on the quarter and up 6.8% year on year. Lump rose to 43% of Pilbara Hub shipments from 34% in the previous quarter. The company maintained FY27 production and cost guidance across all divisions.
01 Production and sales overview
Record output at Onslow Iron
Crusher feed at Onslow Iron came from Ken's Bore, Upper Cane and Cardo Bore East. Production reached 10.26 million wmt (100%), up 17.2% on the quarter and 21.4% on the year. Haulage to the Port of Ashburton was 9.32 million wmt, so production exceeded haulage by about 0.94 million wmt (SMM calculation based on company data). The company carried out maintenance on the port in-load circuit early in the quarter. Once the circuit was back in full service, September exports reached 3.49 million wmt (100%), above the previous high of 3.28 million wmt set in June 2026. A total of 45 vessels were loaded and 9.22 million wmt shipped, an annualised run rate of about 36.9 million wmt, above the 35 Mtpa design capacity the company disclosed earlier.
Attributable shipments ease on the quarter
MinRes' attributable iron ore shipments totalled 7.94 million wmt, down 5.6% on the quarter and up 3.9% on the year. Onslow Iron attributable shipments were 5.02 million wmt, down 12.1% on the quarter. Their share of 100% shipments fell to 54.4% from 59.5%; the company did not explain the change. MinRes said attributable volumes are expected to average its 57% direct equity share over the life of the project. The wholly owned Pilbara Hub produced 3.18 million wmt, up 55.1% on the quarter, and shipped 2.92 million wmt, up 8.2%.
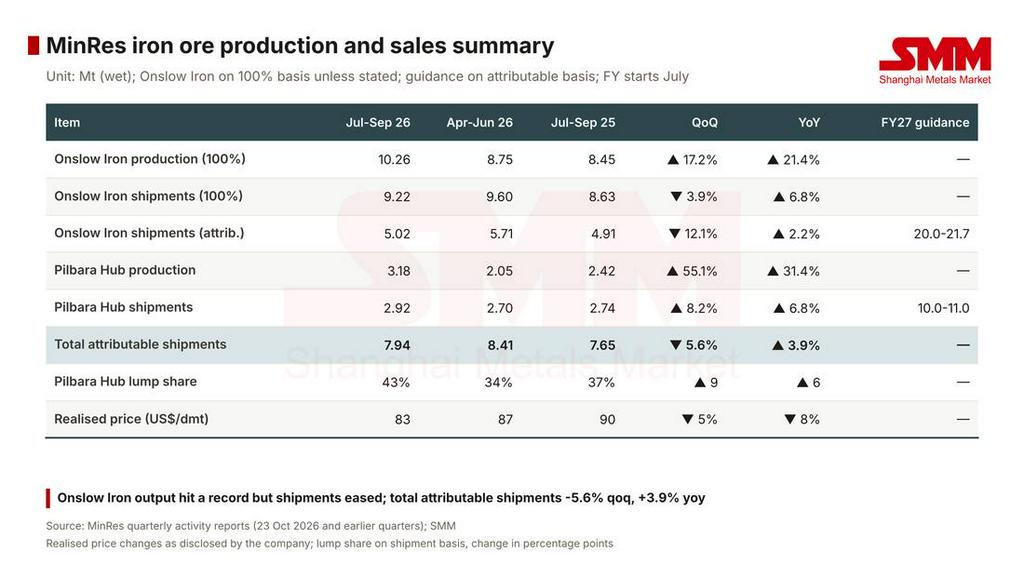
Figure 1: MinRes iron ore production and sales summary (Mt). Source: MinRes quarterly activity report, SMM
02 Product mix and operations
Pilbara Hub lump share rises to 43%
Lump made up 43% of Pilbara Hub shipments, up 9 percentage points from 34% in the previous quarter and above 37% a year earlier. The share ranged between 32% and 43% over the past five quarters. This lifted the lump share of MinRes' total attributable shipments to 16% from 11%. The company gave no separate reason for the higher lump share this quarter.
Lamb Creek in full operation
Lamb Creek, part of the Pilbara Hub, broke ground in December 2025 and shipped its first ore in March 2026. It moved from commissioning to full operation this quarter, which the company said took less than a year from breaking ground. MinRes' Engineering and Construction team delivered the fixed crushing plant, mine access road, administration buildings and a 200-person village.
Grade and realised prices
Onslow Iron's Fe grade was 58.3%, unchanged on the quarter; Pilbara Hub's was 57.6% (57.4% in the previous quarter). The weighted average realised price across both operations was US$83/dmt, down 5% on the quarter and equal to 85% of the 61% Fe CFR index. Onslow Iron realised US$83/dmt, or 86% of the index (82% in the previous quarter), and Pilbara Hub US$81/dmt, or 84%. The company has reported realisation against the 61% Fe index since January 2026; earlier quarters were reported against the 62% Fe index.
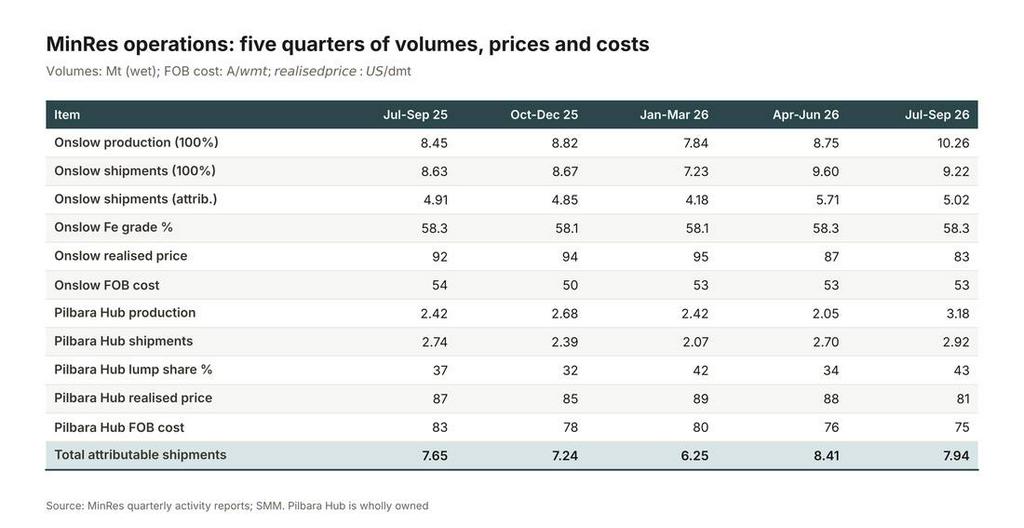
Figure 2: MinRes operations: five-quarter volumes, prices and costs. Source: MinRes quarterly activity report, SMM
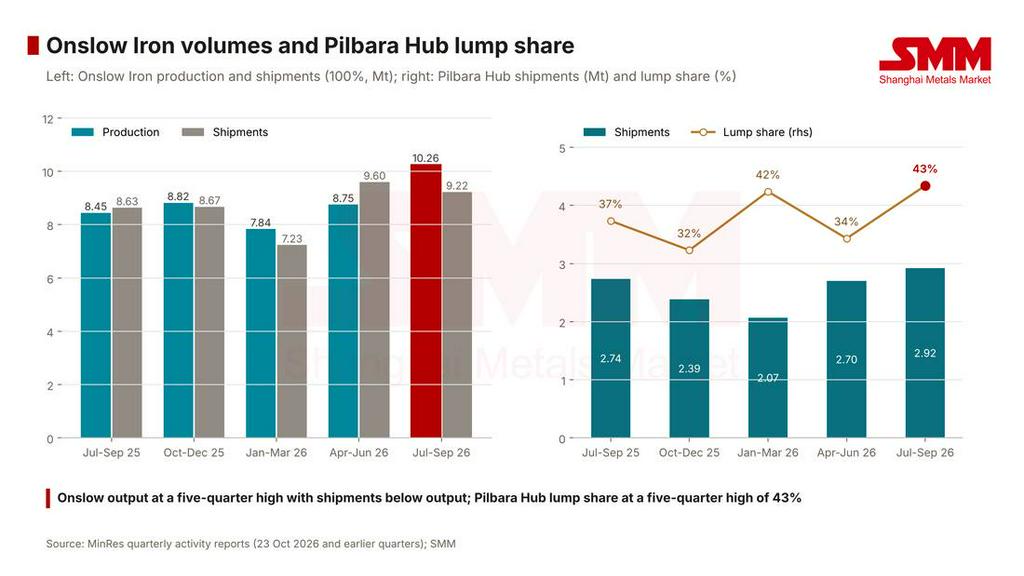
Figure 3: Onslow Iron production and shipments; Pilbara Hub shipments and lump share (Mt, %). Source: MinRes quarterly activity report, SMM
03 Guidance and costs
Progress against guidance
MinRes maintained its FY27 volume guidance: 20.0-21.7 million wmt of attributable shipments at Onslow Iron and 10.0-11.0 million wmt at the Pilbara Hub. Based on company data, SMM calculates that Onslow Iron's Q1 attributable shipments covered 25.1% of the low end and 23.1% of the high end, requiring a quarterly average of 4.99-5.56 million wmt over the remaining three quarters, in line with the 5.02 million wmt shipped this quarter. The Pilbara Hub covered 29.2% of the low end and 26.6% of the high end, requiring 2.36-2.69 million wmt a quarter, below the 2.92 million wmt shipped this quarter.
Unit costs
Onslow Iron's FOB cost was A$53/wmt, flat on the quarter and below the A$54-58/wmt guidance range. The Pilbara Hub's FOB cost was A$75/wmt, down A$1 on the quarter and within guidance of A$74-79/wmt.
Diesel costs
FY27 cost guidance assumes diesel at A$1.25 per litre, broadly in line with the quarterly average. Diesel rose to about A$1.60 per litre in September, which will flow into FOB costs from October because of a one-month pricing lag. The company estimates the 35-cent increase will add about A$1/wmt at Onslow Iron and A$2/wmt at the Pilbara Hub. MinRes said fuel supply and operations were not disrupted in the quarter and, at current prices, it expects FY27 FOB costs to remain within guidance. Freight rates, which respond more quickly to diesel, rose in September.
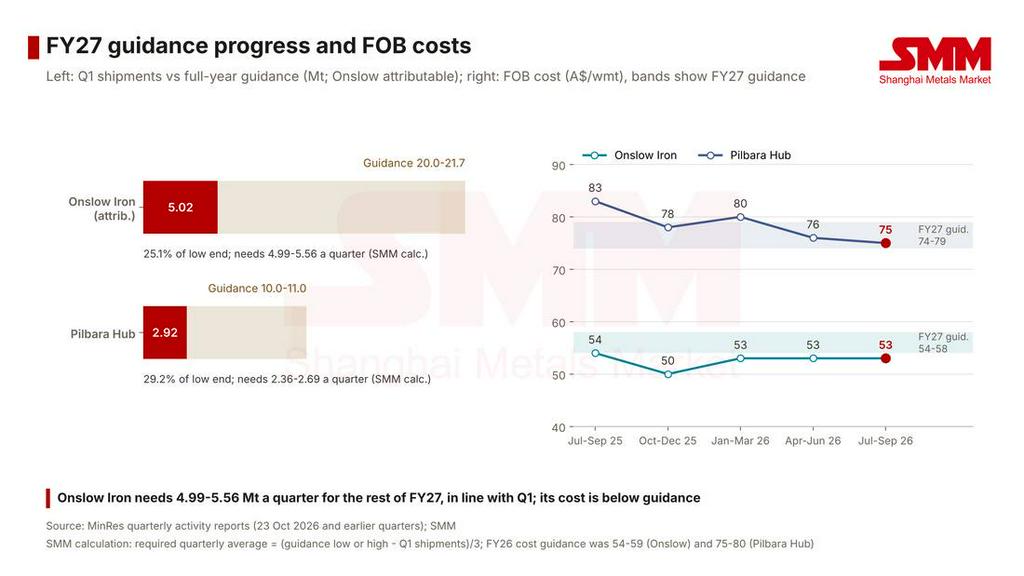
Figure 4: Progress against FY27 guidance and FOB costs (Mt, A$/wmt). Source: MinRes quarterly activity report, SMM
04 Capacity milestones and progress
Capacity milestones this quarter centred on Onslow Iron's port and marine logistics.
Seventh transhipper commissioned
The seventh transhipper, MinRes Karri, was commissioned in August. With seven vessels, six will operate while one rotates through scheduled maintenance; the first transhipper was sent to Singapore for maintenance during the quarter.
Port dredging
The first part of the scheduled dredging campaign is complete. Dredging will resume in mid-November and is scheduled to finish by end-December 2026 (end of Q2 FY27), with only a minimal impact on volumes expected.
Supporting infrastructure and exploration
Non-processing infrastructure, including heavy-vehicle facilities at Upper Cane and a truck management facility at Ken's Bore, is on track for completion by end-December 2026. Construction of the 270-room Onslow Iron Resort resumed in July, with completion expected in early FY28. On exploration, 692 m of RC drilling was completed at Onslow Iron and 694 m at Lamb Creek to support resource extension.
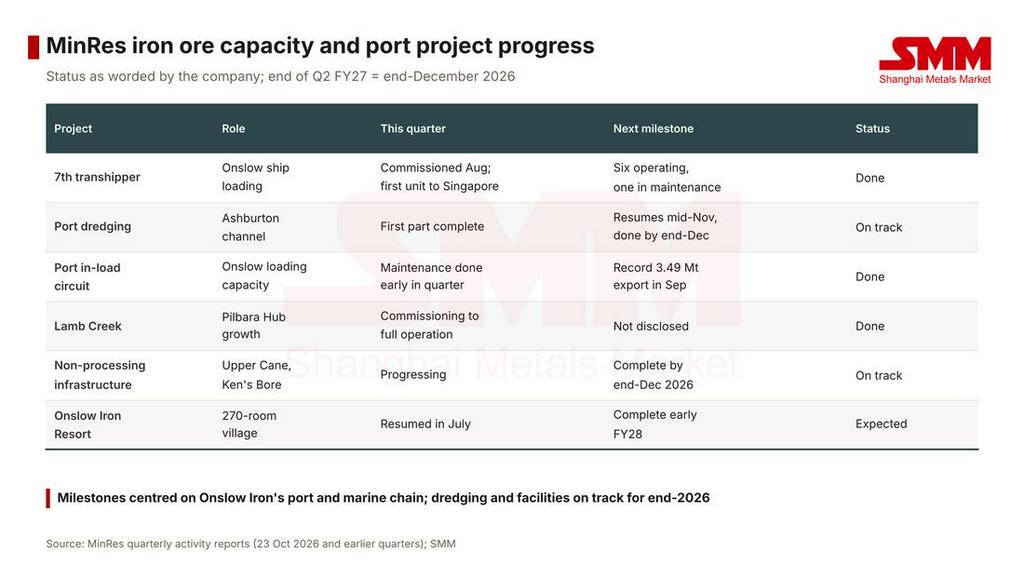
Figure 5: MinRes iron ore capacity and port project progress. Source: MinRes quarterly activity report, SMM
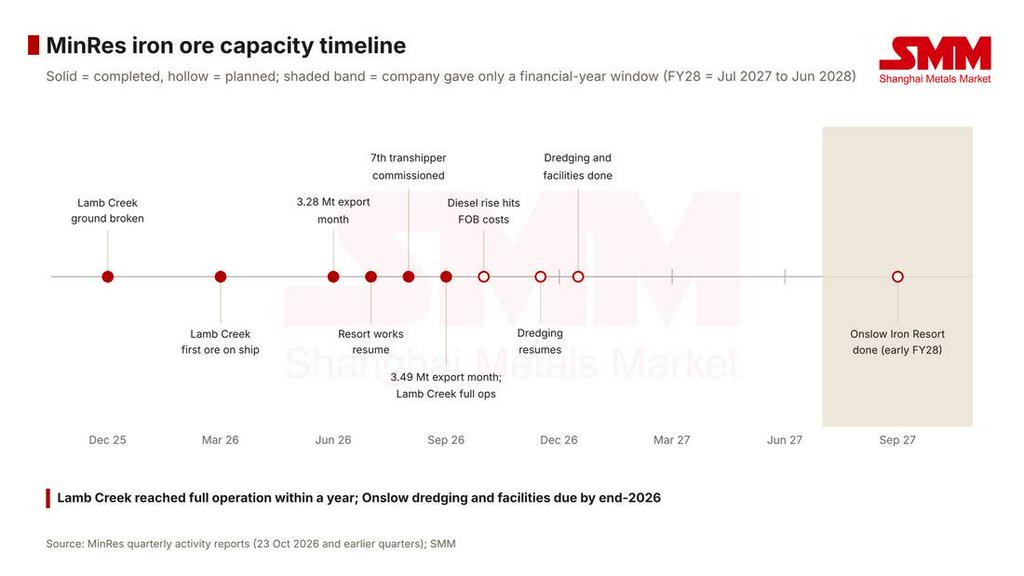
Figure 6: MinRes iron ore capacity timeline. Source: MinRes quarterly activity report, SMM
05 What to watch next quarter
First, whether Onslow Iron can sustain its September export pace. Dredging resumes in October-December, with minimal impact expected, and the transhipper fleet moves to six operating and one in maintenance. Attributable shipments need to average 4.99-5.56 million wmt over the remaining three quarters. If October-December attributable shipments hold above this quarter's 5.02 million wmt, the full year would land within guidance; if dredging or transhipper maintenance slows loading, the gap of about 0.94 million wmt between production and haulage could widen further.
Second, whether the Pilbara Hub lump share holds. This quarter's 43% was the highest in five quarters, Lamb Creek has only just entered full operation, and the company did not explain the increase. If the share stays above 40%, a sizeable part of the Pilbara Hub's additional output would ship as lump; if it falls back into the 30% range, the increase would come mainly as fines.
Third, how the diesel increase feeds into costs from October. Based on the company's estimates, SMM calculates Onslow Iron's FOB cost would rise to about A$54/wmt, still at the low end of guidance, and the Pilbara Hub's to about A$77/wmt, mid-range. Further diesel gains would push the Pilbara Hub closer to the A$79/wmt top of guidance.
06 SMM commentary
Onslow Iron produced 10.26 million wmt in the quarter, while shipments were back-loaded: the port in-load circuit was under maintenance early on, and September exports reached 3.49 million wmt once it returned. Production exceeded haulage by about 0.94 million wmt, showing mine capacity running ahead of the port and transhipping chain; the seventh transhipper should ease that constraint.
For China's imported ore market, MinRes supplies mainly mid-grade ore at around 58% Fe. If Onslow Iron keeps its September pace in October-December, quarterly shipments could set a new record, with the increase concentrated in mid-grade fines. The higher Pilbara Hub lump share put lump shipments at about 1.26 million wmt this quarter (SMM calculation based on company data), a limited addition to lump supply. With guidance maintained and cost headroom intact, the main swing factors for supply are port dredging and transhipper maintenance.