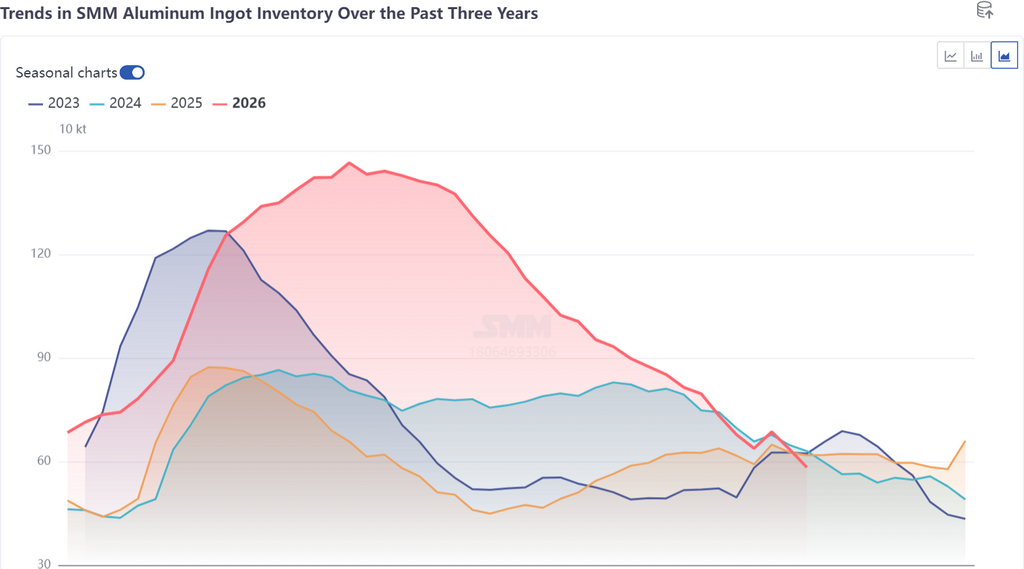
According to SMM statistics, as of October 22, electrolytic aluminum ingot inventories in China's major consuming regions stood at 583,000 mt, down 53,000 mt from last Thursday and 55,000 mt lower than the pre-holiday level (September 30). The further-accelerated post-holiday destocking has brought domestic inventories to the lowest level for the same period in nearly four years.
In Q4, the core logic behind domestic aluminum ingot destocking still lies on the supply side. With processing fees for semi-fabricated products such as aluminum billets recovering after the holiday, the molten-aluminum ratio has returned to the normal pre-holiday level, significantly easing ingot casting pressure. Meanwhile, the unresolved shortage of rail containers in Xinjiang, coupled with transport bottlenecks in the Southwest, has effectively offset the gradual release of smelter stock builds resulting from the increased casting during the National Day holiday. On the demand side, the recent decline in aluminum prices has also boosted post-holiday warehouse withdrawals, and steady-to-improving demand is a direct driver of the accelerated destocking.
A key risk lies on the import side. With import parity recovering rapidly and bonded-zone inventories remaining elevated, the likelihood of overseas cargoes flowing into the domestic market continues to rise. Overall, the destocking trend is expected to persist, and although there is some risk of a slowdown, SMM still expects domestic aluminum ingot inventories to fall further to around 550,000 mt by end-October.
Premiums and discounts diverged notably across regions. In South China, aluminum prices rebounded slightly this week, yet spot performance was unusually strained: the actual backwardation structure and monthly spreads remained wide, and the willingness to sell and cash out stayed high. Despite some divergence later in the week, with some players choosing to hold prices and slow the pace of shipments, discount-priced cargoes still dominated intraday circulation. Buyers mainly sought bargains at discounted levels, providing a degree of floor support without sufficient strength to underpin the market. Downstream restocking demand existed but was clearly differentiated in behavior, and trading results were hard to describe as satisfactory. As of Thursday, the South China spot premium over the 2611 contract narrowed sharply by RMB 125/mt week on week to RMB 310/mt.
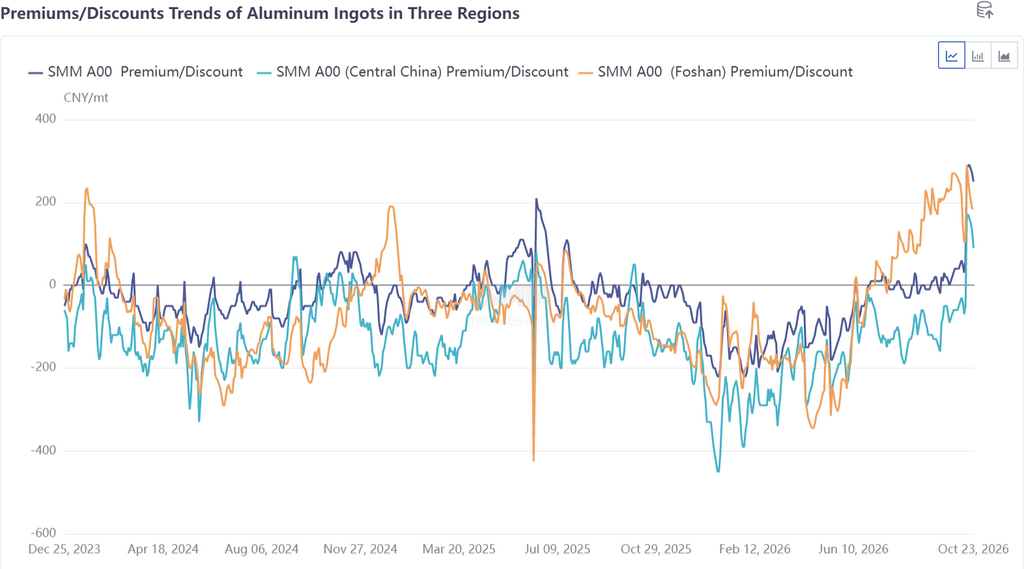
In East China, trading sentiment weakened from strength. At the start of the week, trading was active, with spot premiums over the SHFE Al 2611 contract approaching RMB 300/mt; as aluminum prices rebounded from lows, spot premiums came under pressure and declined. The spread between the SHFE Al 2611 and 2612 contracts has been fluctuating in a backwardation of RMB 250-330/mt, remaining elevated overall, and some holders were reluctant to sell at low prices. The latest A00 spot was quoted at a premium of RMB 260-280/mt over the SHFE Al 2611 contract, with the center of the range higher than last week. Looking ahead to next week, with month-end approaching and long-term contract deliveries largely concluded, spot trading is expected to be quiet, and premiums over the Al 2611 contract are expected to ease to RMB 160-270/mt.
In the Central Plains market, trading sentiment remained subdued. Downstream processors had already purchased in advance during the earlier decline in aluminum prices, and the wide inter-contract spreads pushed quoted premiums higher, which downstream buyers found hard to accept, leaving their purchasing appetite weak. Meanwhile, holders were inclined to offload inventories quickly, with limited price-holding sentiment, dragging quoted premiums lower through the week. Actual transactions in the Central Plains market this week were concluded at discounts of RMB 120-180/mt against the SHFE Al 2611 contract.
On balance, low inventories combined with sustained destocking provide underlying support to the spot market, but under the high-spread structure, regional premiums and discounts have diverged clearly: South China's high premium has narrowed substantially, East China's premium has peaked and pulled back and may ease further next week, while the Central Plains remains in discount. Going forward, watch the pace of import inflows and the winding-down of month-end long-term contract deliveries. Inventories are expected to enter a low-level oscillation after falling to around 550,000 mt by end-October.