

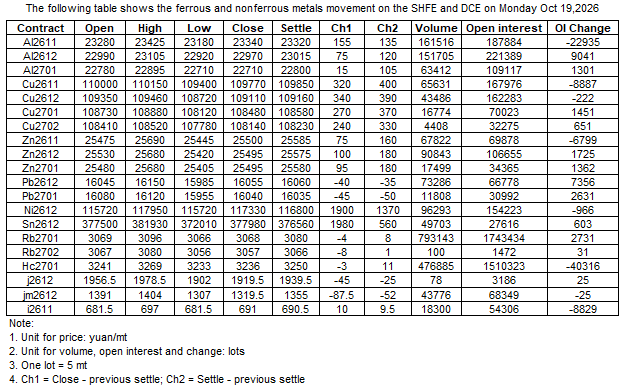
Data: SHFE, DCE market movement (Oct 19)
The following table shows the ferrous and nonferrous metals movement on the SHFE and DCE on 19 Oct , 2026
Data Source Statement: Except for publicly available information, all other data are processed by SMM based on publicly available information, market communication, and relying on SMM's internal database model. They are for reference only and do not constitute decision-making recommendations.
For any inquiries or for more information, please contact: lemonzhao@smm.cn
For more information on how to access our research reports, please contact:service.en@smm.cn
Related News
6 mins ago
[SMM Steel]
Read More
[SMM Steel]
[Steel Billet] Today, export FOB prices for square billet edged up by USD 1/t, with Jiangyin Port quoting USD 460–465/t. According to market feedback, inquiries have been fairly active of late, including from the Middle East. However, domestic finished steel prices in South and East China are more attractive, prompting mills to prioritize domestic supply, leaving overall trading activity moderate-to-weak.
6 mins ago
7 mins ago
[SMM Steel]
Read More
[SMM Steel]
[SMM Steel] Market feedback indicates that the current FOB quote for 3SP square billet, sized 150×150 mm, stands at USD 463/t, with Jiangyin Port as the port of shipment.
7 mins ago
17 mins ago
[SMM Steel] European HRC: Weak Demand Limits Upside Momentum as Supply Curtailments Support Range-Bound Trading
Read More
[SMM Steel] European HRC: Weak Demand Limits Upside Momentum as Supply Curtailments Support Range-Bound Trading
[Europe] European domestic hot-rolled coil (HRC) steel prices remained largely unchanged in flat, range-bound trading. Despite tightening domestic availability caused by planned mill maintenance and operational disruptions, widespread customer inventory overhangs and weak end-user intake continued to cap upward price momentum. In particular, key consuming sectors such as automotive failed to provide recovery support amid a regional economic slowdown, while depressed downstream sheared sheet values limited buyer acceptance of higher primary coil quotes. Regionally, Northwest European workable transaction levels were anchored within 740–760 EUR/tonne EXW (~830–850 USD/tonne). In Southern Europe (Italy), supply curtailments became increasingly pronounced: Acciaierie d’Italia is preparing to idle a blast furnace, Metinvest’s Ferriera Valsider faces severe order backlogs following its operational resumption, and market leader Arvedi reportedly shut down a hot rolling line due to technical issues. Despite these supply reductions, buyers submitted low-ball bids, while mills held firm at 760 EUR/tonne DDP or higher (~850 USD/tonne). However, buyers acknowledged that urgent spot requirements leave little choice but to concede to mill asking levels given tightening supply. On imports, market activity was virtually frozen as tariff-rate quotas (TRQs) for major origins including Turkey and India remain heavily overdrawn. Indian HRC offers were noted between 750–770 USD/tonne CFR, but buying interest was non-existent due to elevated duty and quota exhaustion risks.
17 mins ago
Related News
[SMM Steel]
Oct 19, 2026 16:32 (GMT+8)
[SMM Steel]
Oct 19, 2026 16:31 (GMT+8)
[SMM Steel] European HRC: Weak Demand Limits Upside Momentum as Supply Curtailments Support Range-Bound Trading
Oct 19, 2026 16:21 (GMT+8)
[SMM Steel] Turkish Flat Steel: Domestic and Foreign Trade Stalemate Deepens as TRQs and CBAM Reshape Export Routes
Oct 19, 2026 16:07 (GMT+8)