Import profit margin improves; theoretical import window for aluminum alloy opens [ADC12 Price Daily Review]

Published: Oct 19, 2026 13:19 (GMT+8)
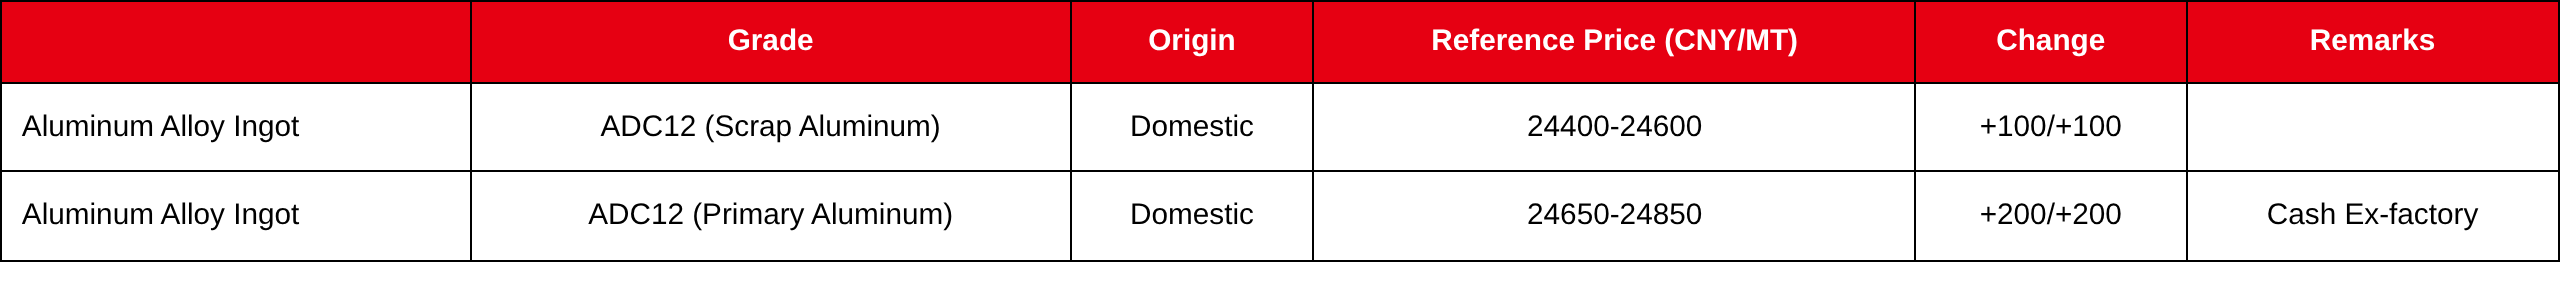
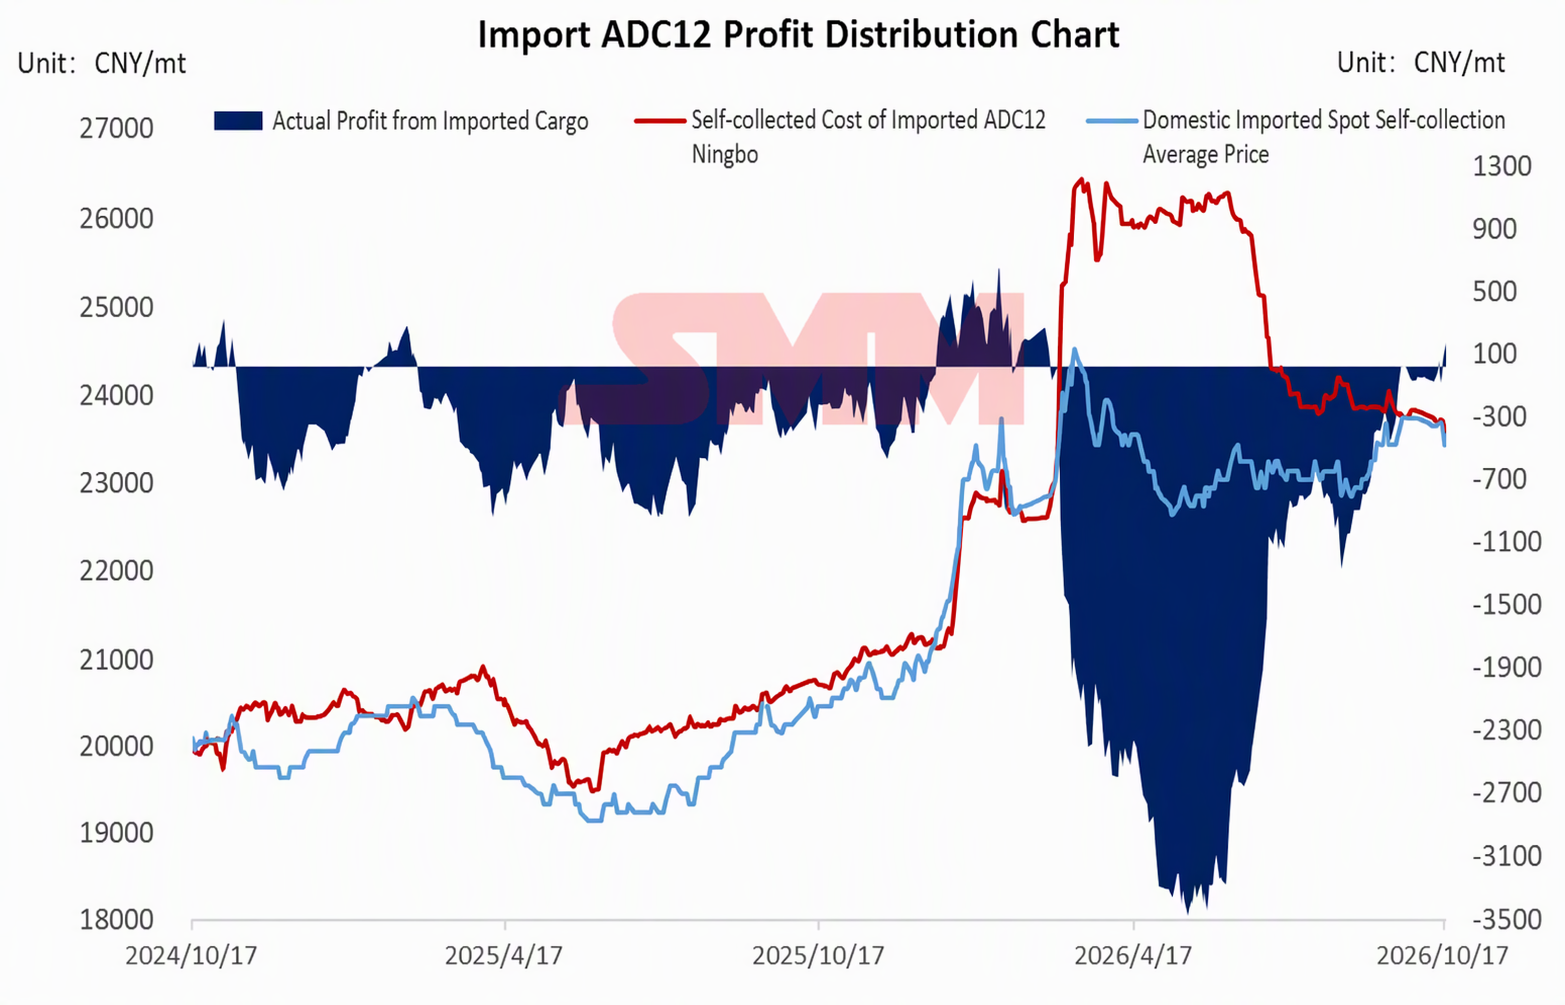
[ADC12 price daily review: import profit margin improves, theoretical import window for aluminum alloy opens] Ex-China ADC12 offers have pulled back slightly to $3,040–3,120/mt. Supported by stronger domestic ADC12 prices and yuan appreciation, the real-time import profit margin has improved and rebounded above the break-even line. The theoretical import window has opened, and future attention should be paid to the impact of changes in ex-China offers and the exchange rate on the inflow of imported supply.

Futures: The most-traded AD2612 cast aluminum alloy contract opened at 22,930 yuan/mt today. After touching a session high of 22,935 yuan/mt in early trading, it met resistance and pulled back, with the price center moving lower in stages. In late trading, it dipped to a session low of 22,795 yuan/mt before rebounding slightly, closing the morning at 22,815 yuan/mt, up 35 yuan/mt, or 0.15%, from yesterday's settlement price.

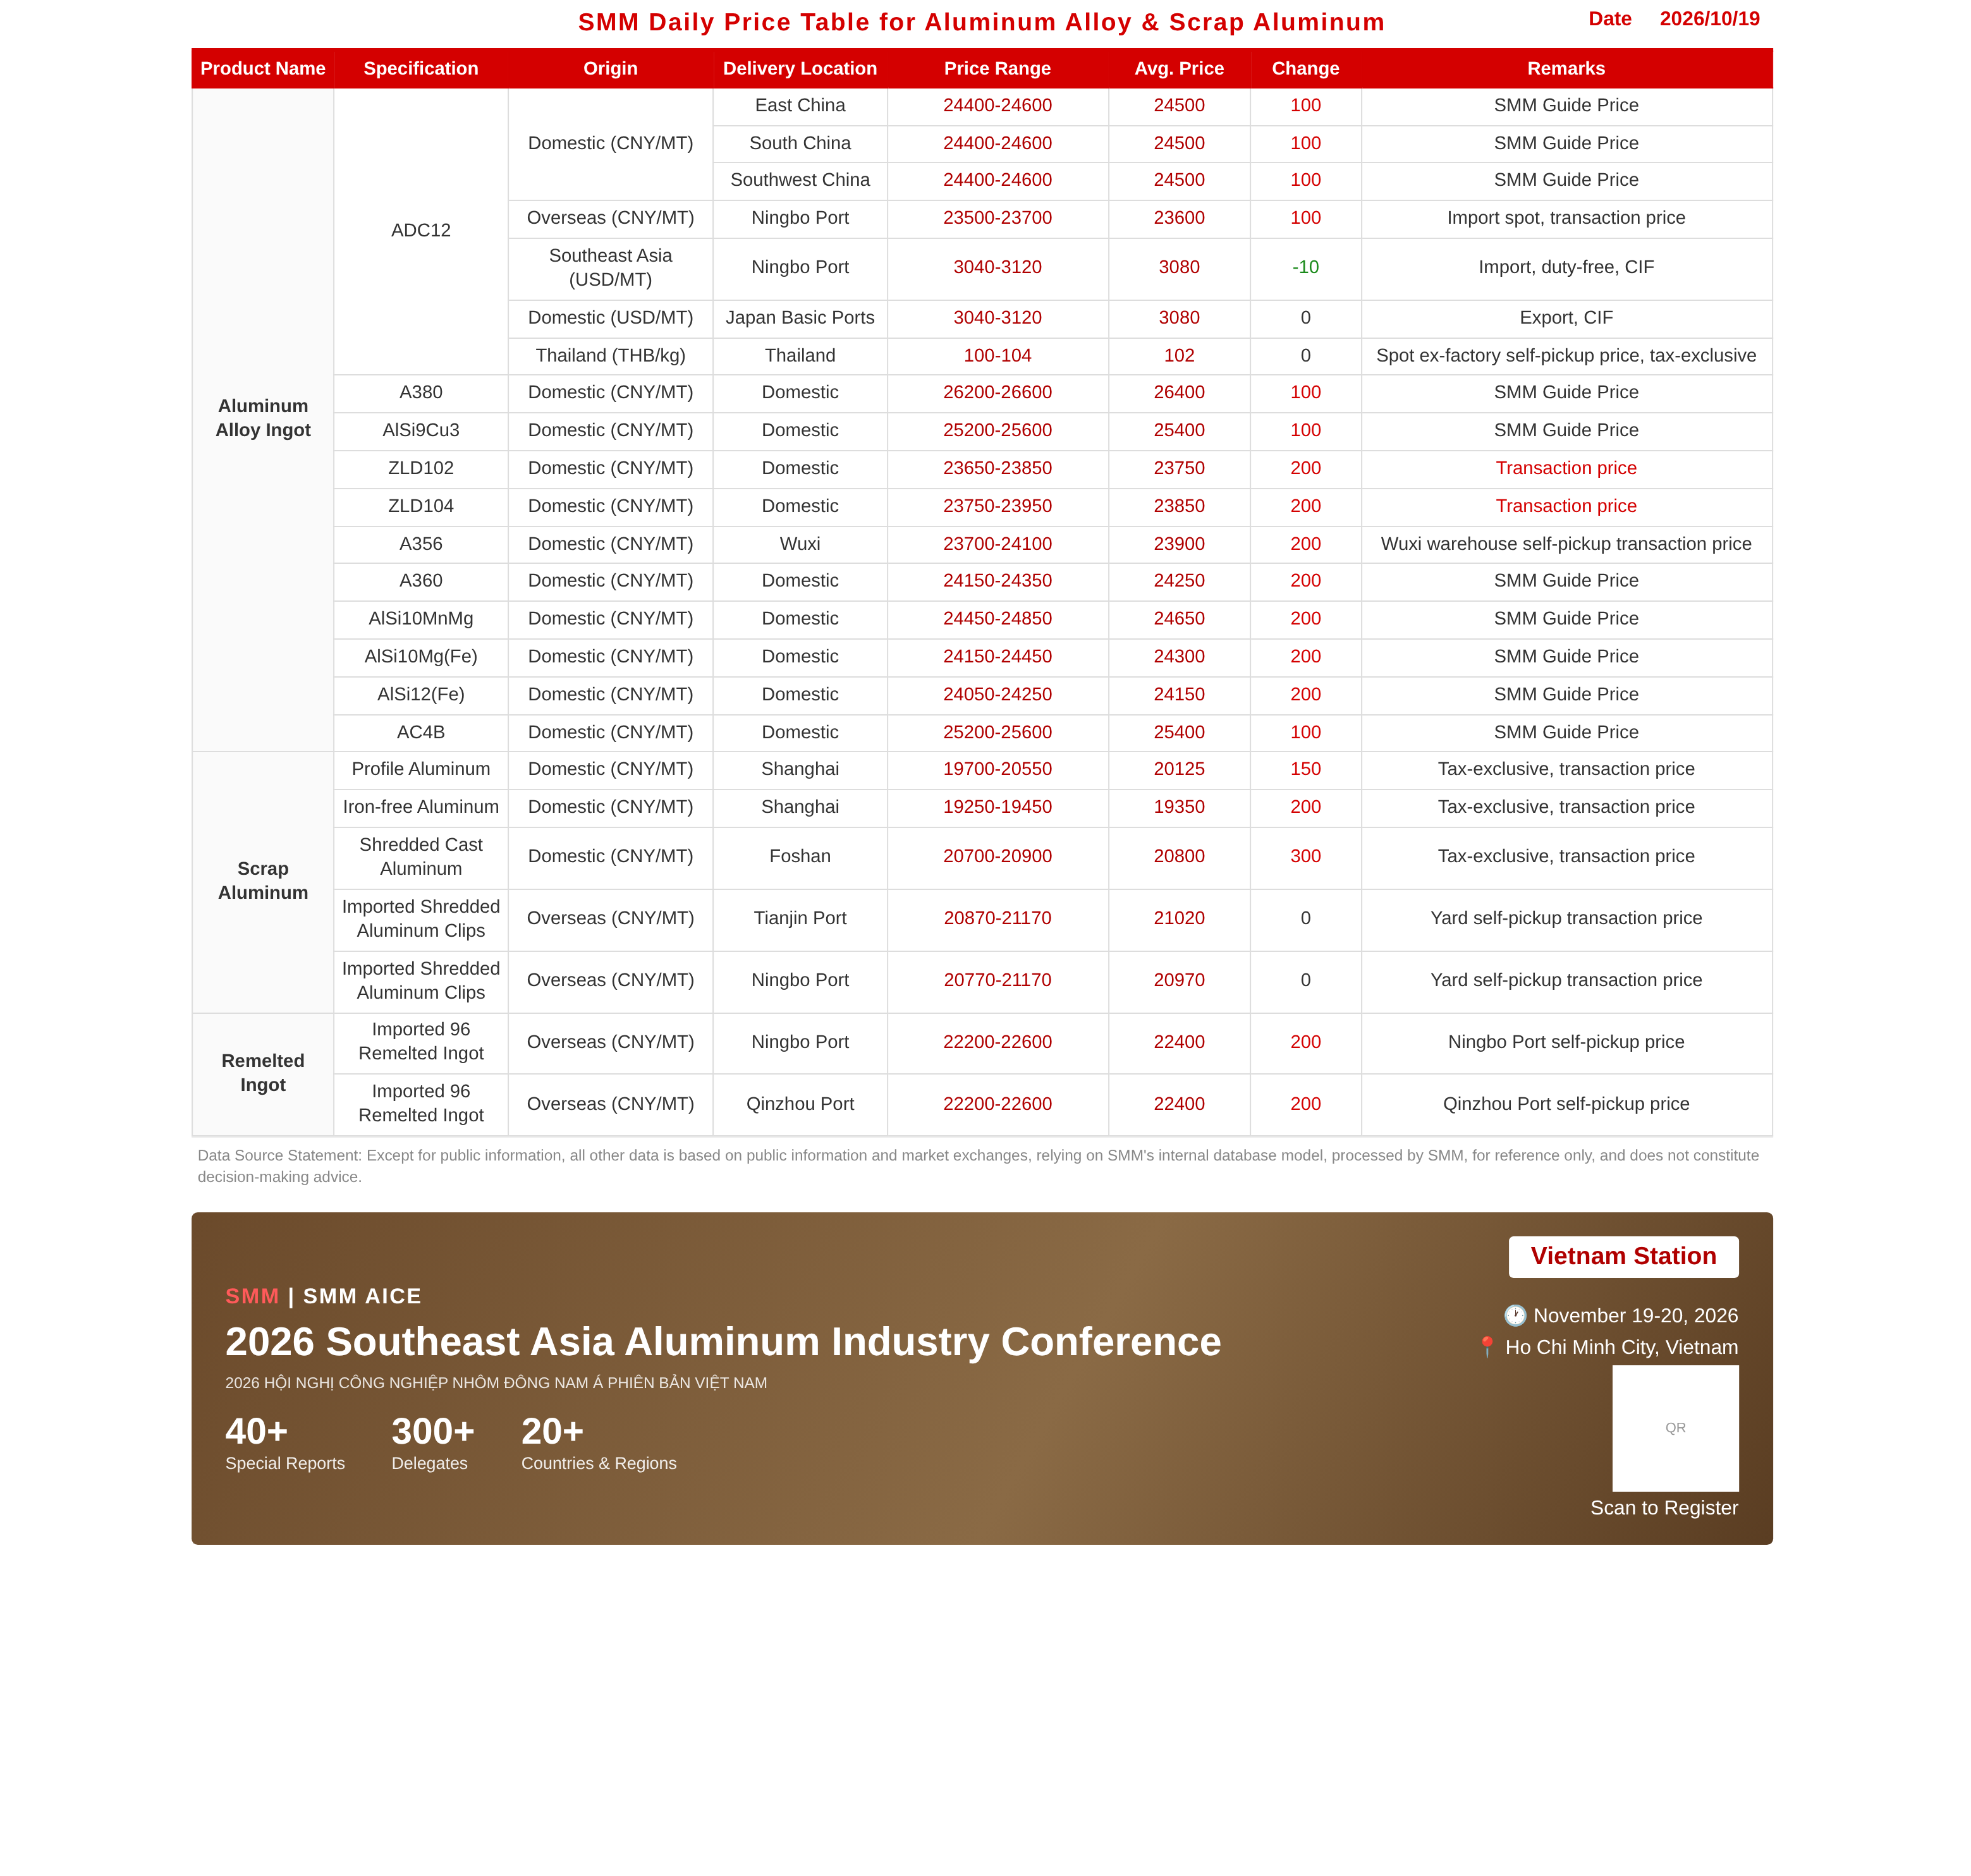
Spot: Spot ADC12 offers moved broadly higher today. The SMM ADC12 market price rose 100 yuan/mt from last Friday to 24,500 yuan/mt. Gains in futures and primary aluminum prices helped repair market sentiment, while raw material cost support strengthened further. Market participants generally raised offers by 100 yuan/mt, and the price center rebounded somewhat. However, downstream feedback suggests end-use demand improvement remains limited, with purchases mostly need-based and acceptance of higher prices relatively constrained. Overall, the current ADC12 market reflects a pattern of cost support and improving sentiment driving a price rebound, while demand follow-through remains relatively insufficient. Prices are likely to continue moving sideways in the short term, but further upside will still depend on aluminum price trends and actual downstream purchasing.

Imports: Overseas ADC12 offers pulled back slightly to $3,040-3,120/mt. Supported by stronger domestic ADC12 prices and yuan appreciation, import breakeven improved and rebounded above the break-even line, with the theoretical import window now open. Attention should remain on changes in overseas offers and exchange rates and their impact on import arrivals.
 

Data Source Statement: Except for publicly available information, all other data are processed by SMM based on publicly available information, market communication, and relying on SMM's internal database model. They are for reference only and do not constitute decision-making recommendations.

Images in this article contain AI-translated captions for reference only.

For any inquiries or for more information, please contact: lemonzhao@smm.cn
For more information on how to access our research reports, please contact:service.en@smm.cn
Related News
【Flash | Sierra Gorda Payable Molybdenum Output Slumps 75% Year on Year】
3 hours ago
【Flash | Sierra Gorda Payable Molybdenum Output Slumps 75% Year on Year】
Read More
【Flash | Sierra Gorda Payable Molybdenum Output Slumps 75% Year on Year】
South32 Limited reported payable molybdenum production of 0.2 thousand tonnes, or about 200 tonnes, from its 45% interest in the Sierra Gorda mine for the September 2026 quarter. Output fell 75% year on year and 50% from the preceding quarter. Payable molybdenum sales were also about 200 tonnes, down 67% year on year and 60% from the preceding quarter. In contrast, payable copper production rose 2% year on year and 17% from the preceding quarter to 18,700 tonnes. South32 cited higher planned copper grades and temporary wet-weather effects but did not explain the molybdenum decline. The figures represent South32’s 45% attributable share, not total mine output or molybdenum concentrate mass.
3 hours ago
【Flash | Centinela Strike Ends Without Disclosed Molybdenum Output Loss】
3 hours ago
【Flash | Centinela Strike Ends Without Disclosed Molybdenum Output Loss】
Read More
【Flash | Centinela Strike Ends Without Disclosed Molybdenum Output Loss】
Antofagasta Minerals’ Centinela mine and the Minera Esperanza and Distrito Centinela unions reached new three-year collective agreements approved by their members, ending the ten-day strike that began on October 7. The two unions represent 709 employees, or 22% of the mine’s directly employed workforce. The company said operational continuity and performance were maintained throughout the stoppage. No shutdown of the molybdenum recovery circuit or loss of contained-molybdenum output has been disclosed. The settlement removes the immediate escalation risk, and there is no current basis for a retrospective molybdenum-output deduction. Centinela’s 2026 contained-molybdenum guidance remains 3,000–3,500 tonnes.
3 hours ago
[SMM Chromium Flash] Global Steel Demand Forecast Turns Flat in 2026 as China Weakens, Recovery Expected in 2027
Oct 16, 2026 22:28 (GMT+8)
[SMM Chromium Flash] Global Steel Demand Forecast Turns Flat in 2026 as China Weakens, Recovery Expected in 2027
Read More
[SMM Chromium Flash] Global Steel Demand Forecast Turns Flat in 2026 as China Weakens, Recovery Expected in 2027
[SMM Chromium Flash] Global Steel Demand Forecast Turns Flat in 2026 as China Weakens, Recovery Expected in 2027
The World Steel Association (worldsteel) revised its global steel demand outlook on 12 October, forecasting demand to remain broadly unchanged at 1.722 billion tonnes in 2026, before increasing by 1.7% to 1.752 billion tonnes in 2027. The downgrade largely reflects weaker-than-expected demand in China, where steel demand is projected to contract by 2.0% in 2026 and a further 1.0% in 2027. Outside China, demand is expected to grow by 1.5% in 2026 and accelerate to 4.0% in 2027. For the chromium market, the subdued global steel outlook suggests that a broad-based recovery in steel-related demand may take longer to materialize, although prospects vary by region. India’s steel demand is forecast to grow by 7.9% in 2026, while demand in the United States is projected to increase by 2.0%. These divergent regional trends provide important context for chrome ore and ferrochrome producers assessing end-market conditions. However, the forecast covers total steel demand rather than stainless steel specifically, so it does not directly quantify future chromium consumption.
Oct 16, 2026 22:28 (GMT+8)
Register to Continue Reading
Gain access to the latest insights in metals and new energy
Already have an account?Sign in here