On October 15, the China Automotive Power Battery Industry Innovation Alliance released September power battery monthly data.
Production side, in September, China's combined production of power and ESS batteries was 237.8 GWh, up 0.3% MoM and up 57.3% YoY.
From January to September, China's cumulative production of power and ESS batteries was 1,833.1 GWh, up 63.4% YoY.
Sales side, in September, China's sales of power and ESS batteries were 222.7 GWh, down 0.2% MoM but up 52.0% YoY. Power battery sales were 149.2 GWh, accounting for 67.0% of total sales, up 1.7% MoM and up 35.0% YoY; ESS battery sales were 73.5 GWh, accounting for 33.0% of total sales, down 3.7% MoM but up 104.4% YoY.
From January to September, China's cumulative sales of power and ESS batteries were 1,681.7 GWh, up 57.6% YoY. Cumulative power battery sales were 1,086.4 GWh, accounting for 64.6% of total sales, up 38.2% YoY; cumulative ESS battery sales were 595.4 GWh, accounting for 35.4% of total sales, up 111.8% YoY.
Exports side, in September, China's combined exports of power and ESS batteries were 44.0 GWh, up 3.7% MoM and up 64.5% YoY, accounting for 19.7% of that month's sales. Power battery exports were 28.4 GWh, accounting for 64.5% of total exports, up 14.9% MoM and up 60.9% YoY; ESS battery exports were 15.6 GWh, accounting for 35.5% of total exports, down 11.9% MoM but up 71.4% YoY.
From January to September, China's cumulative exports of power and ESS batteries were 302.9 GWh, up 51.6% YoY, accounting for 18.0% of cumulative sales. Cumulative power battery exports were 199.7 GWh, accounting for 65.9% of total exports, up 54.7% YoY; cumulative ESS battery exports were 103.2 GWh, accounting for 34.1% of total exports, up 45.9% YoY.
Installations side, in September, China's power battery installations were 87.2 GWh, up 10.4% MoM and up 14.7% YoY.
From January to September, China's cumulative power battery installations were 576.3 GWh, up 16.7% YoY.
Market concentration, in September, 31 power battery enterprises in China's NEV market achieved installation support, 4 fewer than the same period last year. The installations of the top 2, top 5, and top 10 power battery enterprises were 53.8 GWh, 69.7 GWh, and 82.1 GWh, respectively, accounting for 61.7%, 80.0%, and 94.2% of total installations. The top 10 share was down 0.2 percentage points YoY.
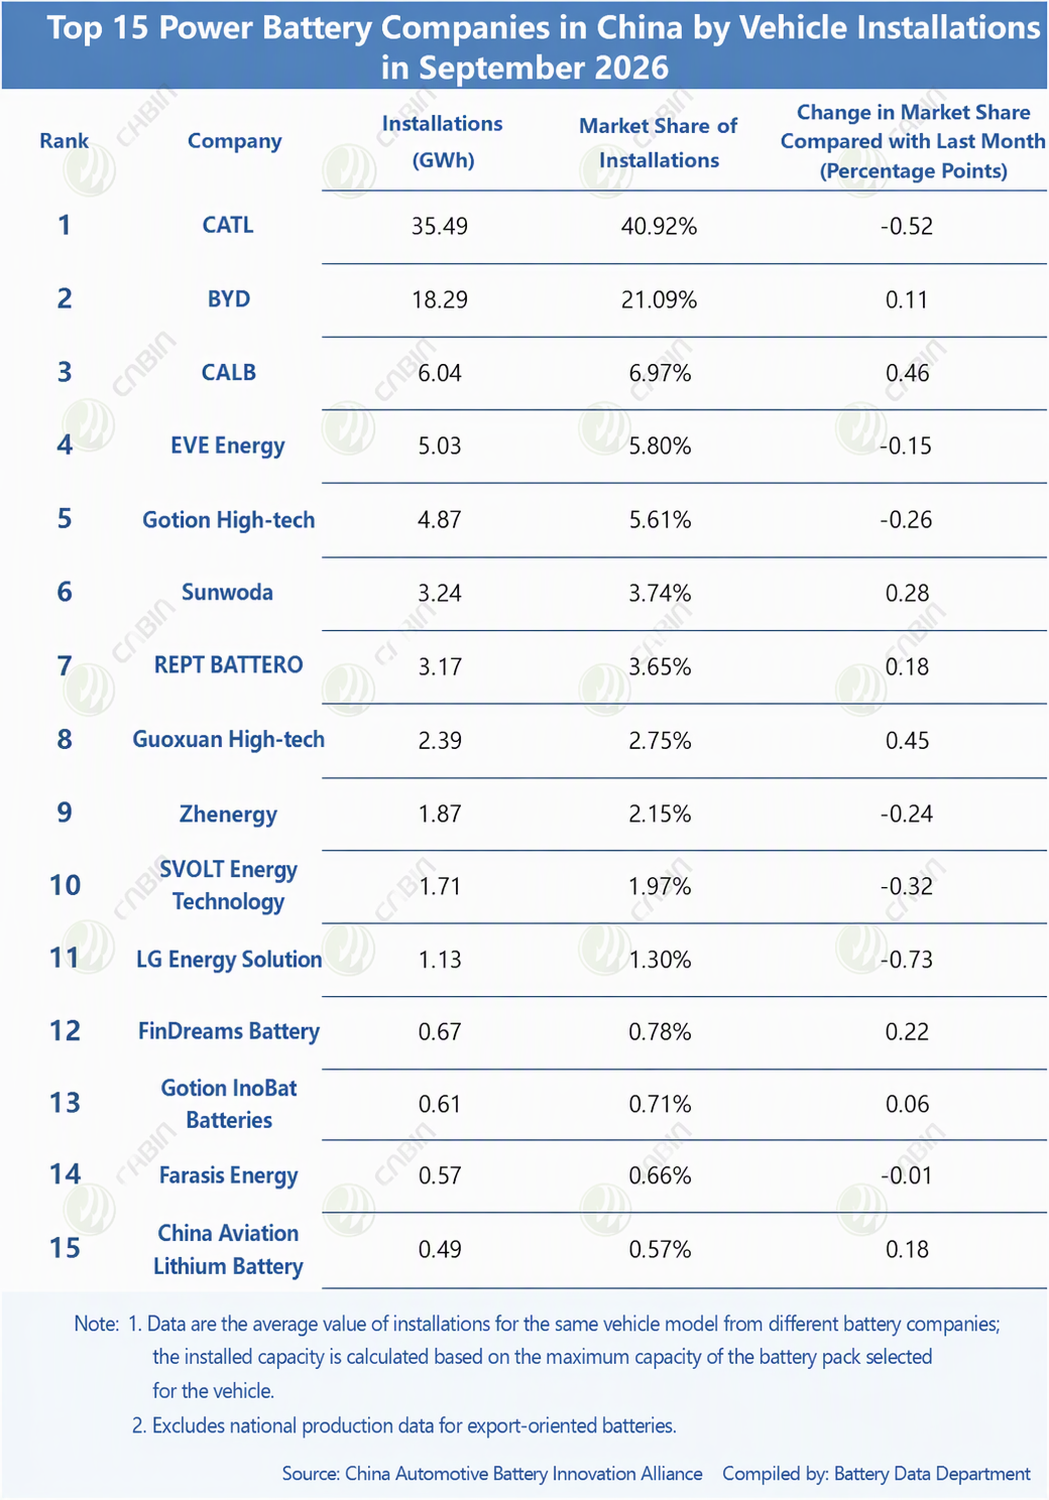
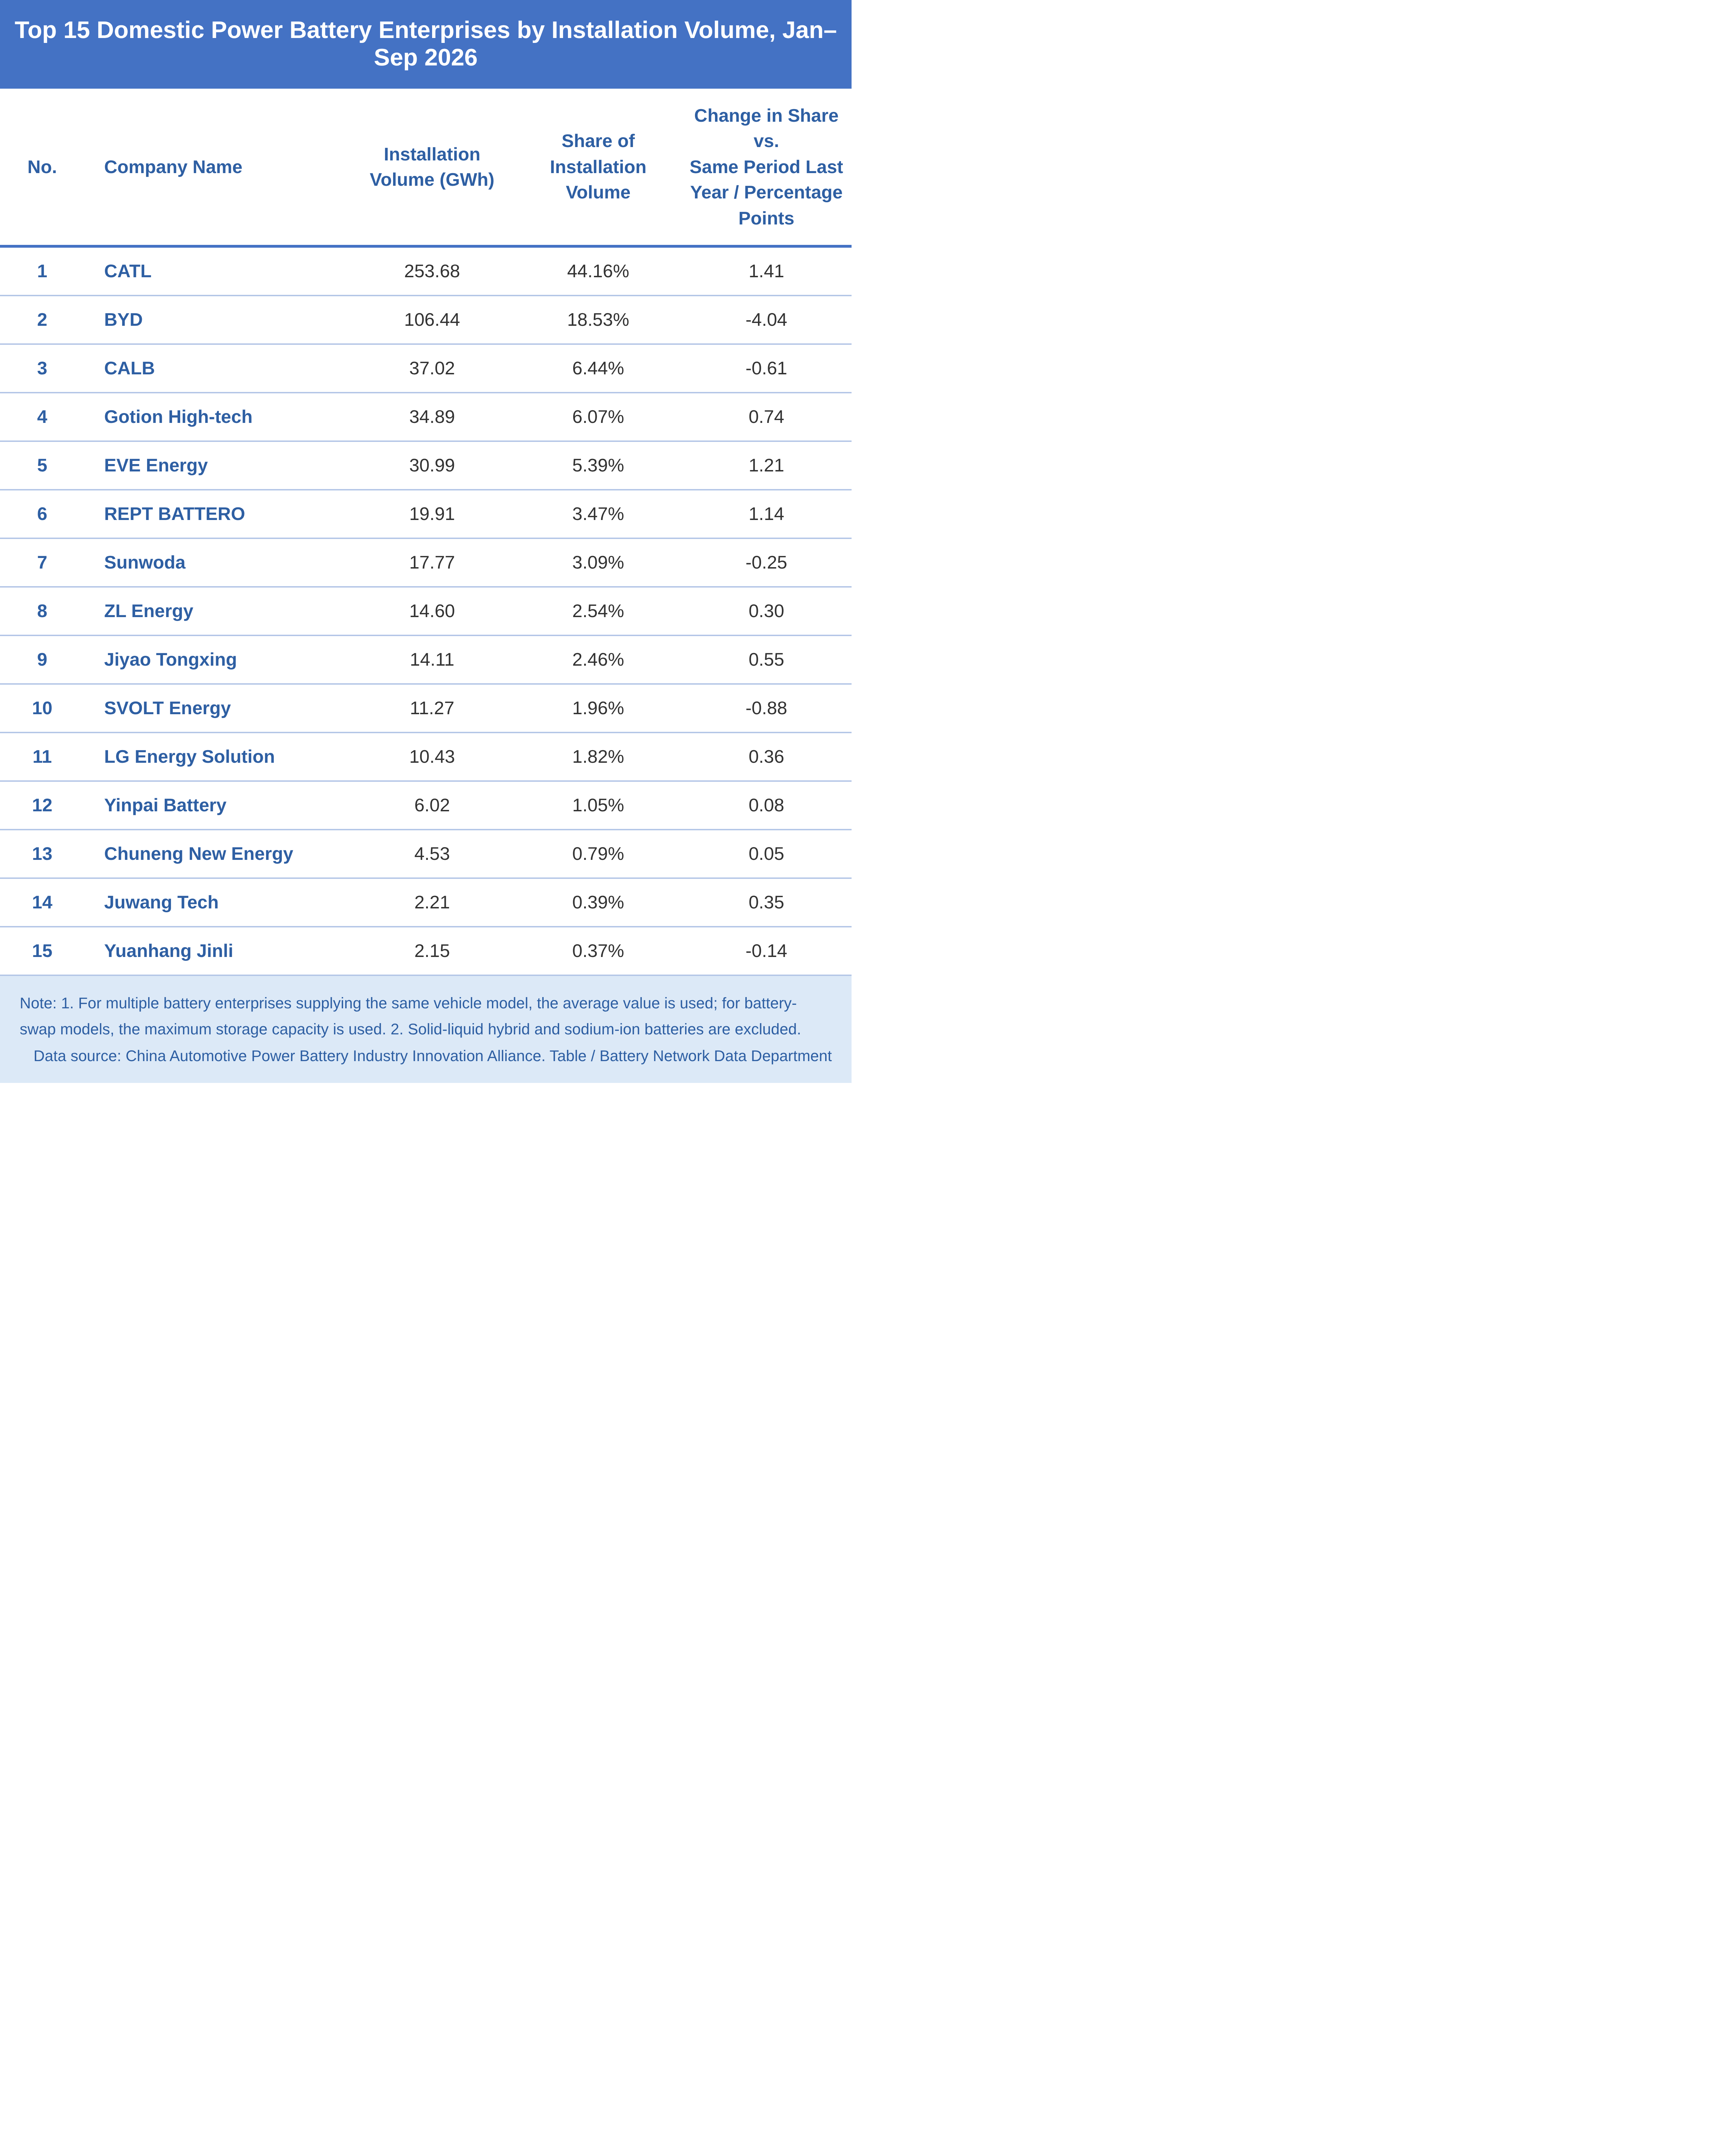
From January to September, 41 power battery enterprises in China's NEV market achieved installation support, 9 fewer than the same period last year. The installations of the top 2, top 5, and top 10 power battery enterprises were 360.1 GWh, 463.0 GWh, and 540.7 GWh, respectively, accounting for 62.5%, 80.3%, and 93.8% of total installations. The top 10 share was down 0.5 percentage points YoY.
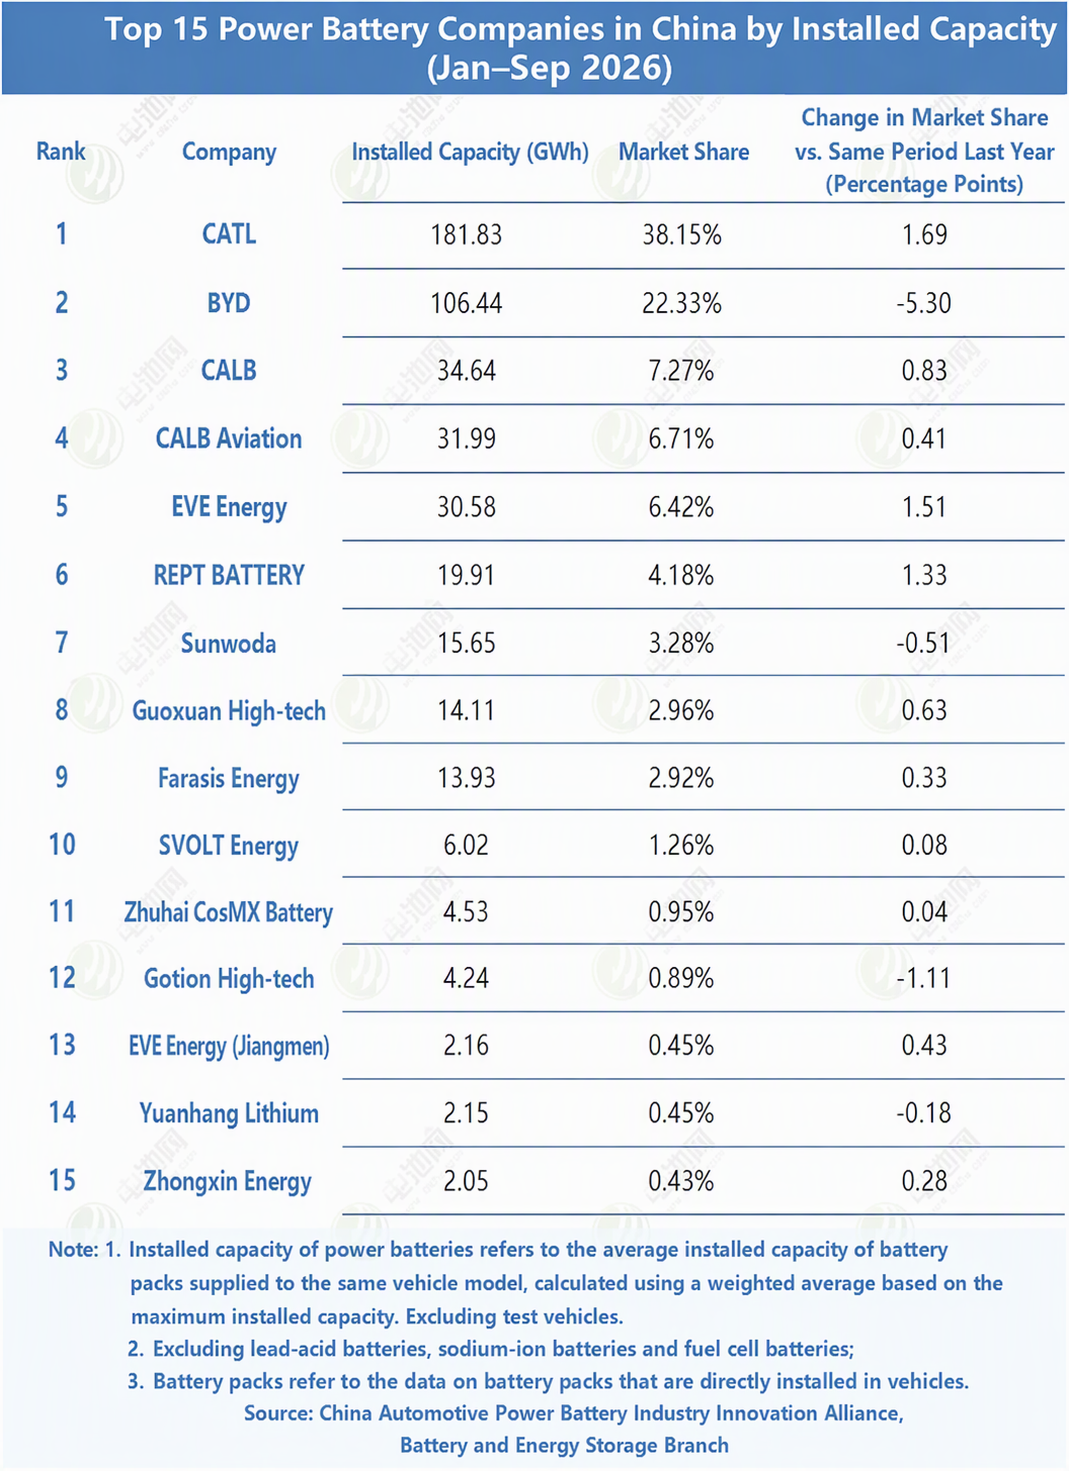
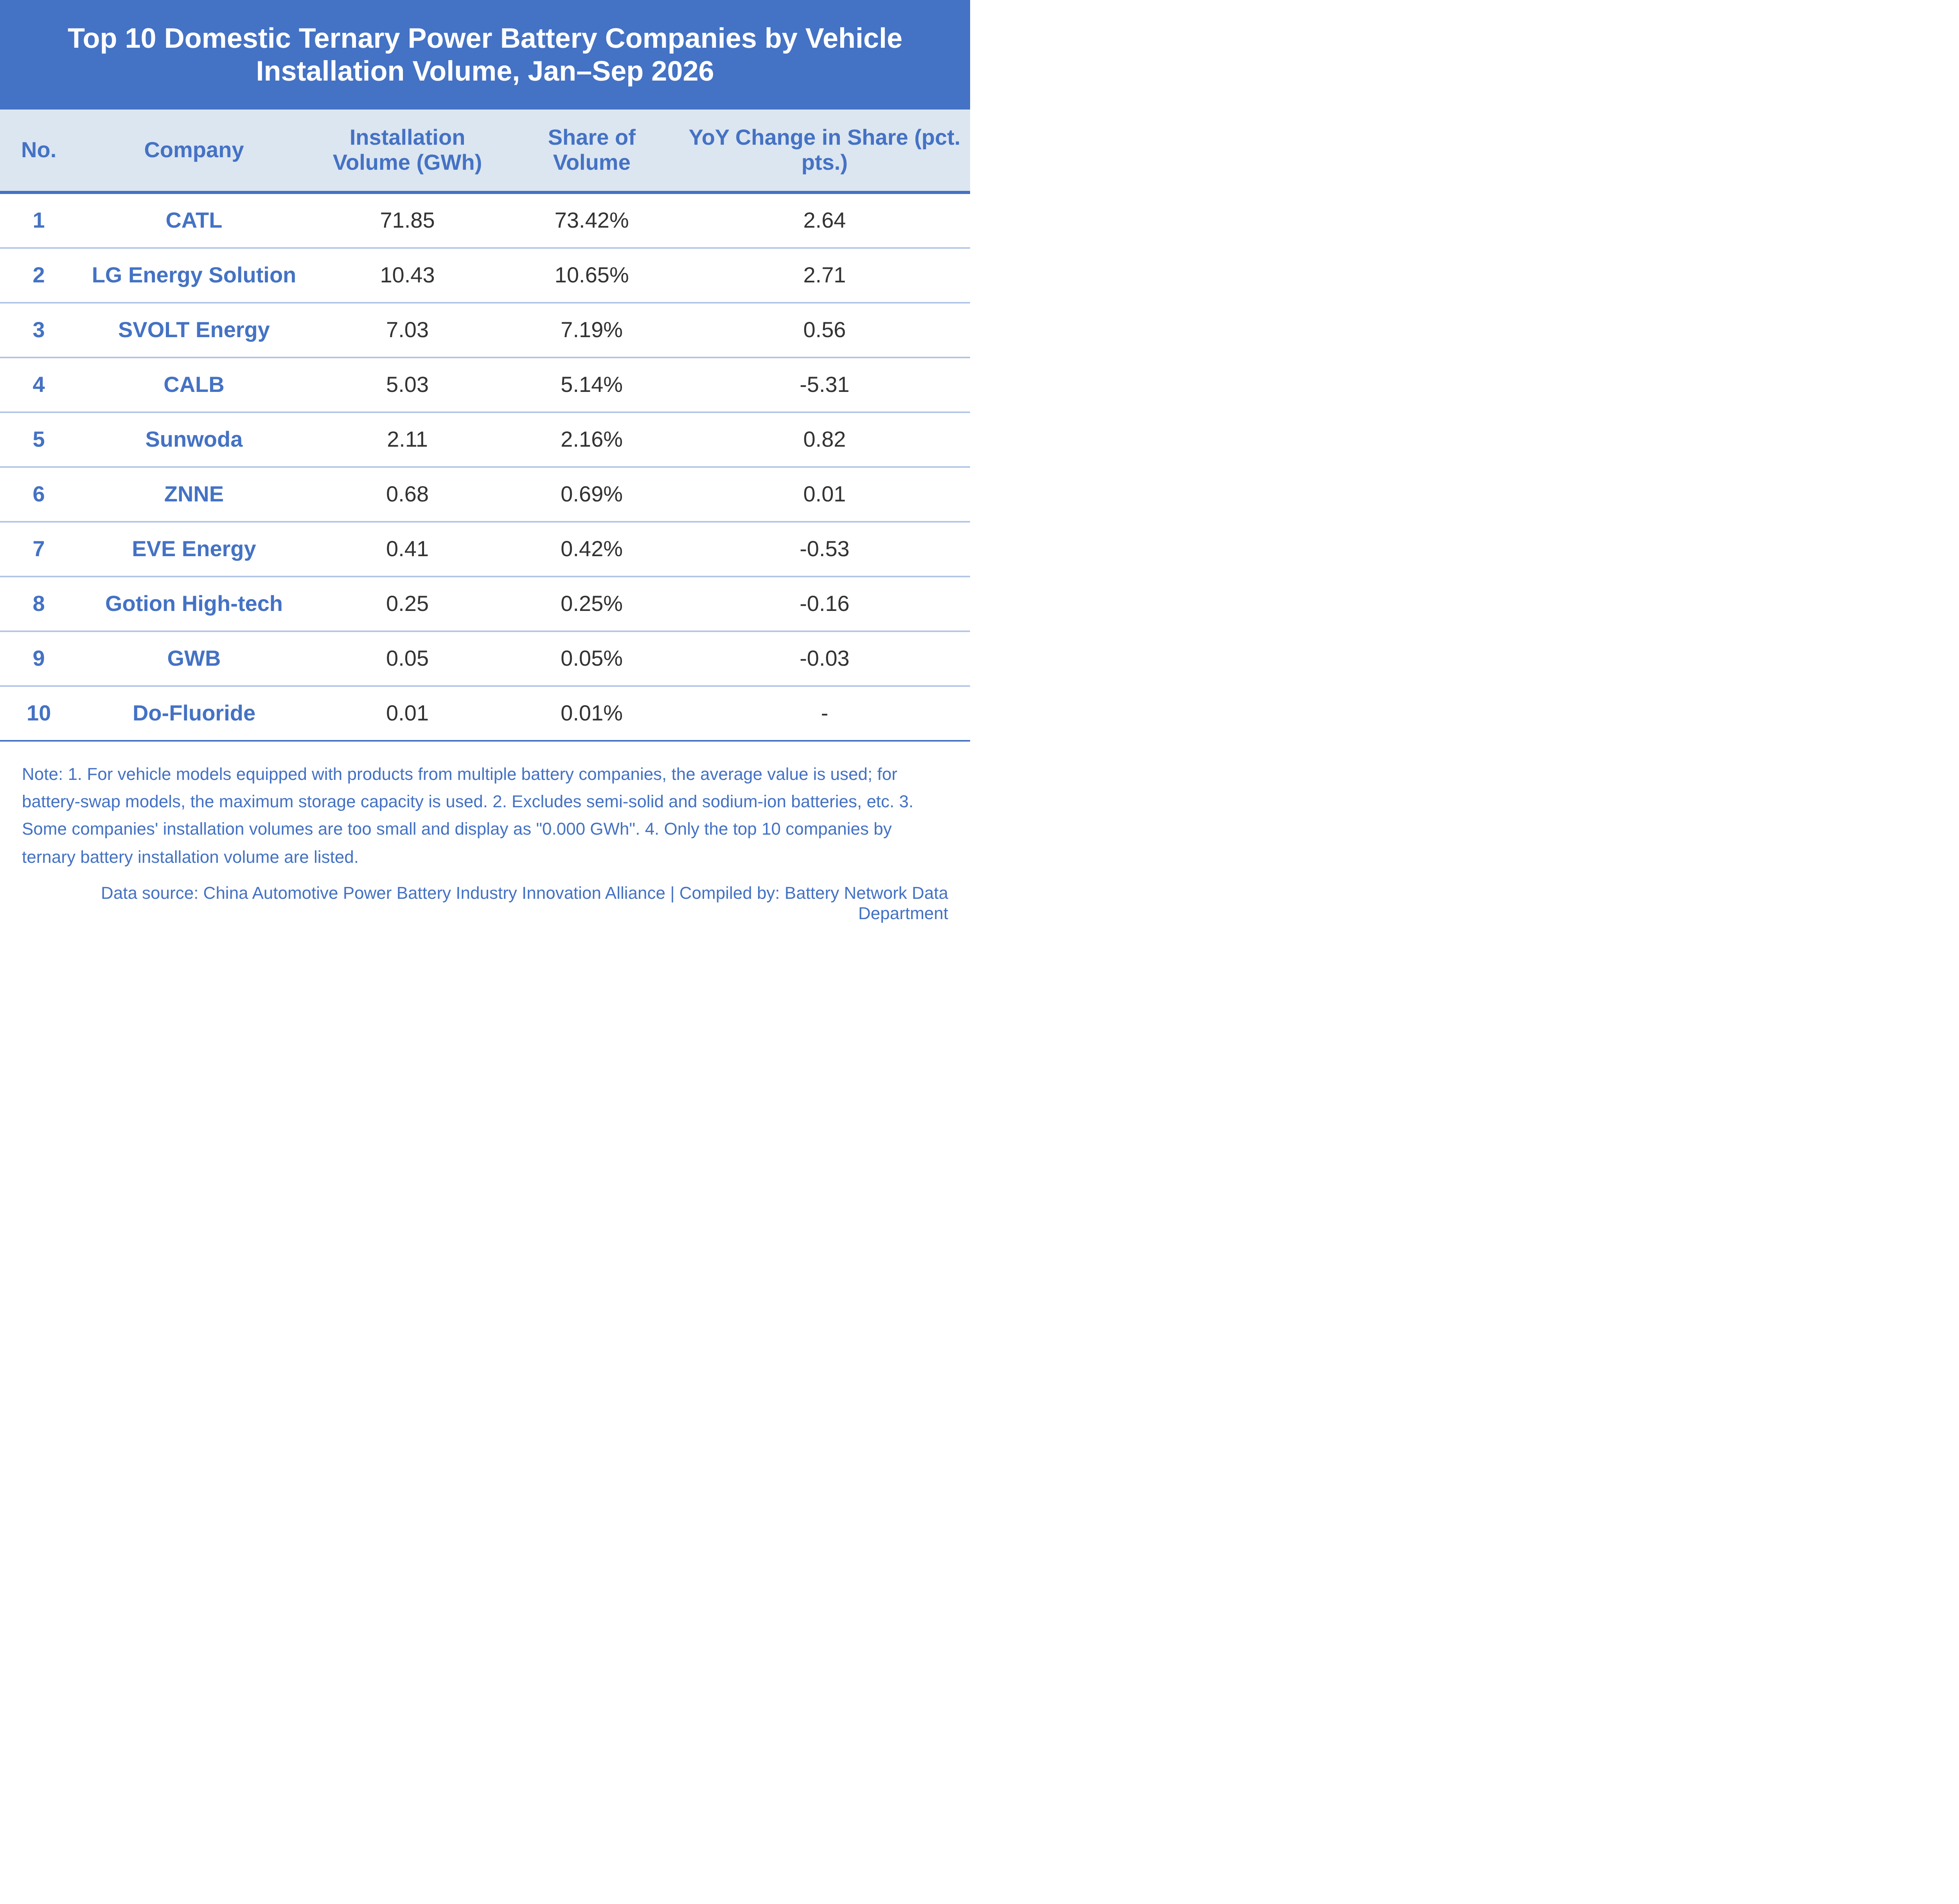
Market share, among the top 15 domestic power battery enterprises, compared with August, in September only BYD, CALB, Sunwoda, REPT Battero, Jiyao Tongxing, Yinpai Battery, CORNEX New Energy, and Zhongqi New Energy achieved positive growth. CALB posted the fastest growth, up 0.45 percentage points. The remaining 7 enterprises saw declines of varying degrees.
Compared with the same period in 2025, from January to September this year, CATL, Gotion High-tech, EVE, REPT Battero, Zenergy, Jiyao Tongxing, LG Energy Solution, Yinpai Battery, CORNEX New Energy, and Juwan Technology achieved improvements of varying degrees. CATL posted the largest increase, up 1.41 percentage points.
Ranking changes, compared with August, in September the top 5 companies CATL, BYD, CALB, EVE, and Gotion High-tech kept their rankings unchanged; Sunwoda and REPT Battero swapped positions, ranking 6th and 7th respectively; Jiyao Tongxing and Zenergy swapped positions, ranking 8th and 9th respectively; SVOLT and LG Energy Solution kept their rankings unchanged, ranking 10th to 11th; Yinpai Battery rose two spots to 12th; Deyi Energy fell two spots to 14th; CORNEX New Energy and Zhongqi New Energy kept their rankings unchanged, ranking 13th and 15th respectively.
Compared with the same period in 2025, from January to September this year, the top 5 companies CATL, BYD, CALB, Gotion High-tech, and EVE kept their rankings unchanged; REPT Battero rose from 8th to 6th; Sunwoda fell one spot to 7th; Zenergy rose one spot to 8th; Jiyao Tongxing rose one spot to 9th; SVOLT fell from 7th to 10th; LG Energy Solution, Yinpai Battery, and CORNEX New Energy ranked 11th to 13th, unchanged; Yuanhang Genlead kept its 15th place unchanged; Juwan Technology replaced DFD as a new entrant, ranking 14th.
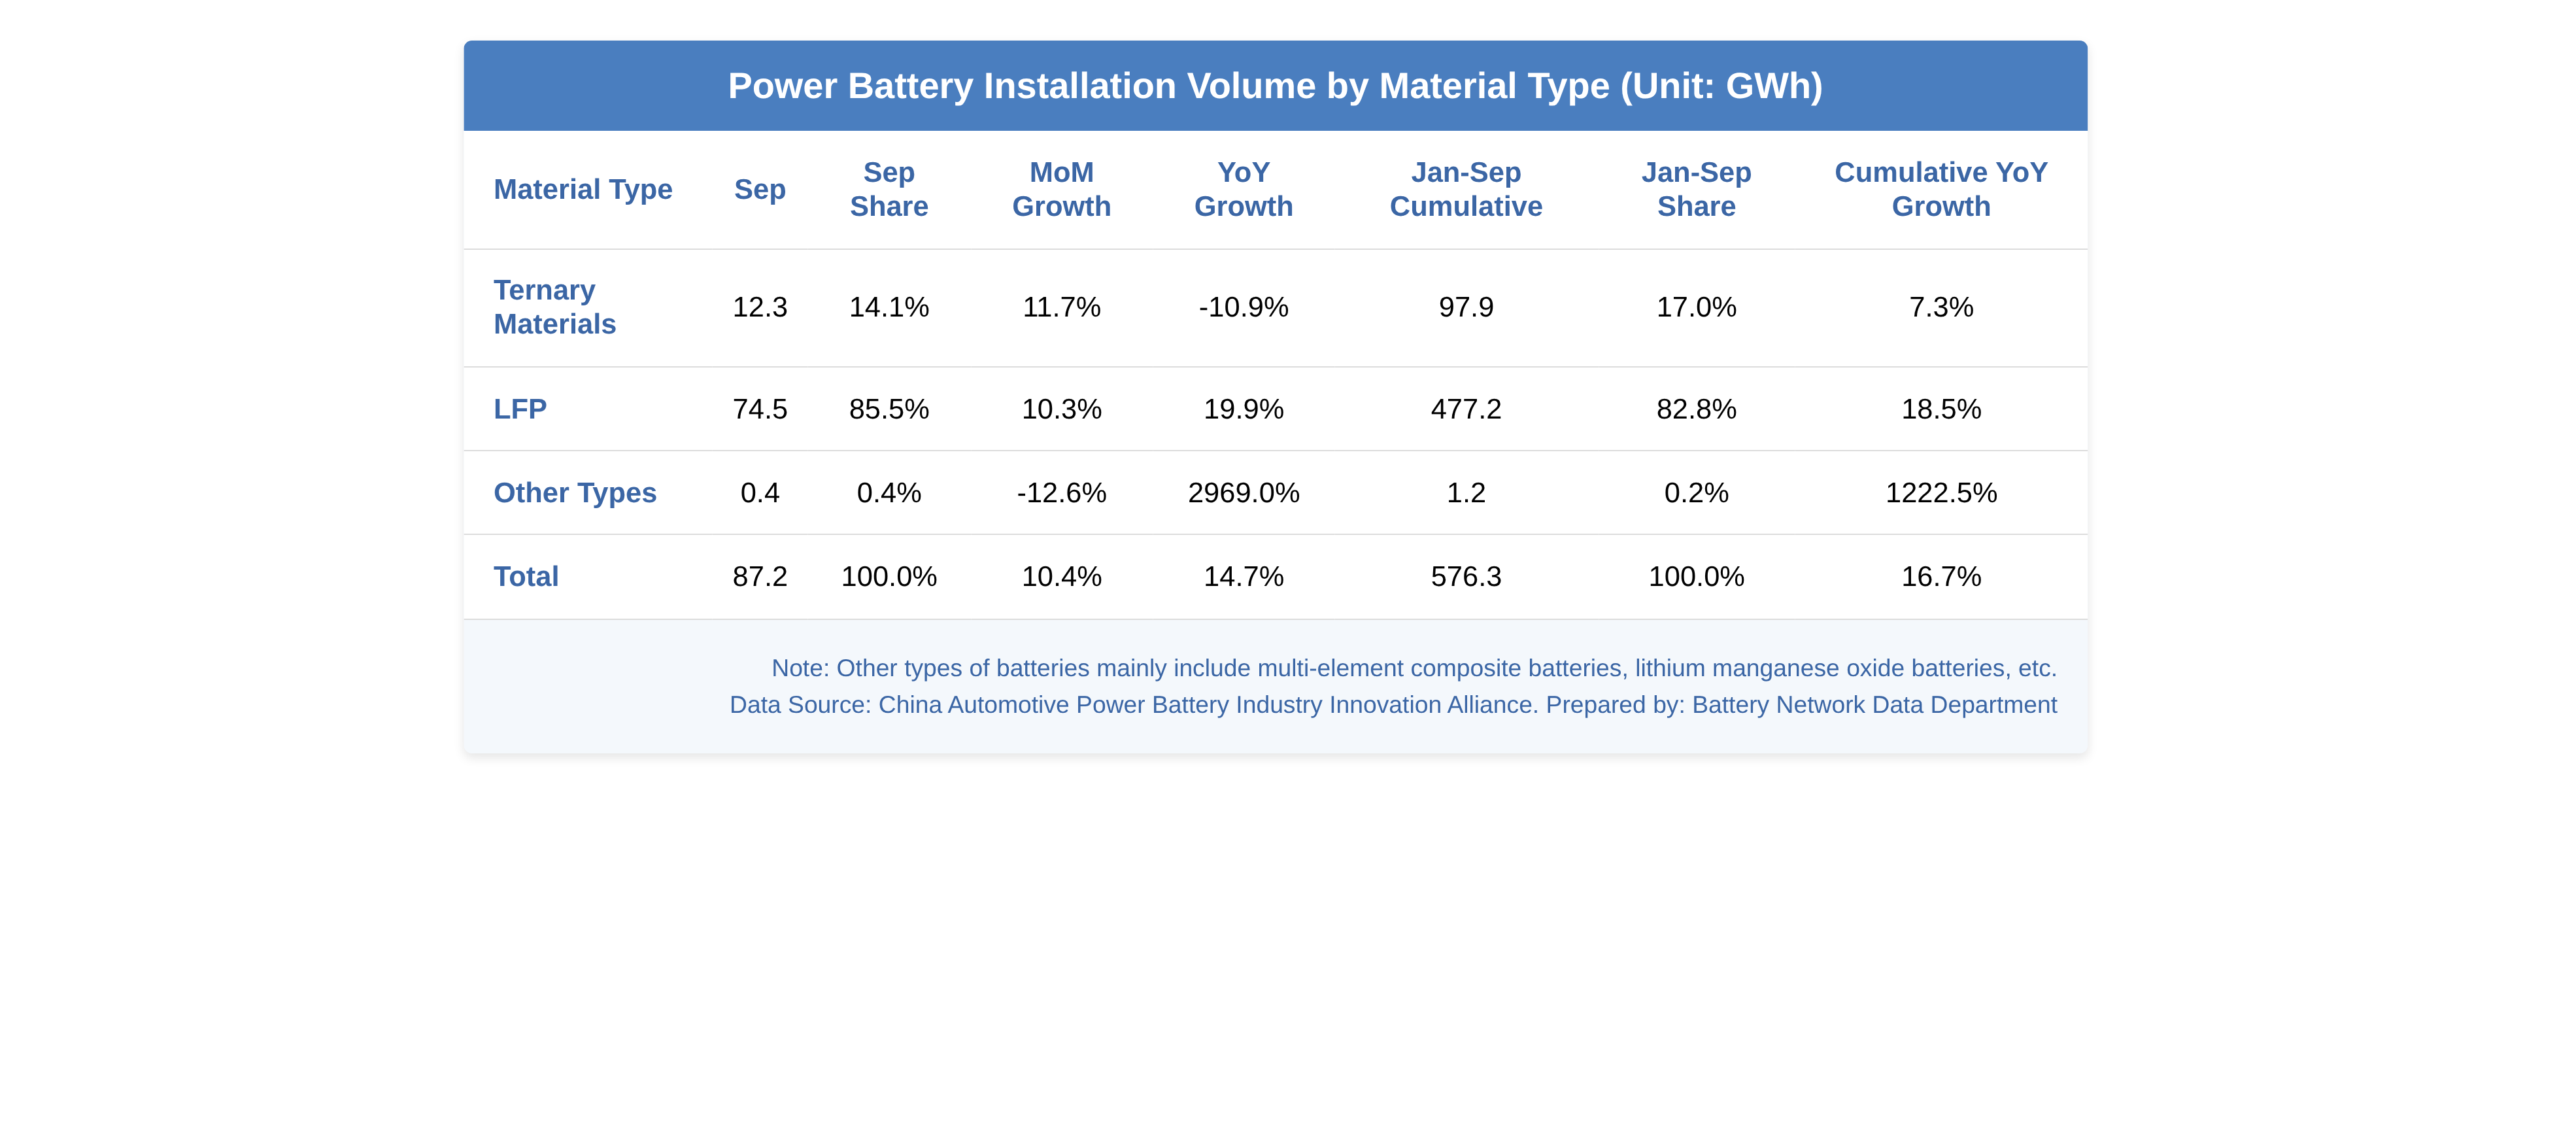
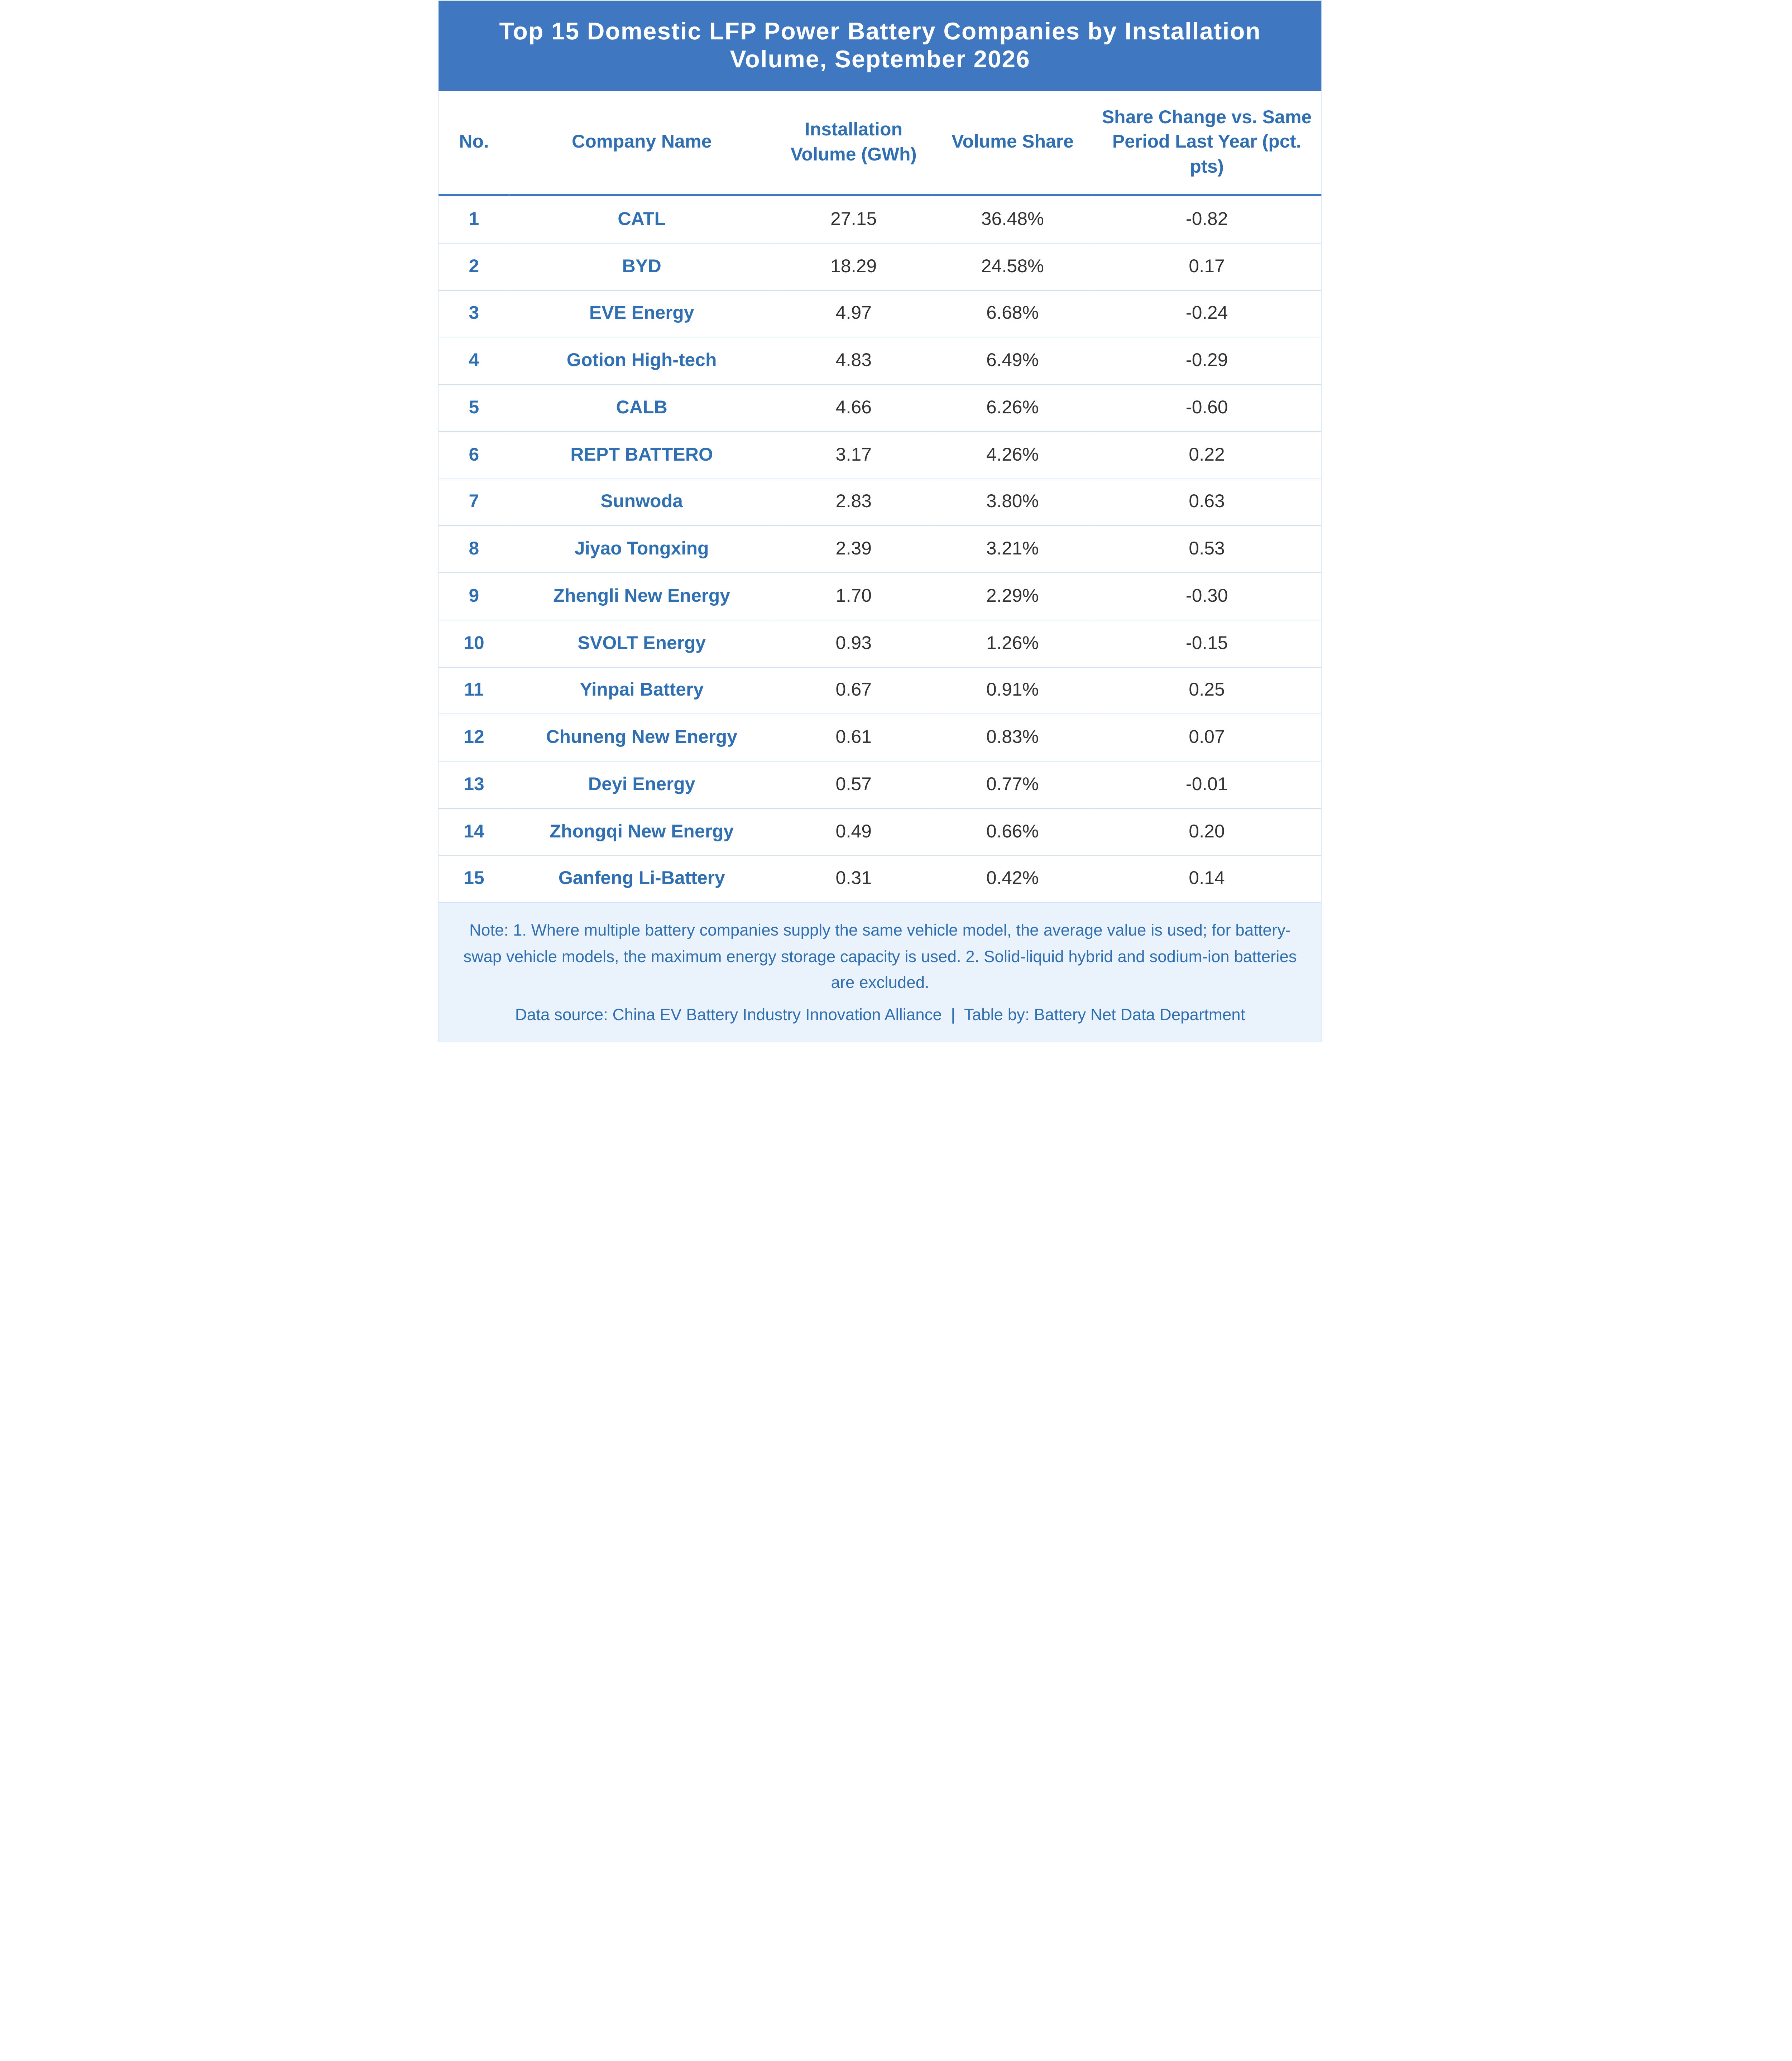
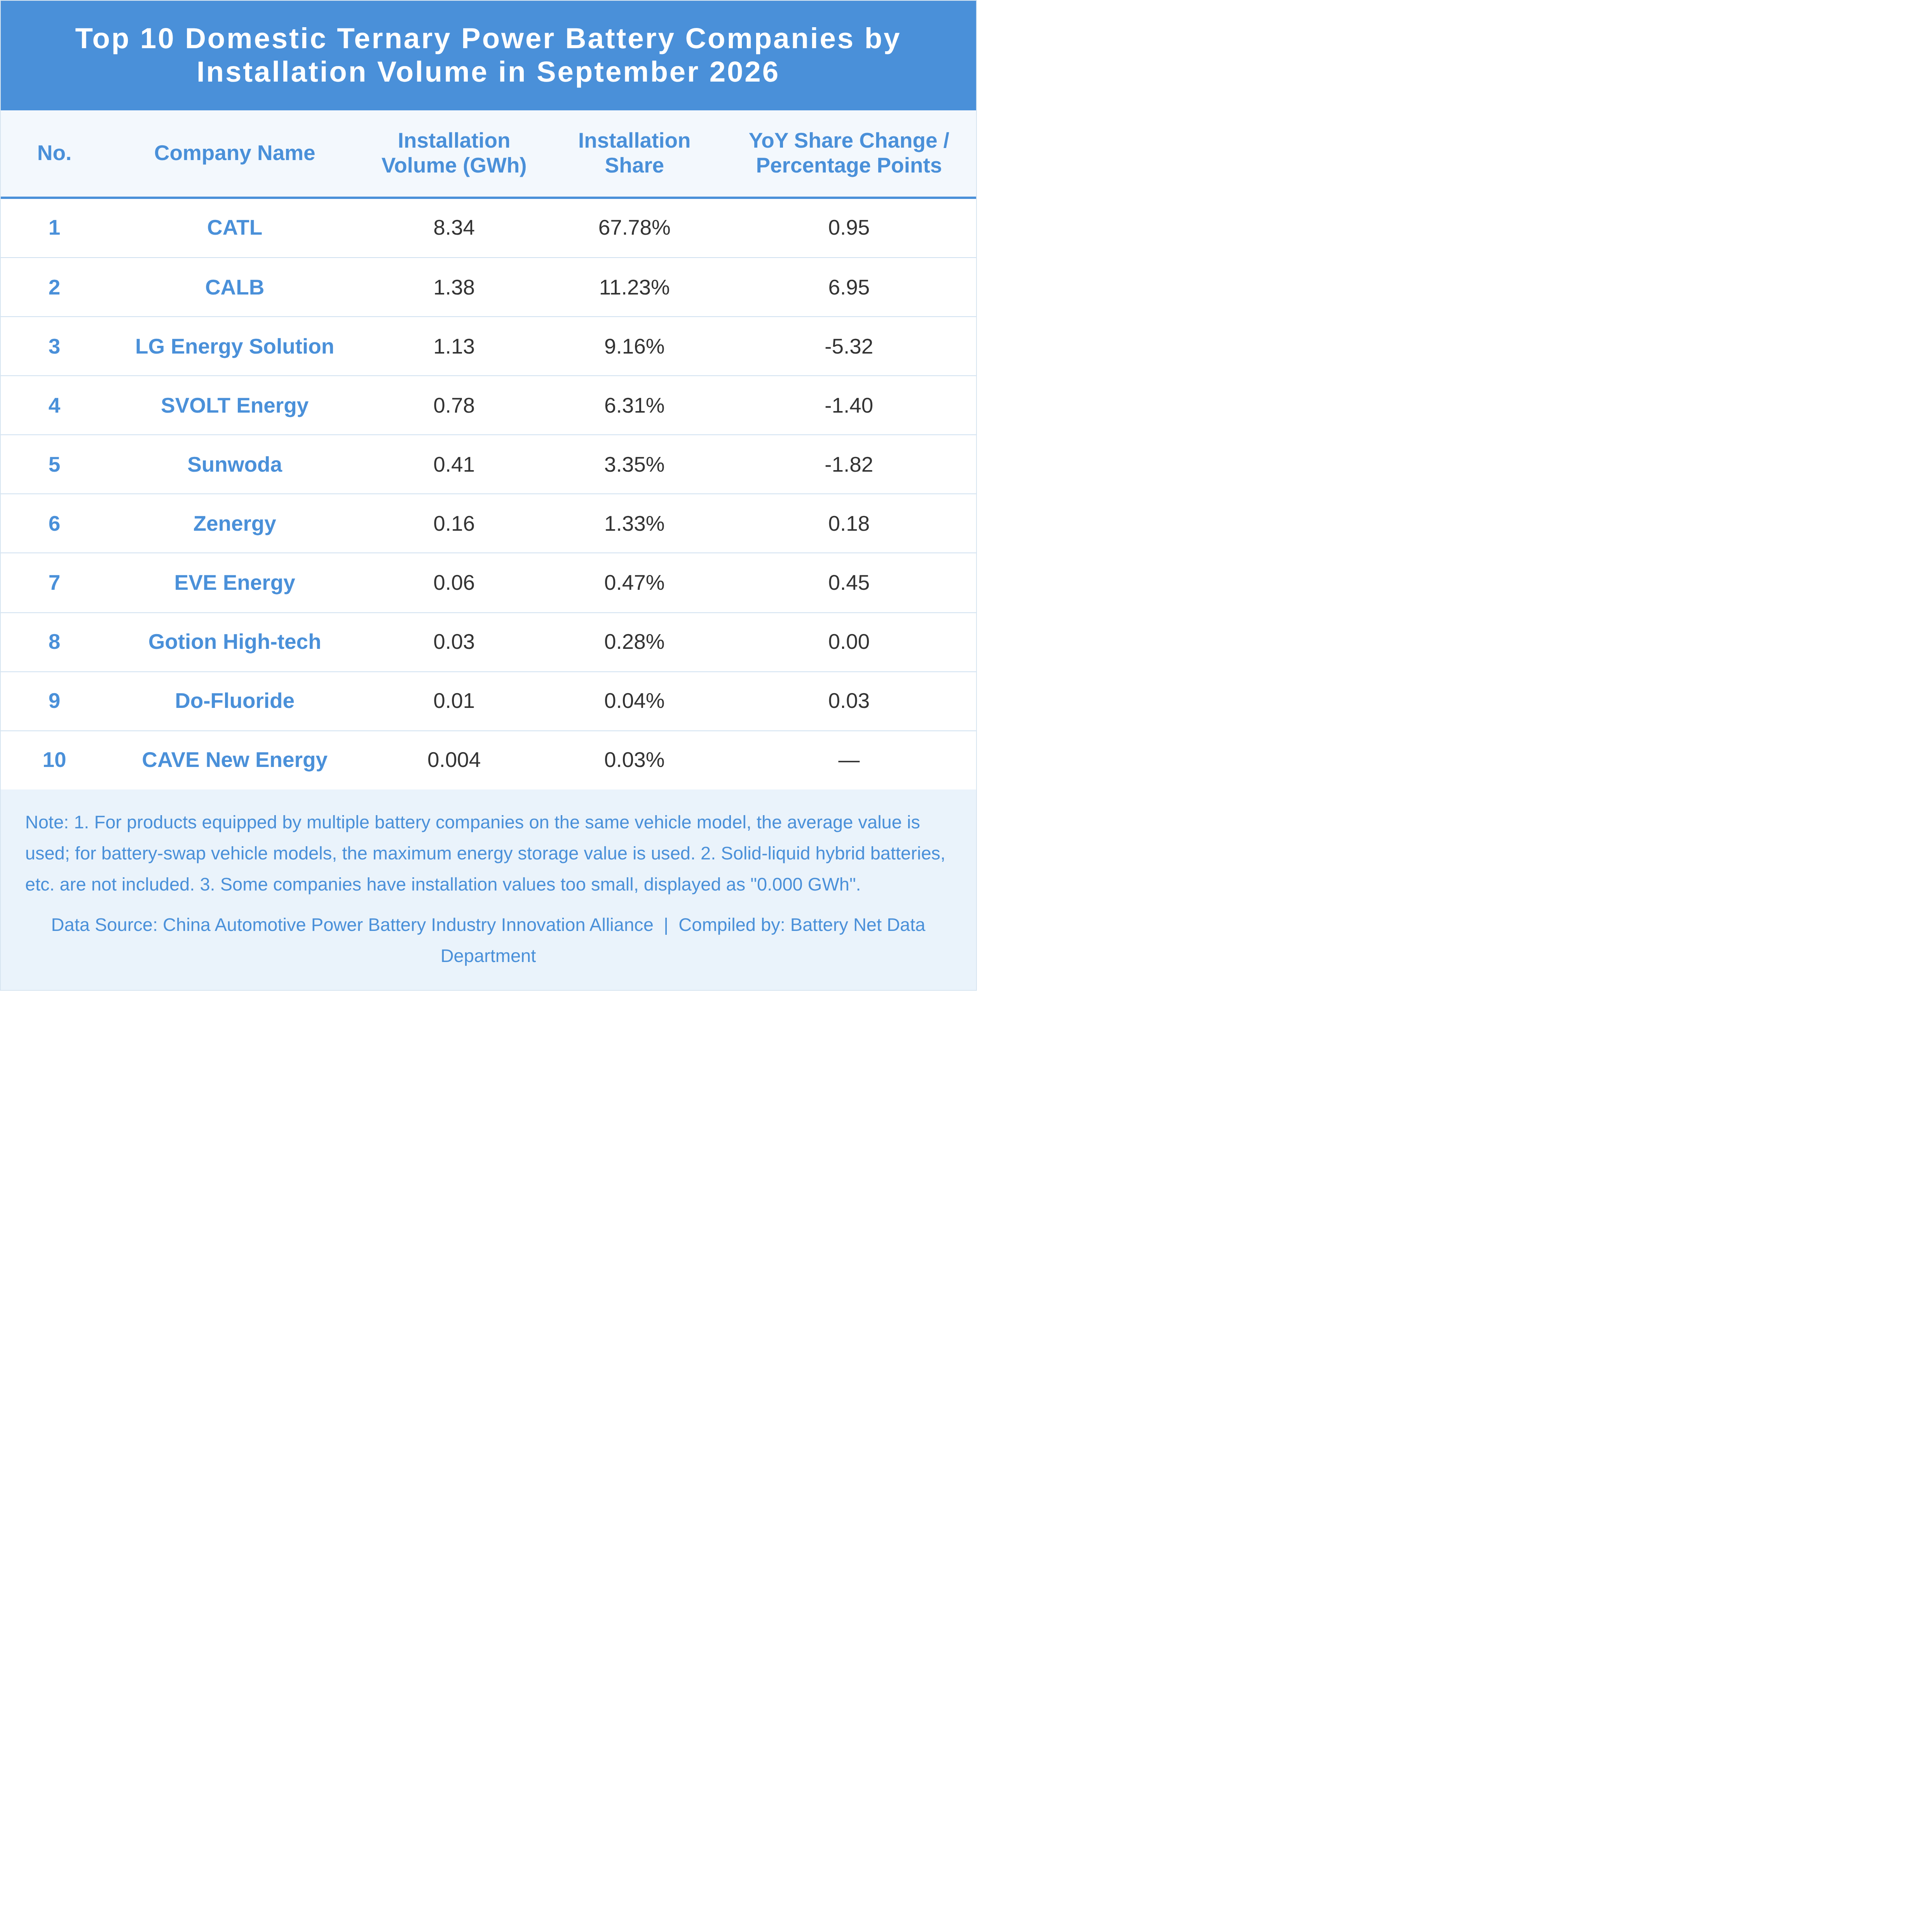
By material, in September, China's ternary battery installations were 12.3 GWh, accounting for 14.1% of total installations, up 11.7% MoM but down 10.9% YoY; LFP battery installations were 74.5 GWh, accounting for 85.5% of total installations, up 10.3% MoM and up 19.9% YoY.
From January to September, China's cumulative ternary battery installations were 97.9 GWh, accounting for 17.0% of total installations, up 7.3% YoY; cumulative LFP battery installations were 477.2 GWh, accounting for 82.8% of total installations, up 18.5% YoY.
By vehicle type, in September, pure electric vehicles accounted for 83.6% of installations, up 17.2% YoY; plug-in hybrid electric vehicles accounted for 16.3%, up 3.4% YoY; fuel cell vehicles accounted for 0.01%, down 68.4% YoY. Among them, trucks and special-purpose vehicles saw faster installation growth.
From January to September, pure electric vehicles accounted for 83.5% of installations, up 19.2% YoY; plug-in hybrid electric vehicles accounted for 16.4%, up 5.5% YoY; fuel cell vehicles accounted for 0.02%, down 35.3% YoY. Among them, trucks and special-purpose vehicles saw faster installation growth.
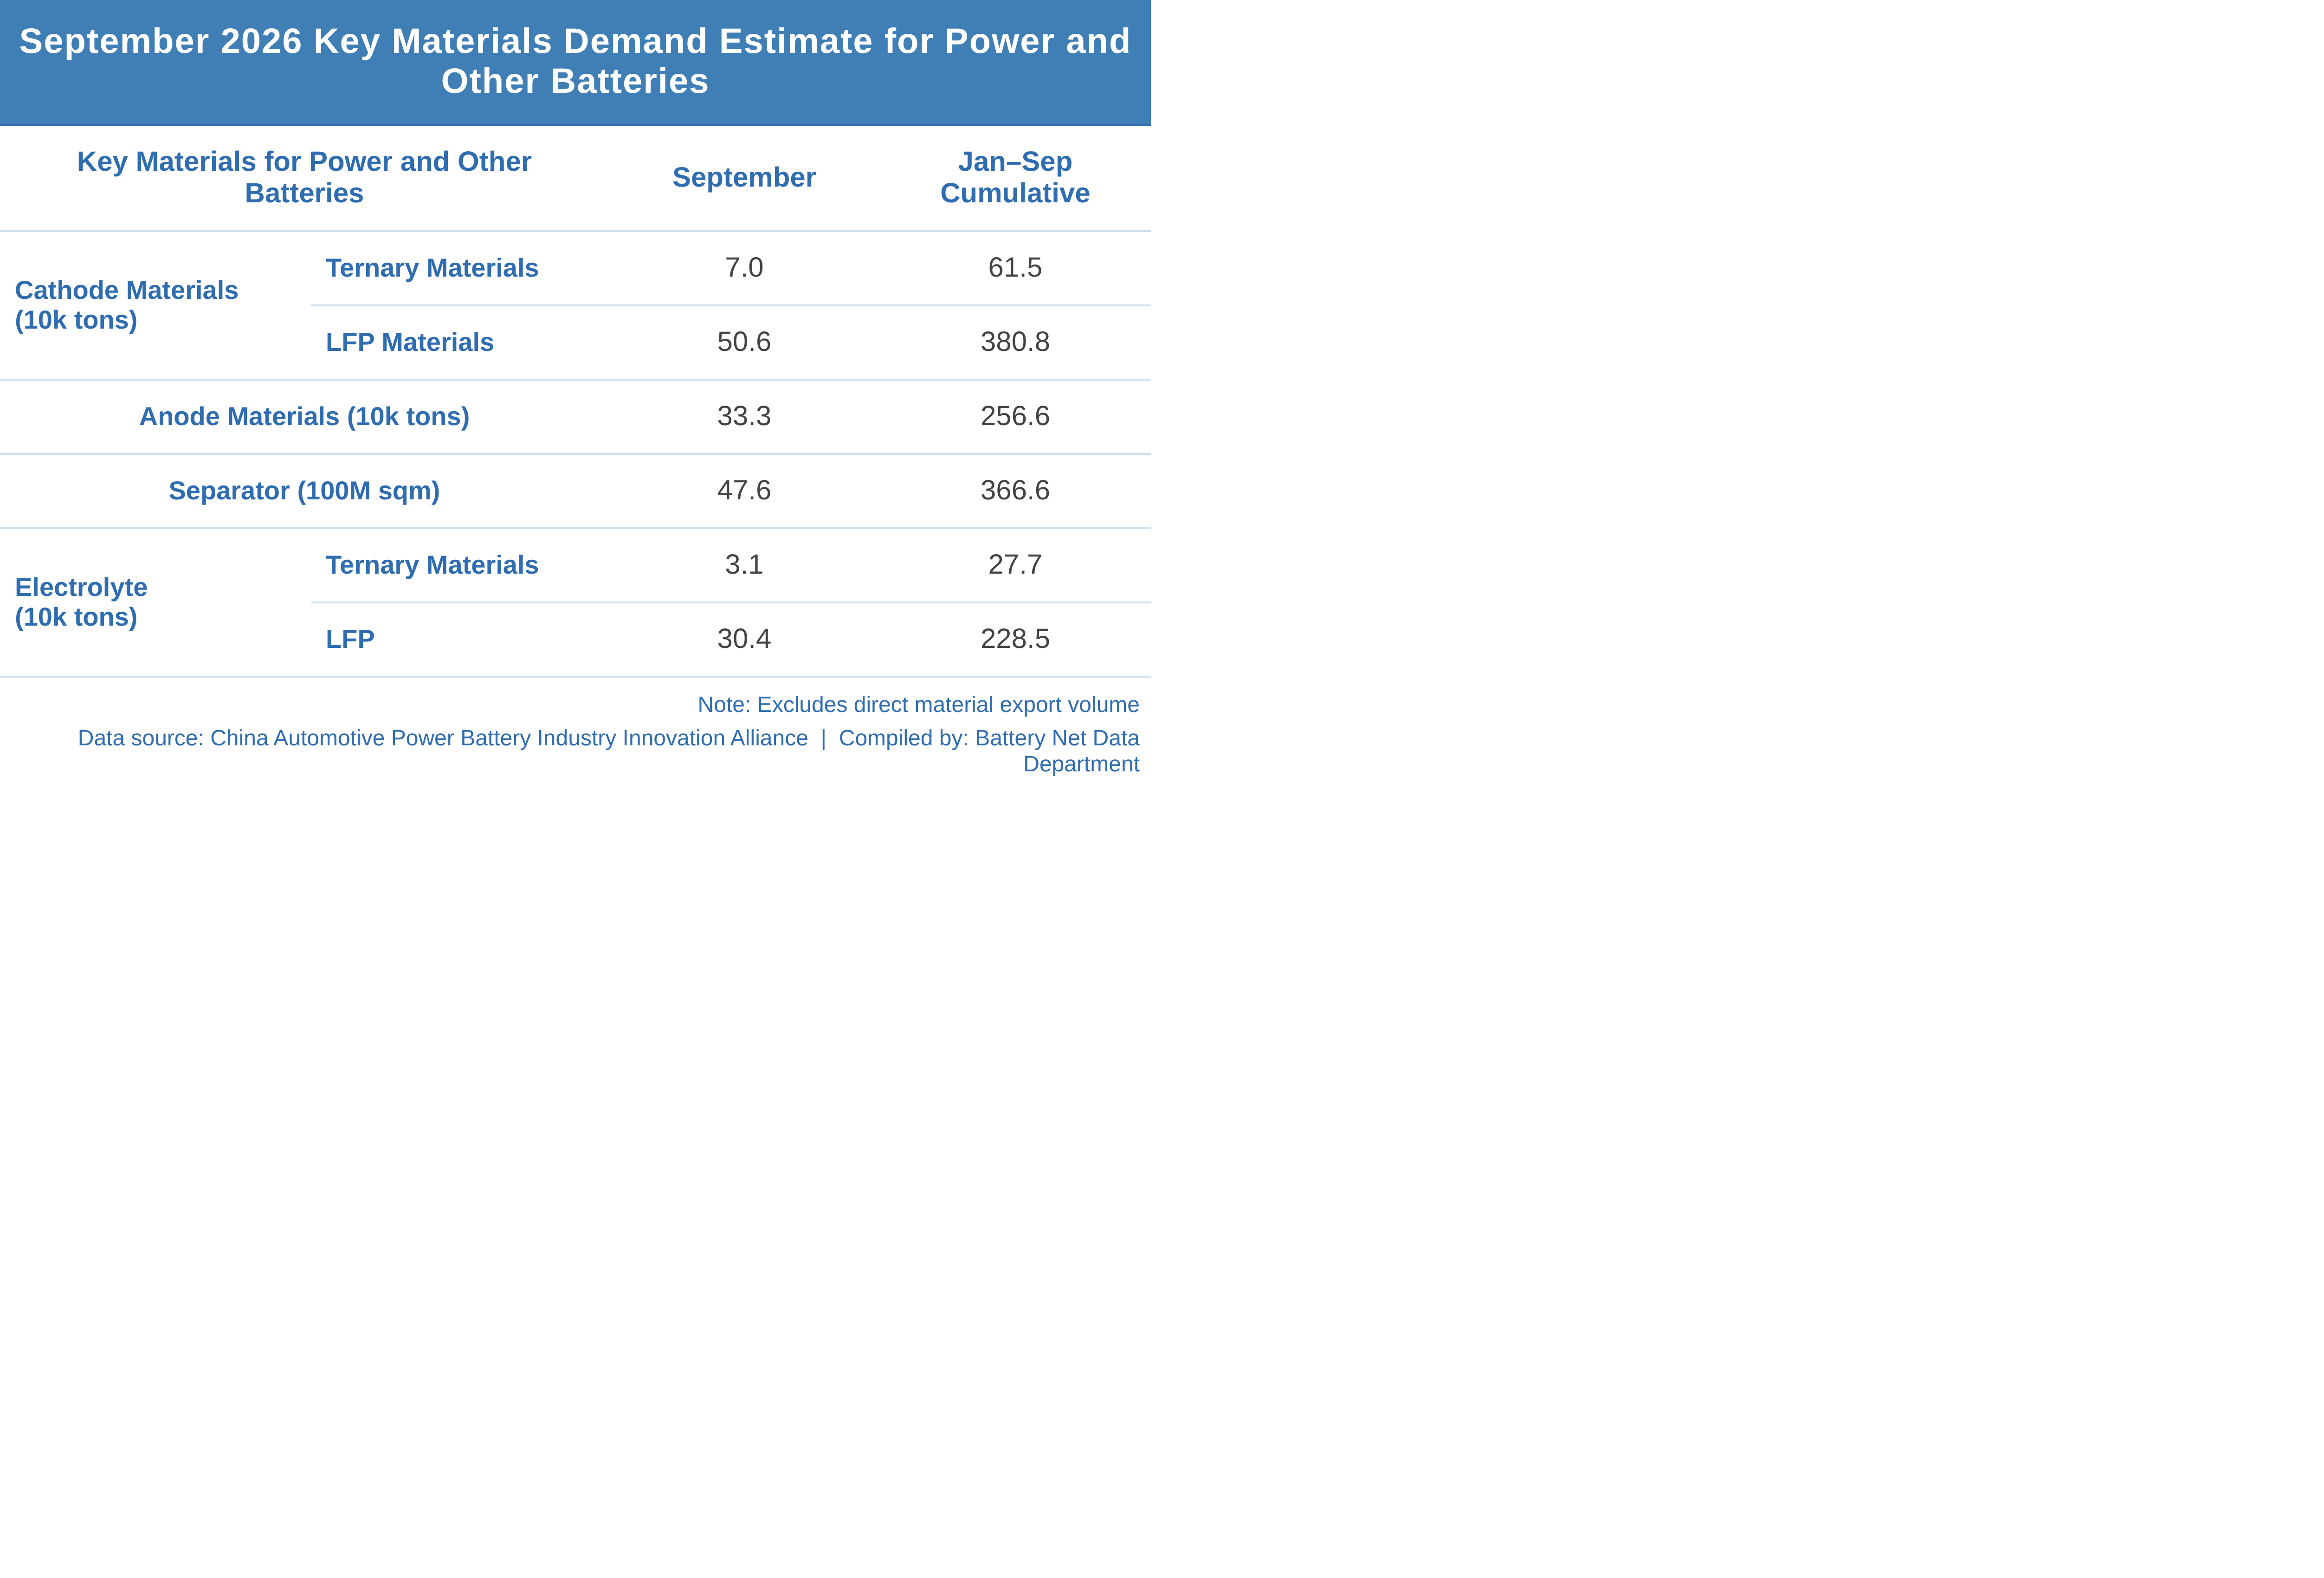
Estimated demand for key materials for power and other batteries, in September, China's power and ESS batteries consumed 70,000 mt of ternary materials and 506,000 mt of LFP materials; 333,000 mt of anode materials; 4.76 billion m² of separators; 31,000 mt of electrolyte for ternary batteries and 304,000 mt of electrolyte for LFP batteries.
From January to September, China's power and ESS batteries consumed 615,000 mt of ternary materials and 3.808 million mt of LFP materials; 2.566 million mt of anode materials; 36.66 billion m² of separators; 277,000 mt of electrolyte for ternary batteries and 2.285 million mt of electrolyte for LFP batteries.