The average price of SMM 10-12% high-grade NPI fell WoW by 7.9 yuan/nickel unit to 1,029.4 yuan/nickel unit (ex-factory, tax included), while the average Indonesia NPI FOB index price fell WoW by $0.7/nickel unit to $133.2/nickel unit. This week, the high-grade NPI market continued to drift lower, with the price center moving further down and bearish sentiment intensifying.
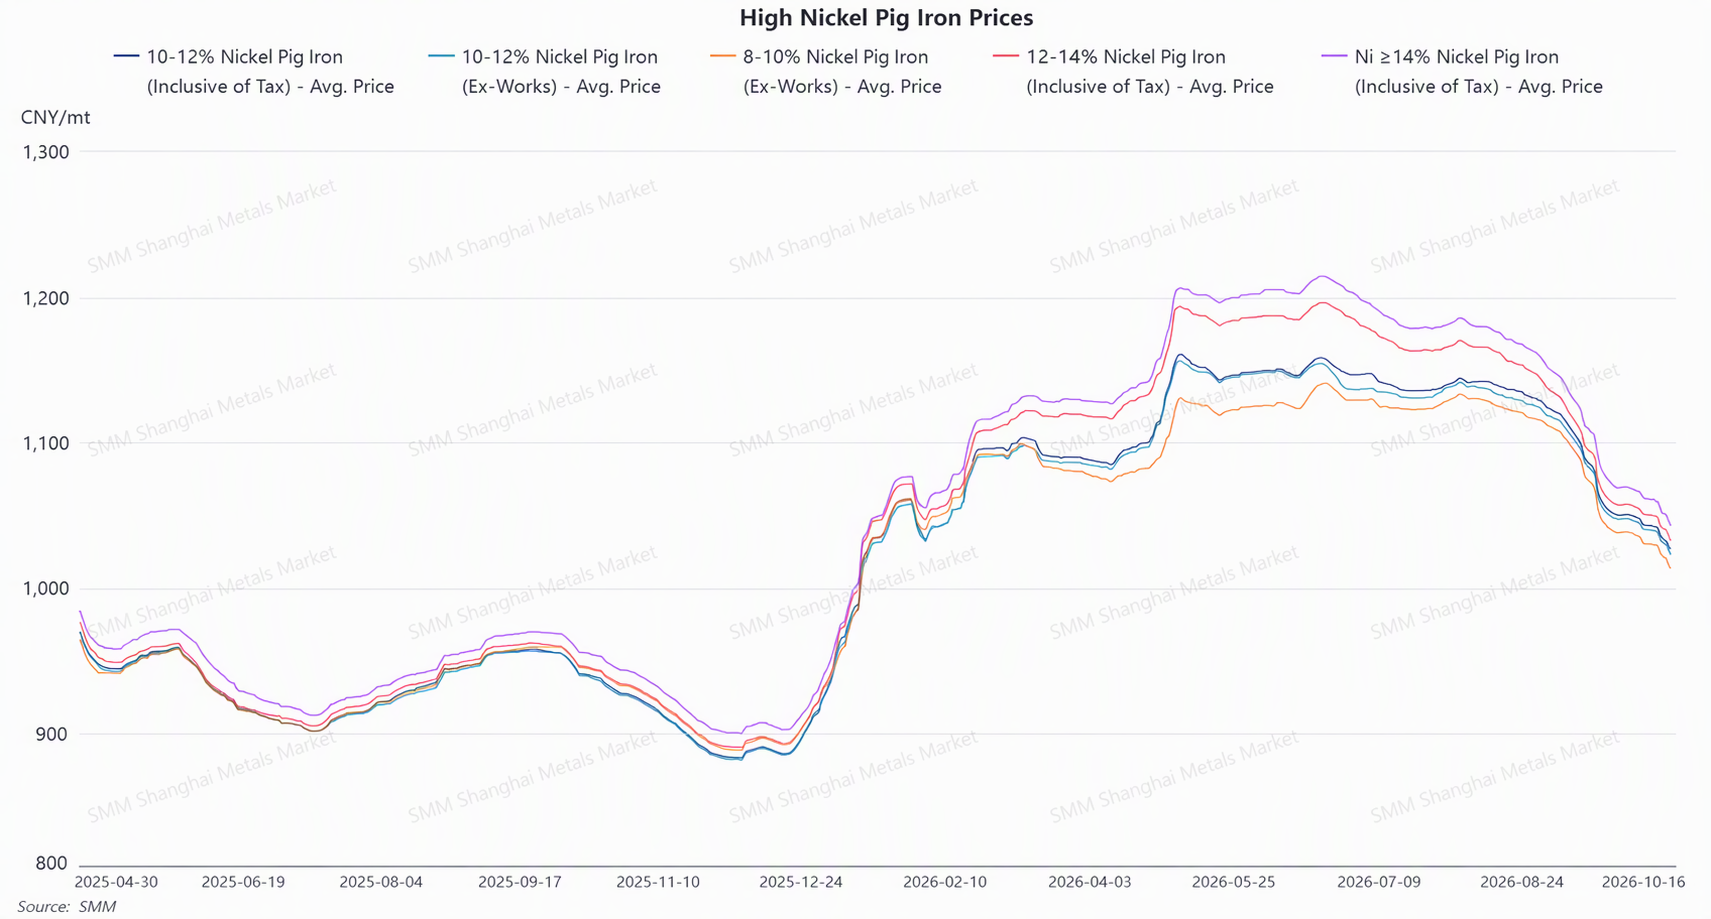
Supply side, overall market supply remained ample. Some traders opted to hold back from quoting and wait on the sidelines, leading to divergent quotation practices, with more transactions shifting to negotiations on par with average prices. Demand side, expectations for the September-October peak season were disproved, and downstream stainless steel product prices continued to weaken. Some steel mills adjusted their production structures and scheduled maintenance and production cuts, dampening nickel-iron consumption expectations. Meanwhile, steel scrap prices were lowered again, and refined nickel prices fell for consecutive sessions, further enhancing the substitution advantage of alternative raw materials. Steel mills proactively reduced nickel-iron purchases, with procurement expectations continuously revised downward, and mills that had previously intended to buy also held off entering the market. Negotiation centers in the market kept moving lower, with a notable spread between high and low prices. High-priced cargoes struggled to find deals, while only low-priced cargoes had room for discussion. Overall trading was sluggish, and substantial bulk transactions were limited. Sentiment-wise, expectations for the price floor continued to probe lower, with most participants believing there is still downside for prices. The market is still waiting for actual steel mill purchases to confirm bottom support.
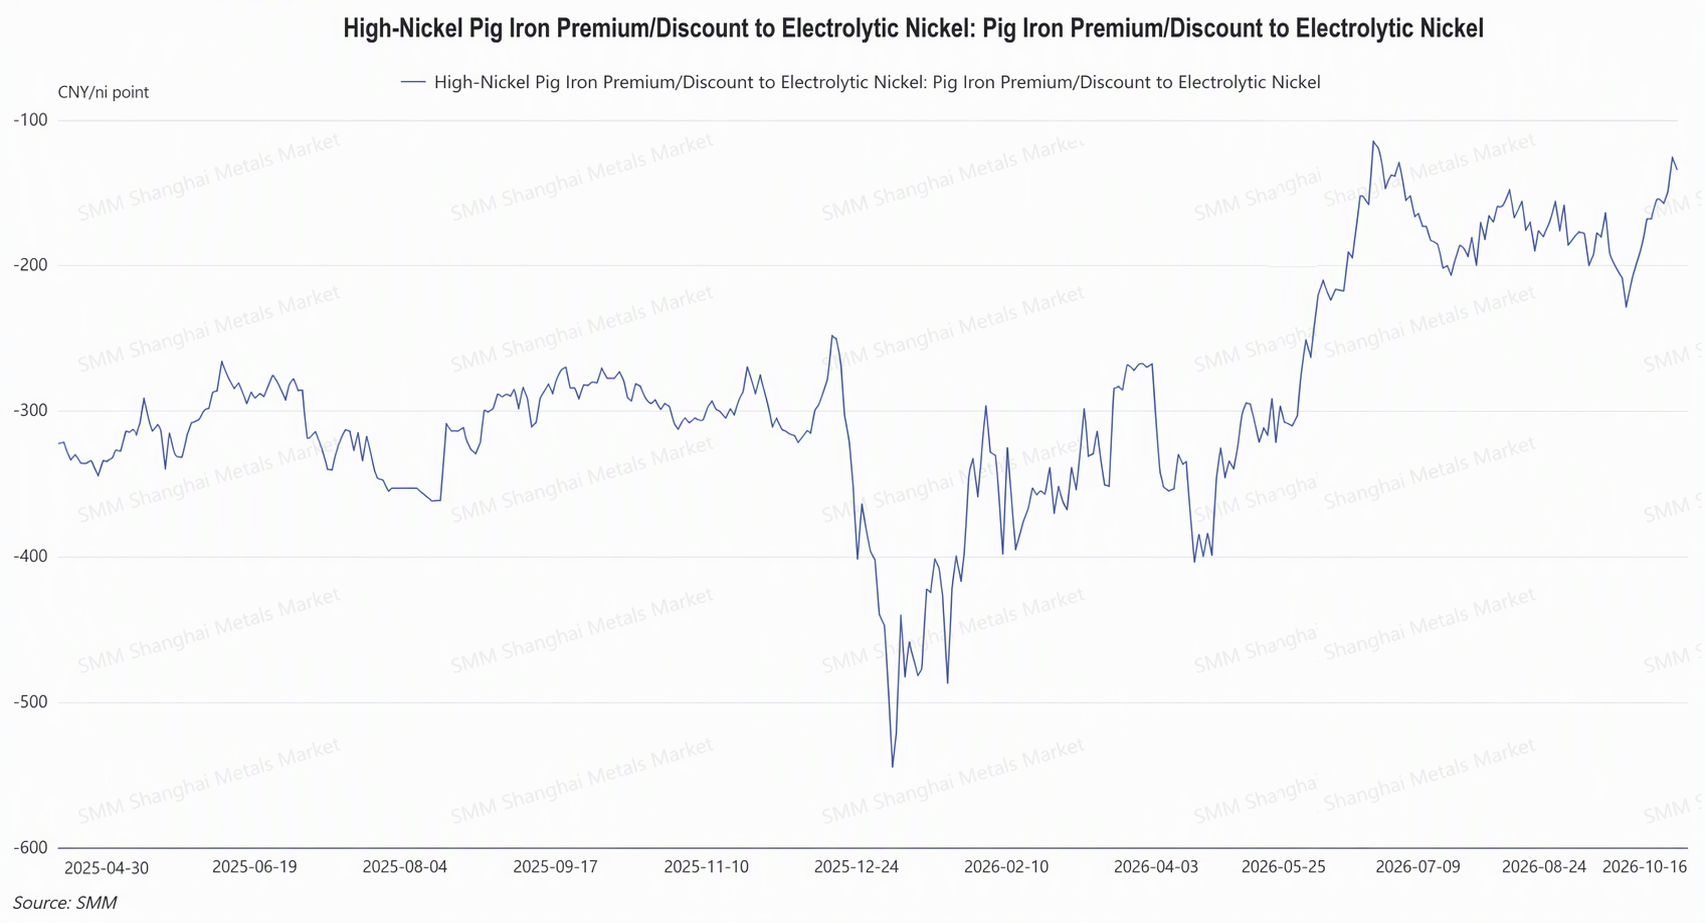
From the perspective of converting NPI to high-grade nickel matte, this week the discount of high-grade NPI to refined nickel was 143.1 yuan/nickel unit, narrowing by 17.2 yuan/nickel unit WoW. This week, refined nickel futures fell more than NPI spot prices, and the spread between the two narrowed significantly, with the discount briefly narrowing to 125.5 yuan/nickel unit on Friday. Looking ahead to next week, under the current fundamental landscape, the discount of high-grade NPI to refined nickel is unlikely to widen notably, still not enough to drive conversion of NPI to high-grade nickel matte. NPI continues to offer higher profitability by comparison.
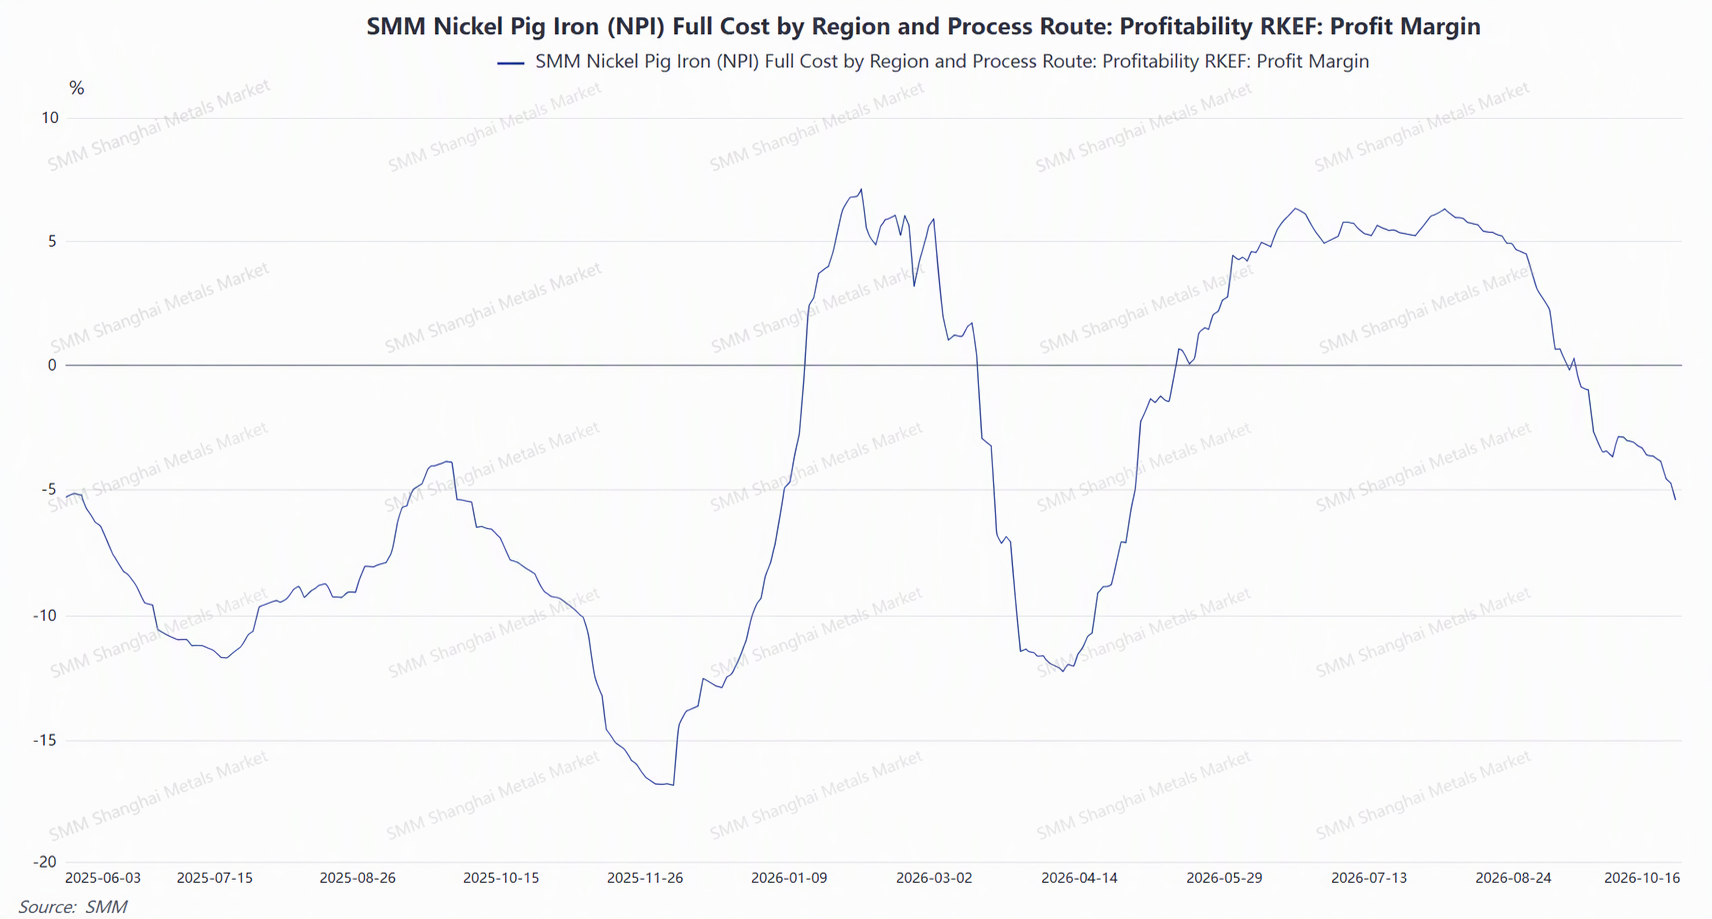
This week, raw material prices for high-grade NPI smelting pulled back across the board. On the nickel ore side, the average price of Philippine laterite nickel ore 1.4% (CIF China) fell from $53.5/wmt to $52.5/wmt, while Indonesia domestic trade saprolite nickel ore 1.6% (delivered price) fell from $59/wmt to $57.1/wmt. Ore prices in both regions were lowered during the week, and smelting cost lines shifted down slightly accordingly. Auxiliary material prices remained broadly stable, with no notable fluctuations. However, the pullback in raw material prices was significantly smaller than the decline in product prices—this week, high-grade NPI spot prices fell from 1,037 yuan/nickel unit all the way down to 1,019.5 yuan/nickel unit, a weekly decline of 17.5 yuan/nickel unit. The cost relief released by ore price concessions was entirely swallowed by the drop in product prices. As a result, smelting margins in both China and Indonesia narrowed simultaneously.