[SMM Analysis] Downstream Stocking Boosts LiPF6 Demand, Supply Growth Release Remains Slow

Published: Oct 16, 2026 14:03 (GMT+8)
[SMM Analysis: Downstream Stocking Boosts LiPF6 Demand, Supply Growth Release Remains Slow] In September 2026, China's LiPF6 production continued to edge up, rising about 3.4% MoM from August and about 59% YoY. The overall pace of supply release remained relatively slow, and the supply-demand tight balance persisted.
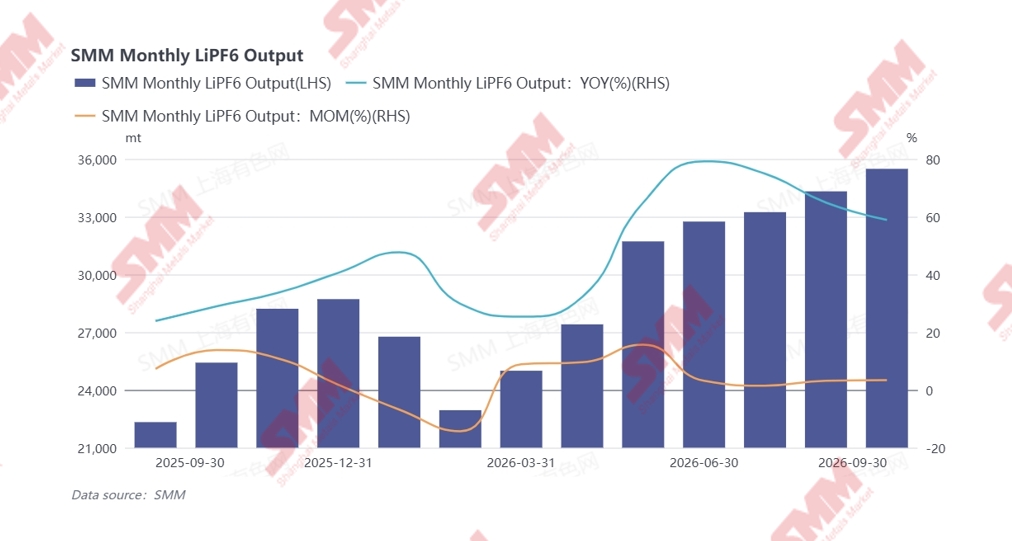
In September 2026, China's LiPF6 production continued to edge up, rising about 3.4% MoM from August and about 59% YoY. The overall pace of supply release remained relatively slow, and the supply-demand tight balance persisted.

On the demand side, end-use demand for lithium batteries continued to improve in September. Coupled with electrolyte producers stocking up on raw materials in advance ahead of the National Day holiday, downstream procurement demand for LiPF6 strengthened, providing core support for the current market upturn. On the supply side, however, although LiPF6 prices continued to rise, overall production growth remained relatively limited, constrained mainly by two factors.

First, capacity was limited. Most LiPF6 producers in the industry are currently operating at full capacity, while some new capacity is still in the ramp-up stage. Given the high technical barriers in LiPF6 production processes and stringent requirements for production environments and quality control, the actual ramp-up progress of some new production lines has fallen short of expectations, making it difficult to quickly release additional output.

Second, producers showed limited willingness to expand output. This month, prices of the key raw material lithium carbonate continued to decline, while end-use demand growth fell short of pre-September peak season market expectations. Although LiPF6 producers themselves sought price increases, the cost pressure from earlier LiPF6 price rises has not yet been fully passed on by electrolyte enterprises to downstream battery clients, and downstream acceptance of further LiPF6 price hikes remains low, limiting actual market price increases. Against this backdrop, even enterprises with spare capacity were reluctant to rapidly raise operating rates without clear justification.

Looking ahead, the October peak season is expected to drive further improvement in demand. Demand in the energy storage segment continues to trend positively, while the EV sector may benefit from the December 1 implementation of export restrictions on hybrid models to Europe, potentially triggering a short-term rush to export and boosting LiPF6 demand. However, electrolyte enterprises' earlier optimistic expectations in September led to advance stockpiling, yet actual end-user output fell short of expectations. Combined with the continued decline in lithium carbonate prices, electrolyte enterprises have adopted a more cautious purchasing stance with weaker willingness to buy. LiPF6 producers, sensing weak downstream demand, are similarly reluctant to proactively increase output. On balance, China's LiPF6 production growth in October is expected to remain at a moderate pace.


Note: If you have any supplements or corrections regarding the details mentioned in this article, please feel free to contact us. Contact information is as follows:

Tel: 021-20707858 Hu Xuejie, Thank you!


SMM New Energy Research Team

Wang Cong 021-51666838

Ma Rui 021-51595780

Feng Disheng 021-51666714

Lyu Yanlin 021-20707875

Zhang Haohan 021-51666752

Wang Zihan 021-51666914

Wang Jie 021-51595902

Xu Yang 021-51666760

Xu Mengqi 021-20707868

Hu Xuejie 021-20707858
Data Source Statement: Except for publicly available information, all other data are processed by SMM based on publicly available information, market communication, and relying on SMM's internal database model. They are for reference only and do not constitute decision-making recommendations.

Images in this article contain AI-translated captions for reference only.

For any inquiries or for more information, please contact: lemonzhao@smm.cn
For more information on how to access our research reports, please contact:service.en@smm.cn
Related News
PLS Approves Final Investment Decision for P2000 Expansion at Pilgangoora [SMM Analysis]
17 mins ago
PLS Approves Final Investment Decision for P2000 Expansion at Pilgangoora [SMM Analysis]
Read More
PLS Approves Final Investment Decision for P2000 Expansion at Pilgangoora [SMM Analysis]
17 mins ago
[SMM Analysis] September demand growth fell short of expectations, and the increase in electrolyte production narrowed
1 hour ago
[SMM Analysis] September demand growth fell short of expectations, and the increase in electrolyte production narrowed
Read More
[SMM Analysis] September demand growth fell short of expectations, and the increase in electrolyte production narrowed
[SMM Analysis] September demand growth fell short of expectations, and the increase in electrolyte production narrowed
[SMM Analysis: September demand growth fell short of expectations, and the increase in electrolyte production narrowed] In September 2026, despite simultaneous expansion on both the supply and demand sides of China's electrolyte industry, market sentiment still improved somewhat, though the growth rate narrowed significantly from the previous month. According to available data, China's total electrolyte production in September rose about 2.8% MoM from August and increased about 66% YoY.
1 hour ago
[SMM Cobalt-Lithium Morning Meeting Summary] Supply-demand expectations diverge, material prices under pressure, industry chain prosperity diverges
5 hours ago
[SMM Cobalt-Lithium Morning Meeting Summary] Supply-demand expectations diverge, material prices under pressure, industry chain prosperity diverges
Read More
[SMM Cobalt-Lithium Morning Meeting Summary] Supply-demand expectations diverge, material prices under pressure, industry chain prosperity diverges
[SMM Cobalt-Lithium Morning Meeting Summary] Supply-demand expectations diverge, material prices under pressure, industry chain prosperity diverges
Industry chain prices were generally under pressure this week, with supply and demand diverging across segments. The lithium market was hit by expectations of ample future supply, dragging the average battery-grade lithium carbonate price down to 104,400 yuan/mt, a weekly decline of 14.7%. Spot destocking and a stronger basis still provided some support, but salt plant inventories edged higher. Cobalt and nickel demand recovery remained insufficient, with cautious procurement keeping salt prices on a downtrend. Ternary cathode materials and LCO faced dual pressure from falling costs and weak orders. LFP supply and demand were stable, with prices easing alongside raw materials. Artificial graphite found relatively strong cost support, separator inventories were low with tightening supply-demand conditions, and electrolyte prices held steady. Sodium-ion battery orders grew and capacity releases accelerated, but profitability recovery lagged, leaving commercialization still constrained by economics. In the recycling market, black mass prices and procurement coefficients moved lower, strengthening buyer bargaining power. Competition intensified in end-user energy storage project bidding, with Jieyang project candidate quotes concentrated at 0.8–0.82 Yuan/Wh. Going forward, attention should focus on ore-side production resumptions, production schedule fulfillment, and actual restocking; industry chain stabilization still hinges on demand improvement.
5 hours ago