SMM data shows that China's copper semis production in September was 1.7257 million mt, up 3.5% MoM and down 4.25% YoY. From January to September, cumulative production reached 15.6382 million mt, up 1.16% YoY.
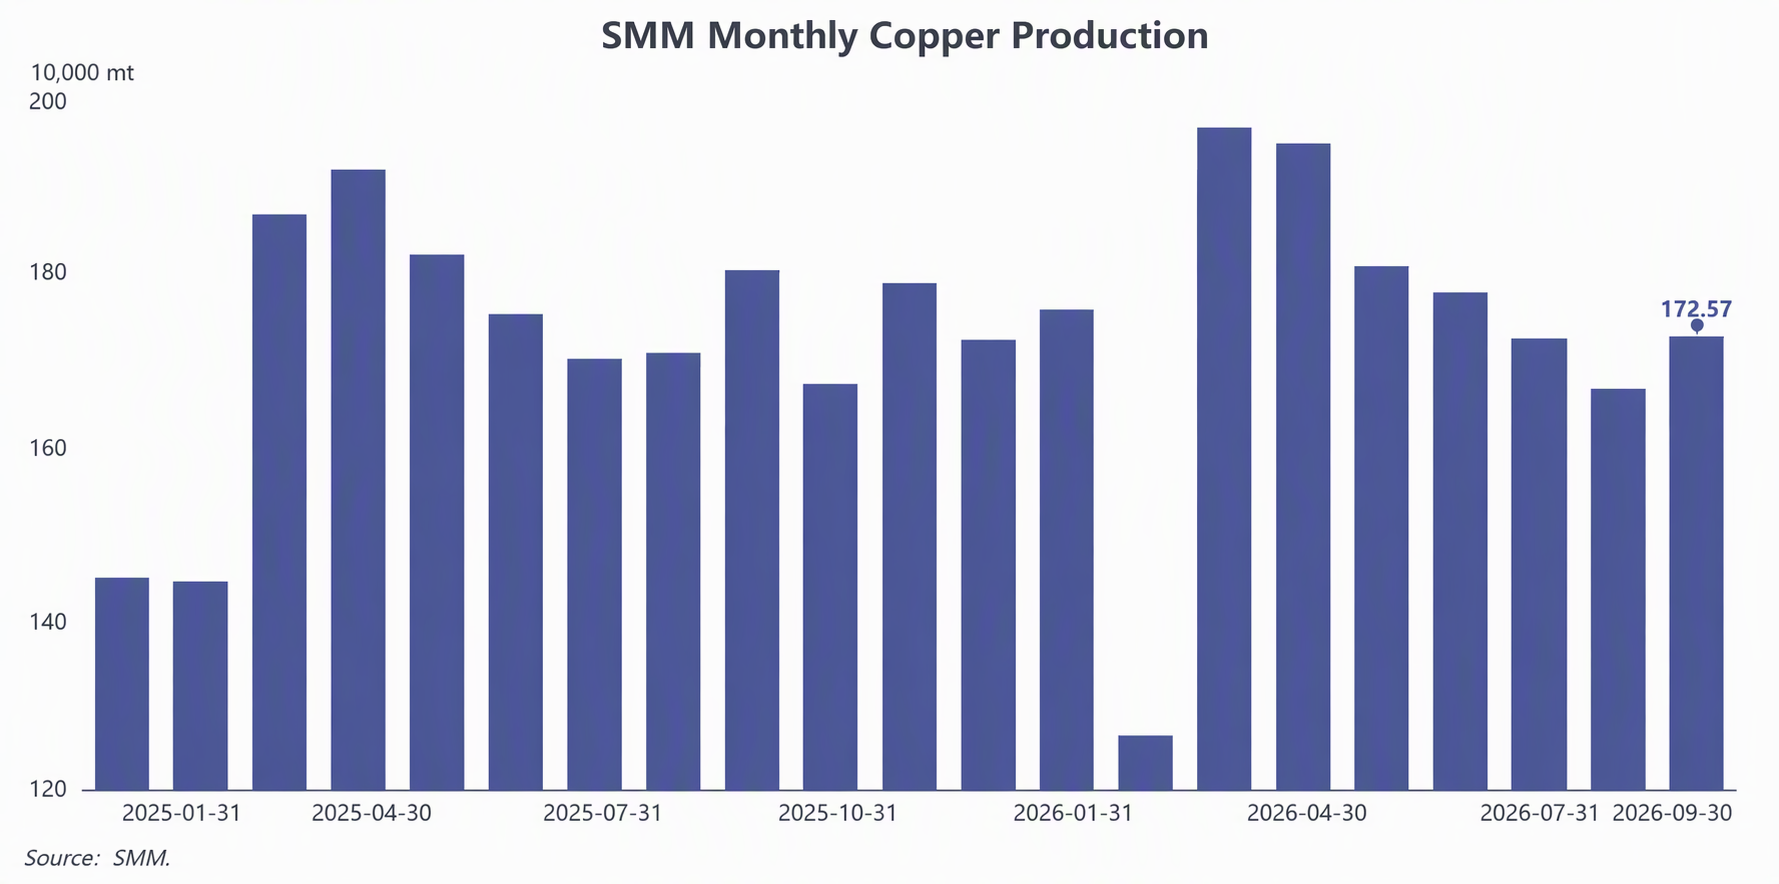
Entering September, the copper semis market reached a critical window for the seasonal transition between slack and peak periods. According to SMM's entire industry chain survey, although copper prices remained high overall during the month, the mid-month pullback effectively stimulated downstream restocking interest at lower prices. With the release of concentrated pre-National Day holiday stockpiling demand from enterprises, copper semis producers accelerated their production schedules and output rebounded.
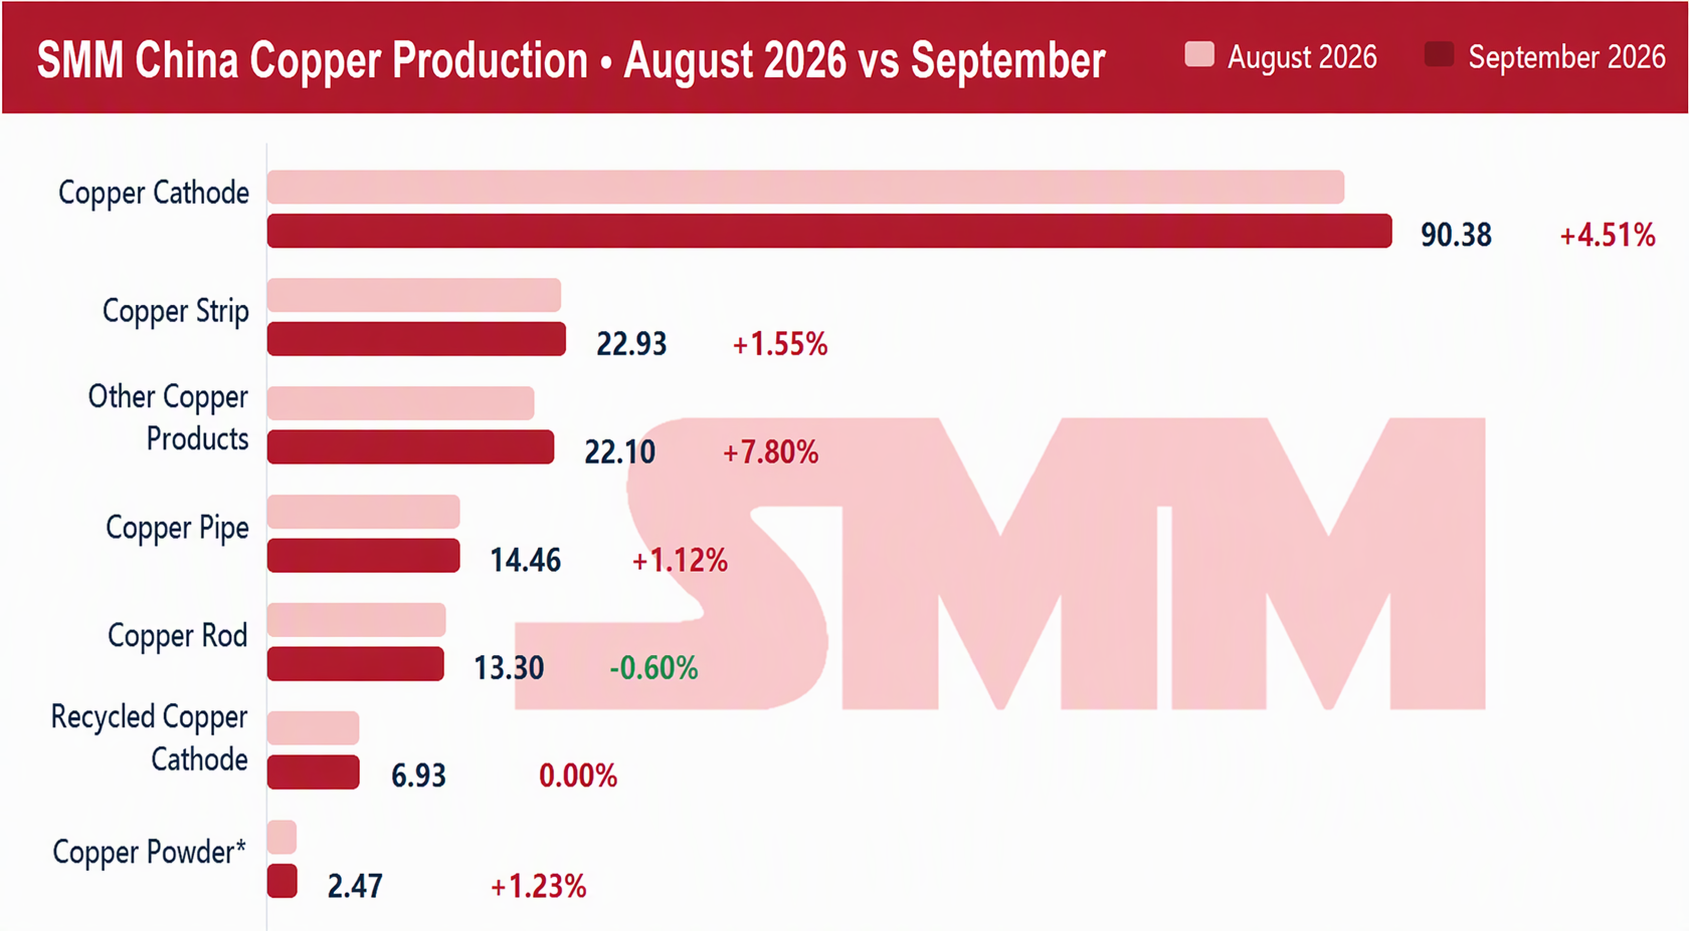
Unit: 10 kt; Copper foil scope: only production using purchased copper cathode as raw material is counted
By product category, performance across segments showed significant structural divergence:
Copper cathode rod: September production rebounded to 903,800 mt (up 4.51% MoM, down 4.46% YoY). The notable pullback in copper prices in mid-September effectively opened a restocking window for downstream buyers. Improved purchasing sentiment, combined with pre-holiday stockpiling demand, became the core driver behind the production rebound. However, amid the tug-of-war between high copper prices and a high basis, downstream enterprises remained relatively cautious in their pre-holiday stocking, with overall intensity weaker than the same period in previous years.
Secondary copper rod: Affected by policy-side disruptions, September production was only 69,300 mt, basically flat MoM and sharply down 51.47% YoY. With raw material supply remaining constrained, the contraction trend in secondary copper rod production has yet to bottom out. Notably, some wire and cable demand was forced to shift to copper cathode rod, and this "substitution effect" objectively became an important driver boosting copper cathode rod production schedules.
Copper plate/sheet, strip and foil: As the most certain bright spot in Q4, overall production showed a strong trend of "MoM rebound and high YoY growth." In September, copper plate/sheet and strip production reached 229,300 mt (up 1.55% MoM, up 21.26% YoY), and copper foil production reached 24,700 mt (up 1.23% MoM, up 30.00% YoY). As the only two subcategories maintaining high YoY growth across all product types, their strong performance mainly benefited from the sustained release of high-end manufacturing demand in AI computing power and energy storage, power batteries, NEV components, and integrated circuits, with structural growth driven by industrial upgrading being a notable feature. (Note: Copper foil production only includes output using purchased copper cathode as raw material)
Copper pipe & tube and billet: Production recovery was limited, and YoY weakness persisted. September copper pipe & tube production was 144,600 mt (up 1.12% MoM, down 6.1% YoY). Despite the MoM improvement, the YoY decline in air-conditioner domestic sales and exports production schedules, along with cost pressure from high copper prices and high premiums, meant peak-season demand recovery fell short of expectations. Copper billet production was 133,000 mt (down 0.60% MoM, down 16.56% YoY). Under the dual pressure of high copper prices and tight recycled brass raw material supply, copper billet producers showed weak production enthusiasm, and end-use demand continued to shrink, leading to a sustained contraction on the production side.
October outlook: holiday drags copper semis production, high-end demand continues to provide support
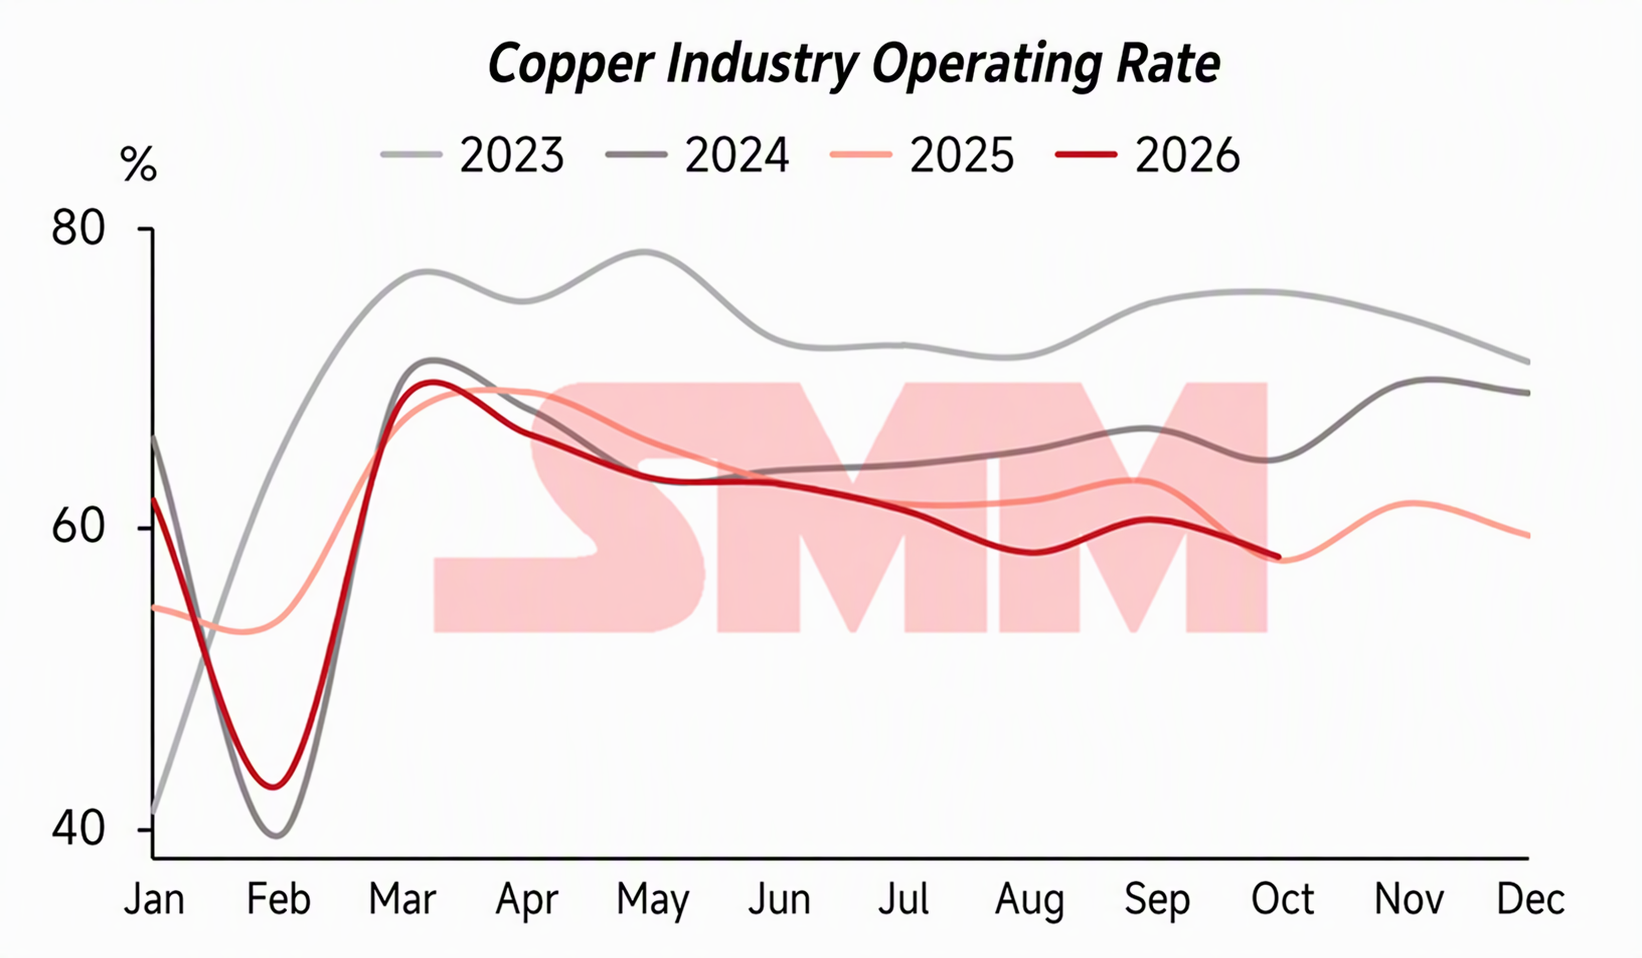
SMM's latest data shows that, dragged by fewer production days during the National Day holiday and the continued contraction of secondary copper rod, the overall operating rate of the copper semis industry in October is expected to pull back to 58.07% (down 1.47% MoM, down 1.03% YoY), with total copper semis production in October falling slightly to 1.6213 million mt.
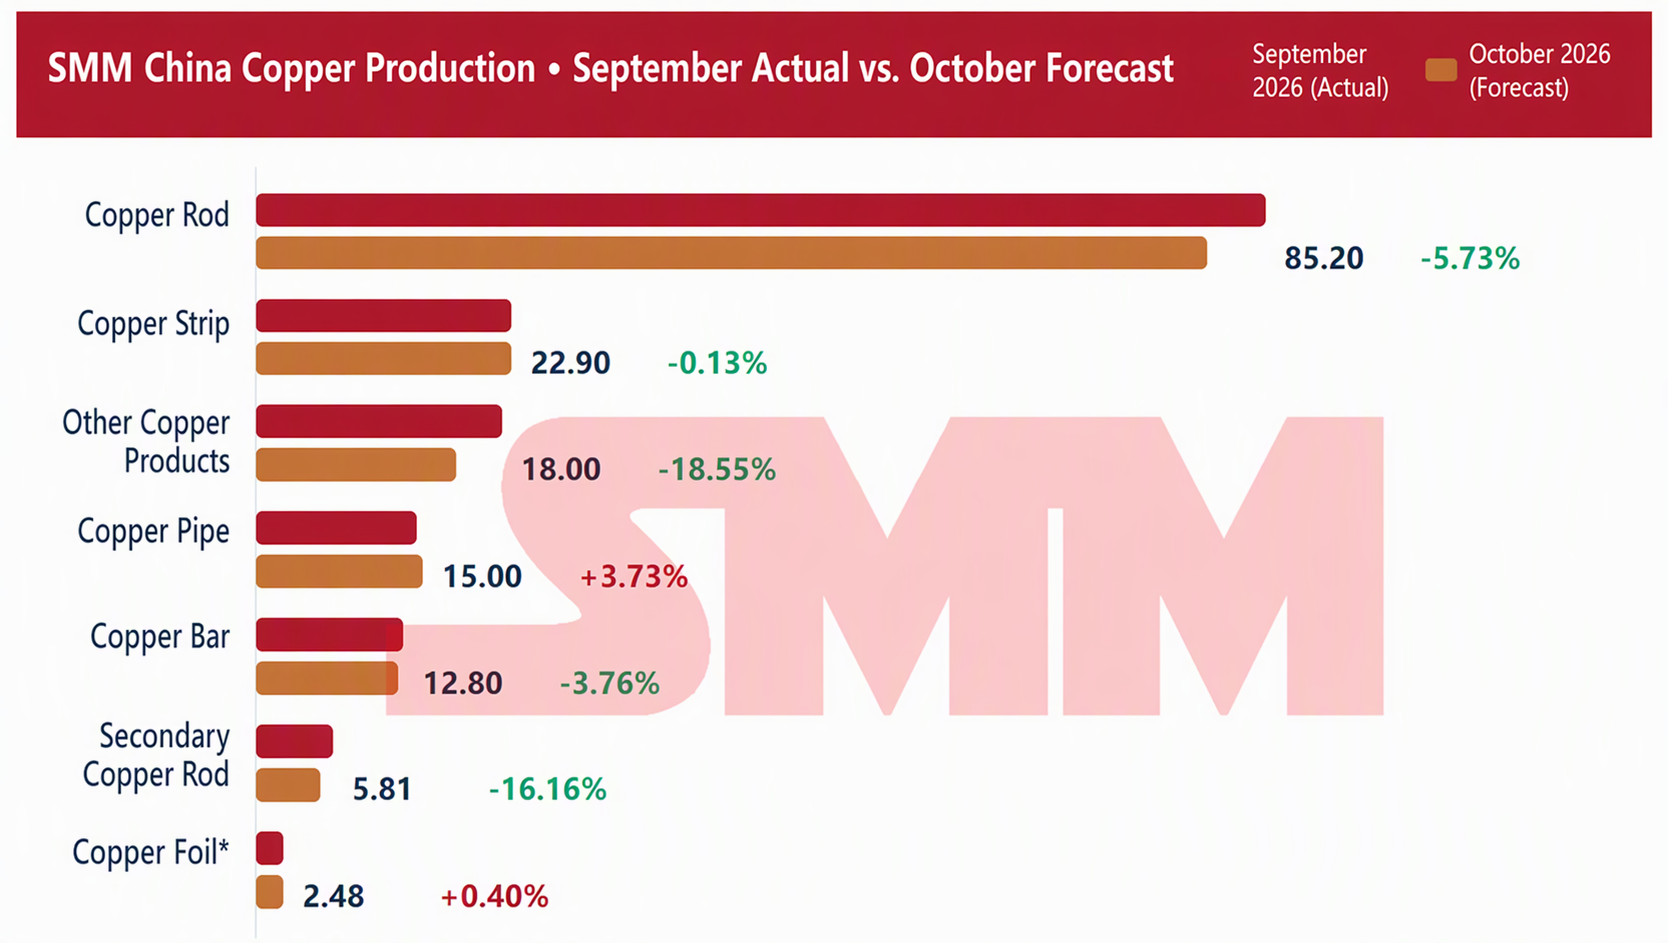
Unit: 10 kt; October E is based on SMM enterprise production schedule surveys and already includes the National Day holiday impact; Copper foil scope: only production using purchased copper cathode as raw material is counted
Looking at subcategories and end-use demand performance, on one hand, copper plate/sheet, strip and foil continued their strong momentum, becoming the most certain growth engine in the peak season. Driven by robust demand in emerging fields such as AI computing power servers, NEV components, concentrated energy storage project deliveries, and high-end transformers, plate/sheet, strip and foil producers' production schedule plans continued to lead the industry. In particular, copper strip, alloy strip, and electronic circuit copper foil had extremely high order visibility and strong peak-season performance, effectively supporting the overall operating rate of copper semis. On the other hand, under the pressure of high copper prices and a high basis, downstream demand was suppressed, and the peak-season performance of copper rod, copper billet, and copper pipe & tube still needs to be tested.
Overall, the pullback in semi-finished copper products operating rates in October was more of a "short-term disturbance driven by holiday factors" rather than a structural weakening of the industry trend. At the structural level, high-end manufacturing demand represented by copper foil and copper plate/sheet and strip remains the core growth engine driving the copper semis industry's upward breakthrough, while copper rod, which accounts for a high base weight, constitutes the fundamental base determining the overall performance of copper semis. Looking ahead, as Q4 power grid tenders enter a period of concentrated release, overall copper semis demand still has strong resilience and is worth looking forward to, but wide fluctuations in copper prices will continue to test the real cargo pick-up capability of end-users. SMM will continue to closely track marginal changes in operating rates and inventory data across all segments of the industry chain, providing precise data navigation and decision-making support for industry enterprises.