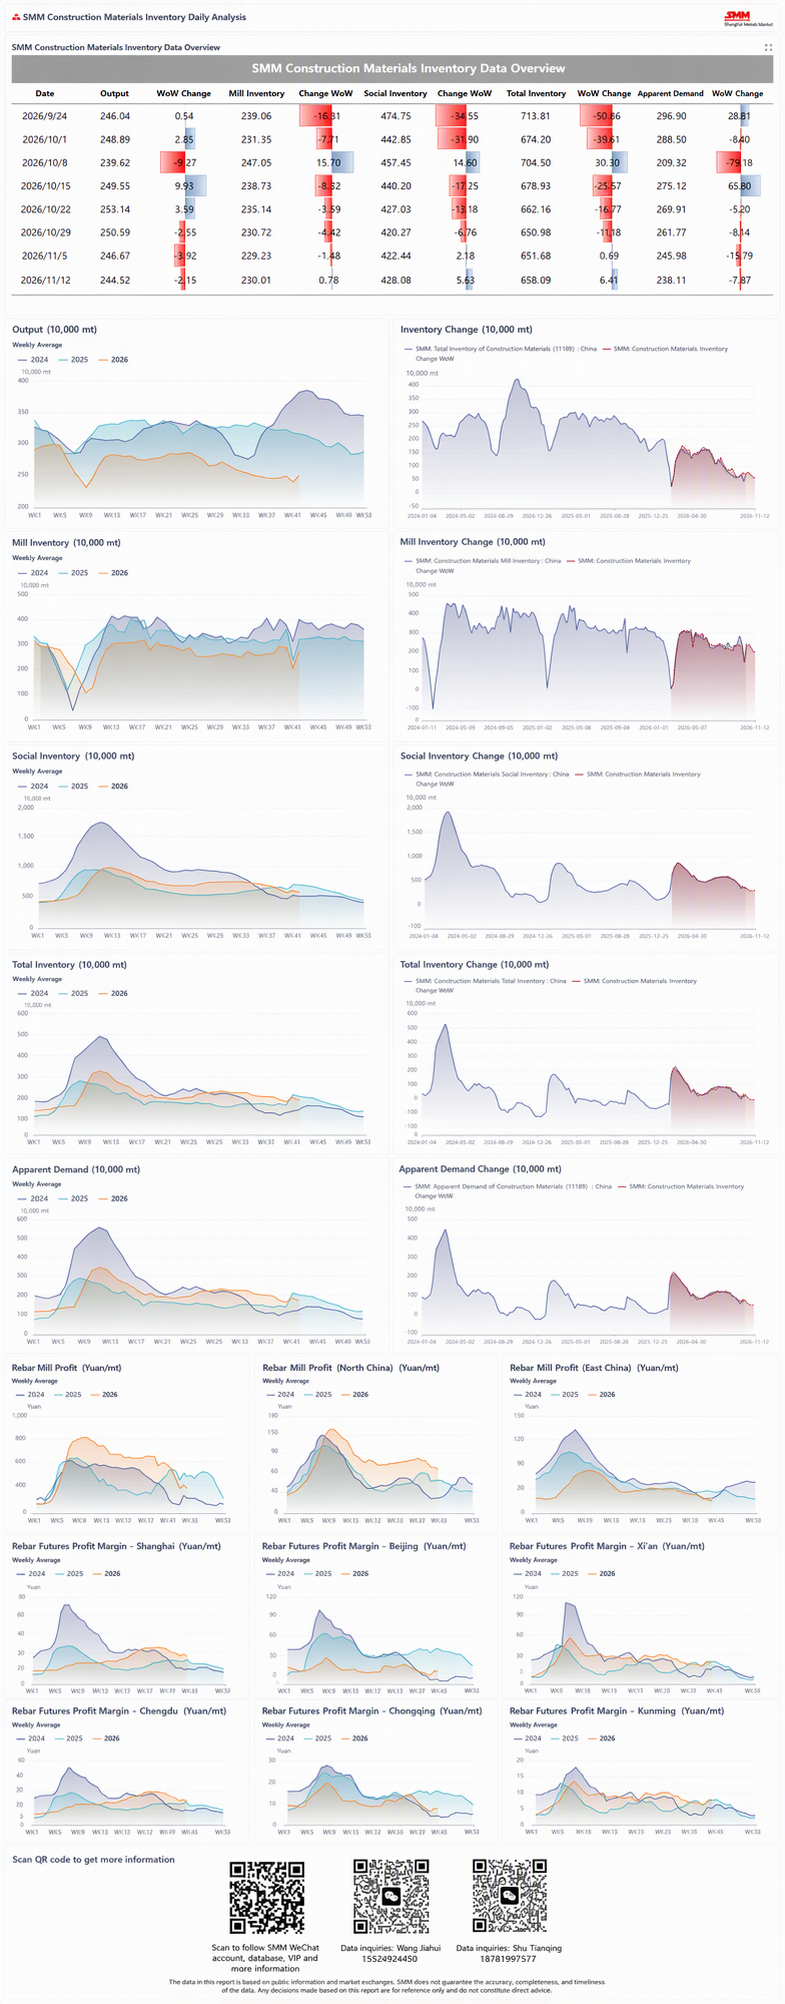
Supply side, most blast furnace steel mills are maintaining their current unsaturated production pace, with only a few producers resuming rolling line production as planned. After two rounds of coke price cuts were implemented, the cost-effectiveness of hot metal improved, easing the pressure on steel scrap procurement for electric furnaces. Coupled with per-tonne steel margins generally staying above the break-even line, some electric furnace mills have extended operating hours or resumed production. Demand side, the National Day holiday last period disrupted terminal construction and logistics transportation, causing a sharp decline in building materials demand. After the holiday, as demand gradually returned to normal levels and trading sentiment improved, apparent demand rose significantly WoW. According to SMM statistics, this period saw destocking in building materials mill inventories and social inventories, with total building materials inventory at 6.7893 million mt, down 255,700 mt WoW, or -3.63% WoW, shifting inventory changes from an increase to a decrease.