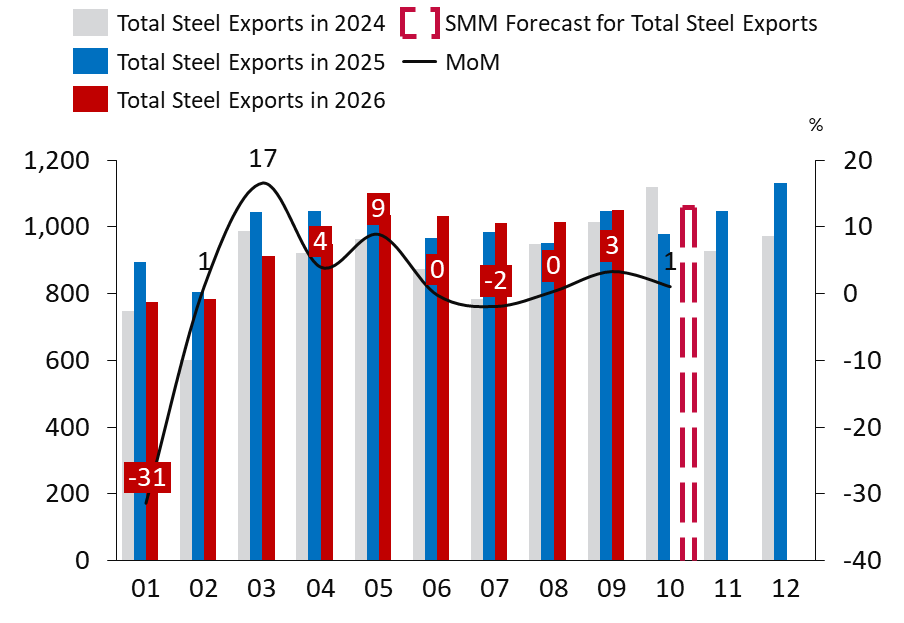
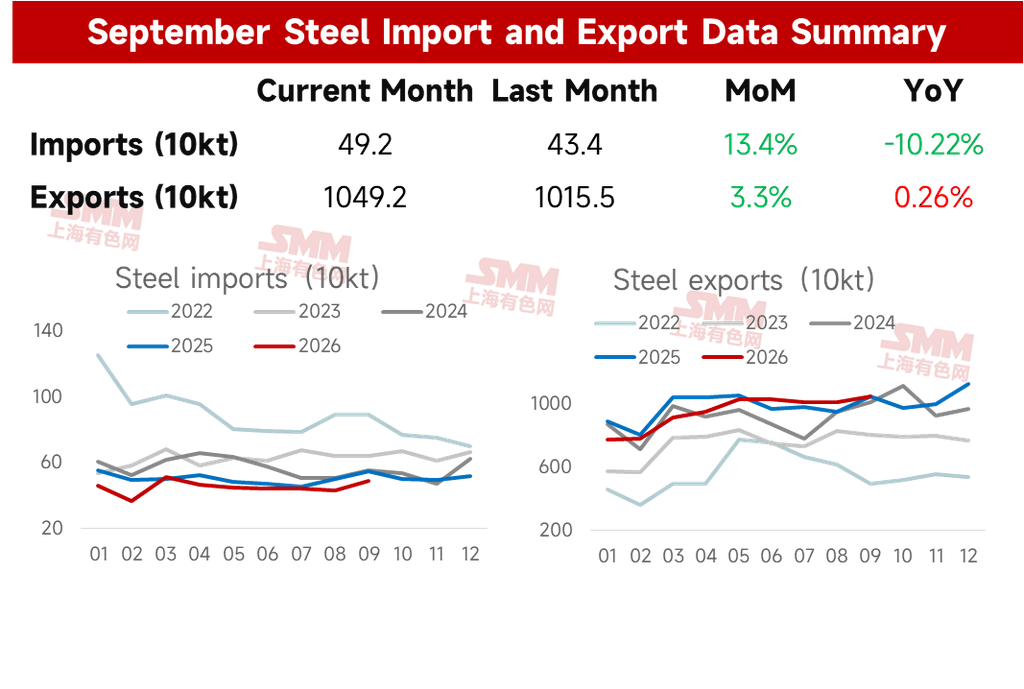
On October 14, data from the General Administration of Customs showed that China exported 10.492 million mt of steel in September 2026, up 337,000 mt MoM, a rise of 3.3%; cumulative exports in January-September reached 85.641 million mt, down 2.6% YoY.
China imported 492,000 mt of steel in September 2026, up 58,000 mt MoM, a rise of 13.5%; cumulative imports in January-September reached 4.066 million mt, down 10.5% YoY.
Table 1 - Steel import and export data overview for January-September
• China's steel exports rose MoM in September
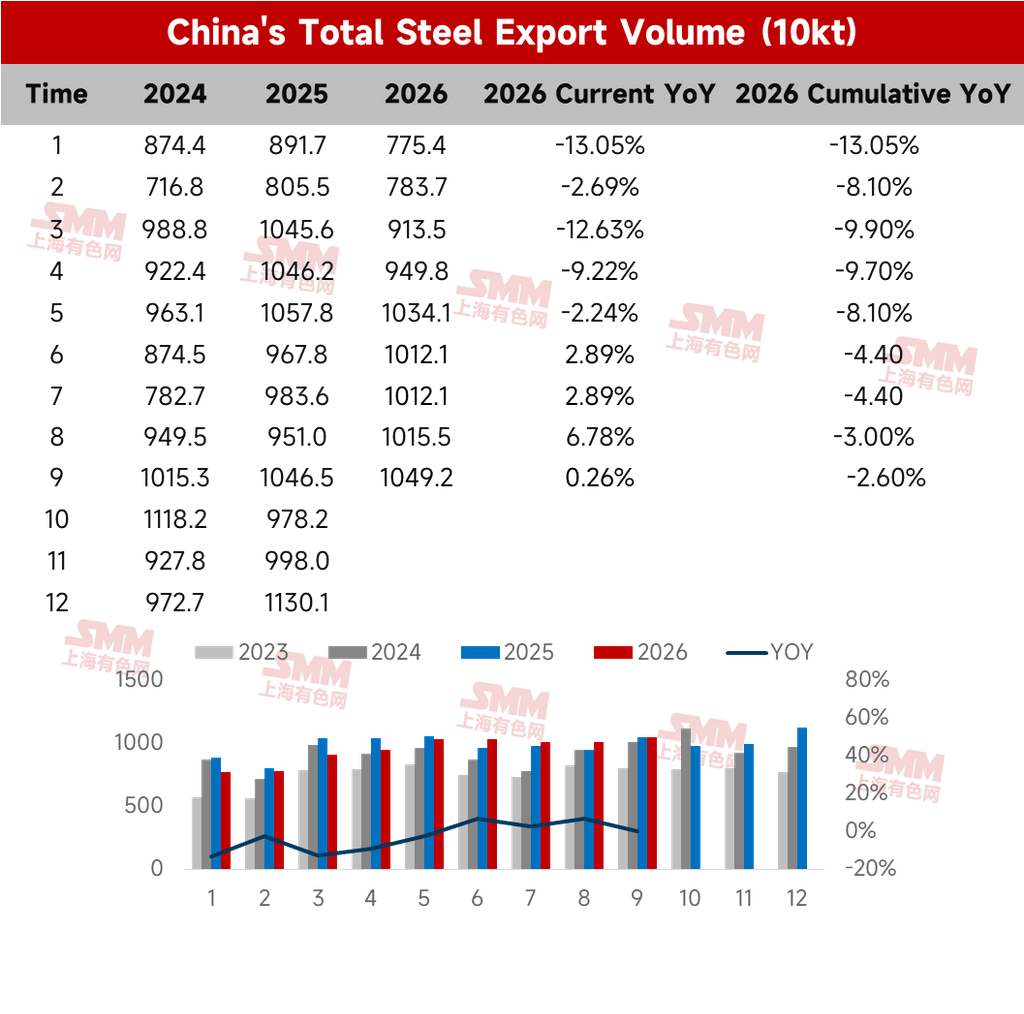
According to SMM's September export schedule survey, the planned HRC export volume for the month was 1.072 million mt, up 5.63% from actual exports in August. SMM export order data shows that from early July to August, steel export orders rebounded from a bottom. In the earlier period, the phased depreciation of the yuan, combined with poor domestic trade conditions at steel mills, led mills to cut prices to secure export orders, releasing some long steel export orders. Later, demand for sheets & plates from Pakistan and Türkiye was released, making overall order-taking relatively favorable. As a result, steel exports in September maintained a relatively good growth pace overall.
Table 2 - China's total steel exports
• China's steel imports remained low in September
On the import side, September steel imports were 492,000 mt, up 58,000 mt MoM, a rise of 13.5%; cumulative imports in January-September were 4.066 million mt, down 10.5% YoY. In January-September, net steel exports reached 81.575 million mt.
• Short-term steel export outlook
1. Global manufacturing PMI rose MoM; manufacturing supply and demand resonated
According to J.P. Morgan global PMI data, the global manufacturing PMI recorded 53 in September 2026, a 55-month high, with all five sub-indices improving simultaneously for three consecutive months. This was mainly driven by AI- and national defense-related demand, and new export orders also rose to their highest since July 2021. This will provide some support for China's steel exports, and this round of increases reflects a resonance between global manufacturing supply and demand. In July, China's manufacturing new export orders index stood at 50%, down 0.1 percentage point MoM, still in expansion territory.
2. Overseas steel mill production continued to decline; supply contraction brings opportunities for domestic exports
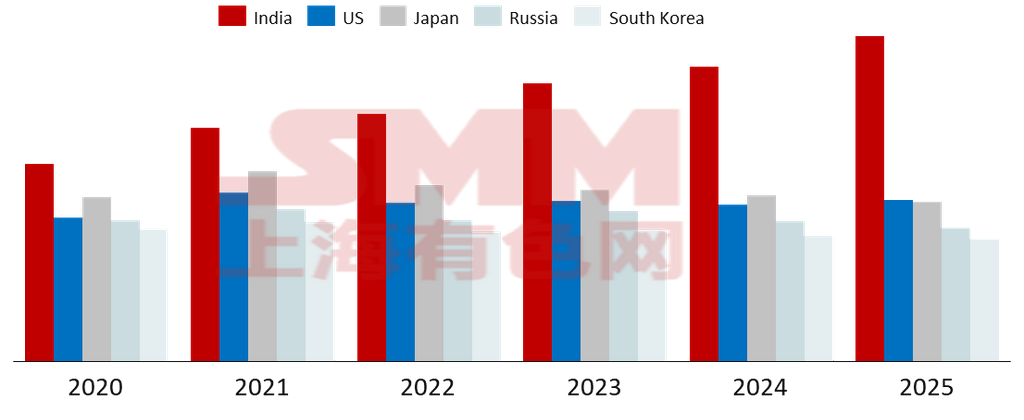
Global crude steel production in August 2026 was 144.2 million mt, down 1.2% YoY. China's average daily crude steel production in August was 2.4068 million mt (down 3.0% MoM), with cumulative output in January-August at 652 million mt, down 3.1% YoY. Excluding China, overseas production in August was approximately 69.6 million mt, up 1.6% YoY, a notable slowdown from the +3.5% growth in July, and down 3.7% MoM, mainly due to the EU turning negative YoY and the CIS weakening again. The EU's negative turn stemmed from stockpiling that overdrew demand rather than tariff ineffectiveness. To avoid the new tariffs effective July 1, European buyers had stockpiled large volumes of imported inventory from Q4 2025 through Q2 2026, and in Q3 they shifted to destocking and wait-and-see. In September, steel mill order books were only half full, and summer break shutdowns were extended. In India, August production was 14.8 million mt, up 4.6% YoY and up 2.8% MoM, the strongest MoM performance among the top ten steel-producing countries. The Middle East's YoY decline narrowed from -27.6% in April to -4.6%, mainly due to Iran's production resumptions and equipment ramp-up. Russia and other CIS countries recorded -5.6% (Russia itself -0.3%), remaining the largest drag outside China. Vietnam produced 2.7 million mt, up 36.4% YoY, but with Hoa Phat's Dung Quat Phase 2 No. 2 blast furnace starting production in September 2025, YoY growth will automatically fall back to single digits from next month due to a high base. The decline in overseas production will bring structural opportunities for domestic exports.
Figure 1 - Global crude steel production by region
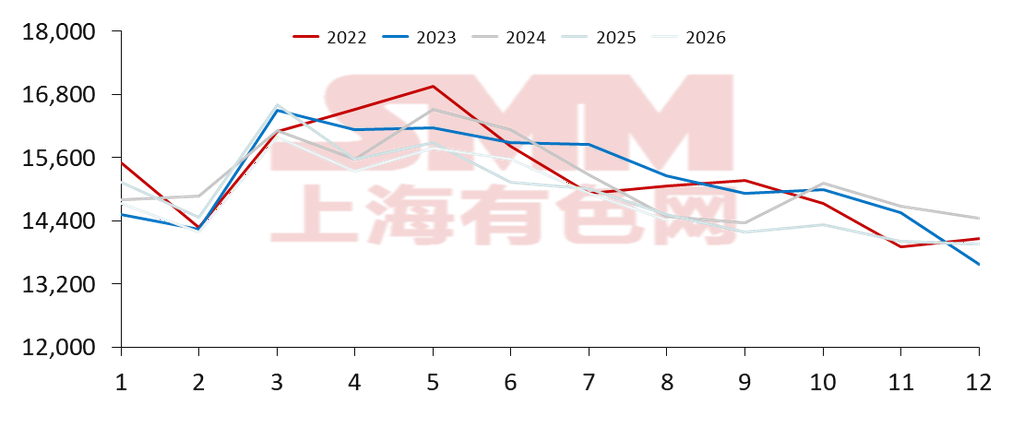
Figure 2 - Crude steel production in major producing areas
3. Price advantage widened significantly; export order-taking improved
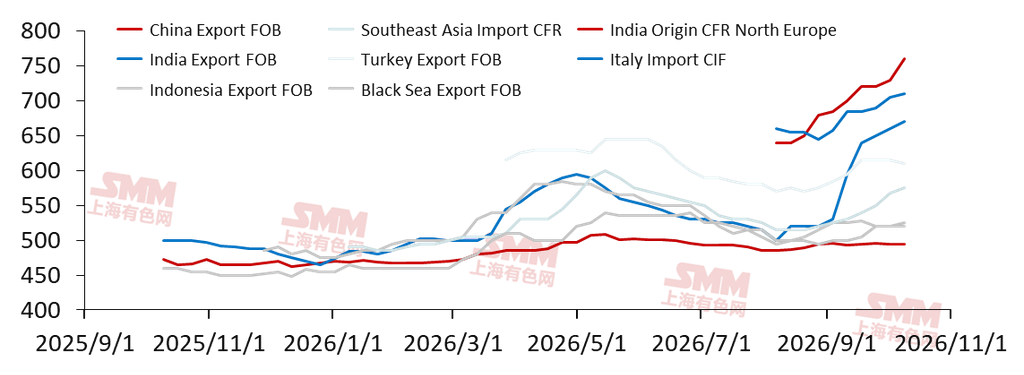
As of October 2, 2026, HRC export quotes (FOB) from India, Türkiye, and the CIS were $660/mt, $615/mt, and $520/mt respectively, while China's HRC export quote (FOB) was $495/mt. Currently, China's HRC export quotes are -$160/mt, -$120/mt, and -$25/mt versus other countries respectively. China's steel export price advantage widened notably MoM from August. In September, overseas demand gradually recovered, and new maintenance plans at mills in Indonesia and Vietnam helped drive a clear recovery in overall overseas prices. Meanwhile, domestic demand recovery fell short of expectations, raw material support weakened, and price movements were relatively flat. The price spread between Chinese and overseas markets widened, and export order-taking improved.
Figure 3 - HRC quotes in major global markets
4. September export orders improved notably; demand for both sheets & plates and long steel increased
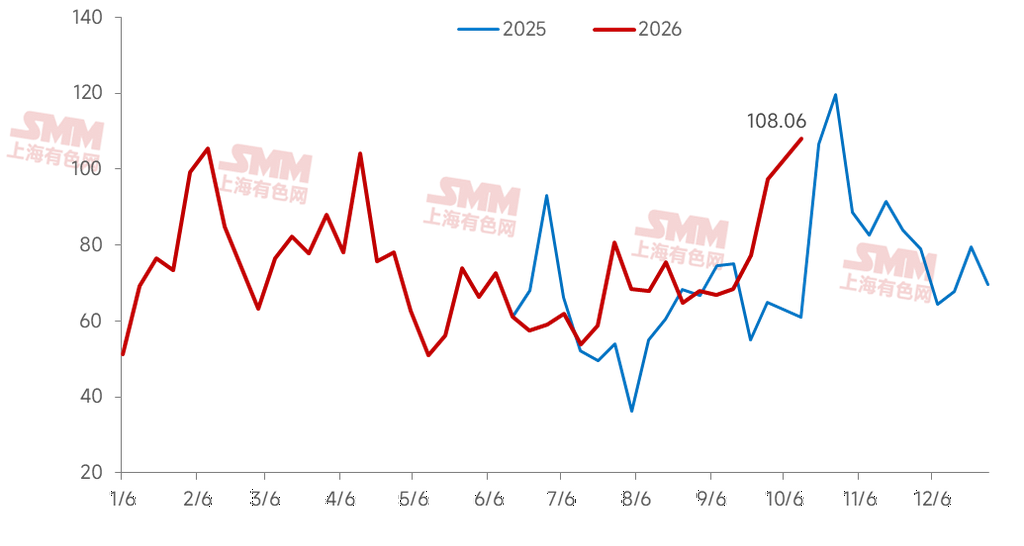
According to SMM's latest steel mill export order data, this month's planned export volume was 999,000 mt, down 66,000 mt from actual exports last month, a MoM decline of 6.2%. The pullback in total volume was not a broad-based industry weakening; the core disturbance came from maintenance in October at a major mill in east China, which has a high export share and dragged down the overall export reading. From SMM's steel export order performance, total orders in September recorded 3.2565 million mt, up 6.60% MoM from 3.0547 million mt in August, marking the third consecutive month of MoM growth. By product, both long steel and sheets & plates grew, with a more balanced structure: long steel orders were 1.6151 million mt, up sharply by 12.07% MoM, reversing the -1.83% pullback in August. Among them, steel billet orders improved relatively, on one hand because the previous export order base was low and there was overseas demand backfilling; on the other hand, just-in-time procurement in ocean-going regions still provided support, driving a recovery in square billet orders. Sheets & plates orders were 1.6413 million mt, continuing to edge up 1.72% MoM, maintaining resilience after the high growth of +16.24% in August. However, because quotes rose relatively quickly, some demand follow-through was limited. Nevertheless, Türkiye and the Middle East still saw incremental just-in-time procurement, with Türkiye's demand increase mainly driven by the supply gap from Russian sources.
Figure 4 - SMM steel export order volume5. Increase in steel anti-dumping cases in September
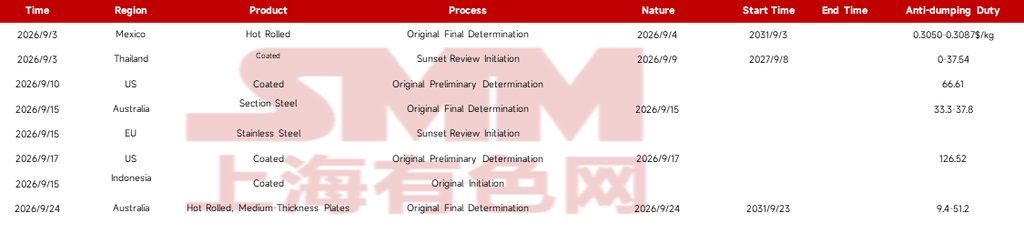
In September, the number of new anti-dumping related cases in China increased, involving hot-rolled products, coated products, section steel, stainless steel, and medium-thickness plates. The specific cases and affected volumes are shown in the table below:
Table 3 - New anti-dumping cases in September
Taking all factors into consideration, benefiting from the rise in global manufacturing activity in September, which drove a recovery in demand outside China, coupled with the strong price competitiveness of domestic steel, steel export orders achieved significant growth. Based on this, SMM expects that total steel exports in October are likely to continue the upward trend and hit a new high for the year. In the improvement of export orders from August to September, semi-finished products made a significant contribution, which is reflected in the product mix, with steel billet exports expected to maintain a strong performance.
Figure 4 - Steel exports and forecasts, 2024-2026