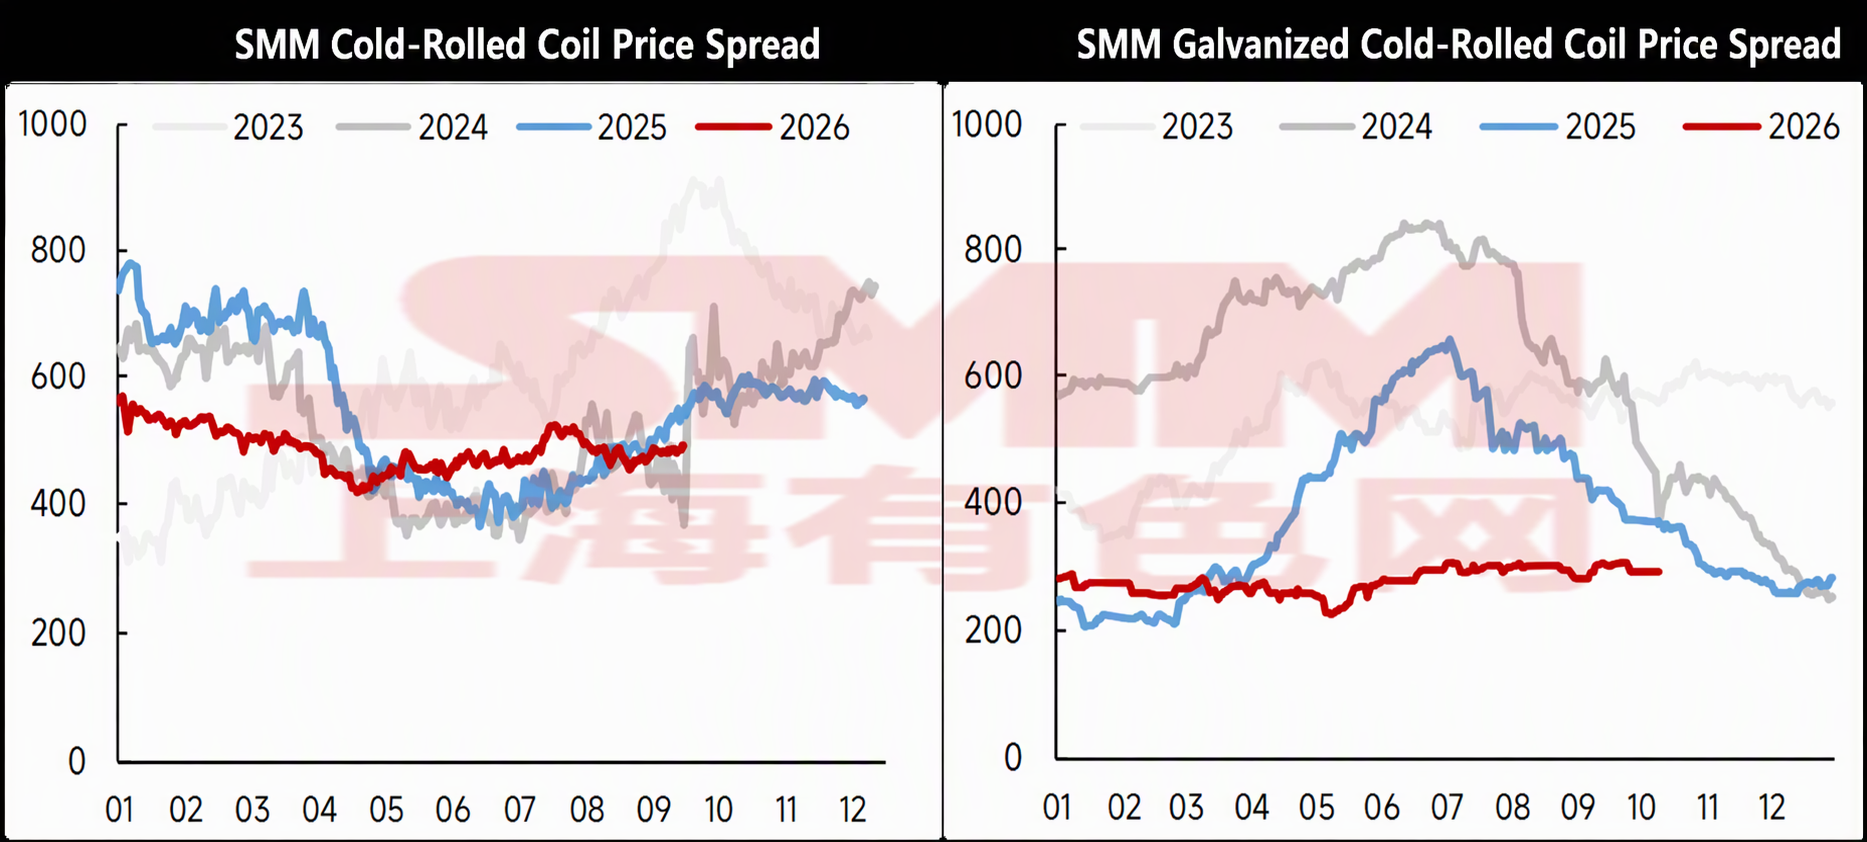
In September, the CRC-HRC price spread and GI-CRC price spread narrowed MoM. The monthly average CRC-HRC price spread narrowed from 501 yuan/mt in August to 477 yuan/mt, while the monthly average GI-CRC price spread narrowed slightly from 297 yuan/mt in August to 295 yuan/mt, basically stable. September officially entered the peak season, but peak-season demand was not prominent. Demand rebounded from the off-season but remained weak compared with the same period in previous years, leaving limited upside for prices. Meanwhile, after multiple rounds of coke price hikes, costs for sheets & plates were high, and most steel mills were operating at a loss, leaving no room for price declines. According to SMM statistics, cold-rolling profits were lower than HRC profits in September. Under pressure from weak demand and loss-making margins, cold-rolling prices basically ran stable with slight increases, and the upside for prices was narrower compared with HRC.
Looking ahead to October, October is still within the peak season but demand is mediocre. Based on steel mill order-taking and downstream demand, a sharp demand surge is unlikely in October. After the National Day holiday, there was little demand beyond essential restocking, and with high inventory accumulation, price pressure persists. Meanwhile, coke price cuts have begun, giving sheets & plates more profit room, and the price fluctuation range for sheets & plates is expected to widen. From the perspective of spot profits, current HRC profits are lower than CRC profits, and the downside for HRC prices is narrowing. From the perspective of cold-rolling vs. hot-rolling products, cold-rolling order-taking limits the upside for prices to some extent. In summary, the price spread in October is expected to have room to narrow slightly from September.
Data source statement:
(All data in this report other than public information are derived from public information (including but not limited to industry news, seminars, exhibitions, corporate financial reports, broker reports, National Bureau of Statistics data, customs import and export data, and various data published by major associations and institutions), market communication, and SMM's internal database models, and are obtained through comprehensive analysis and reasonable inference by the research team. They are for reference only and do not constitute decision-making advice.
Shanghai Metals Market reserves the right of final interpretation of this statement and the right to adjust and modify the content of the statement based on actual circumstances.