[SMM HRC Arrivals] Post-holiday arrivals increased from the holiday period

Published: Oct 13, 2026 19:06 (GMT+8)


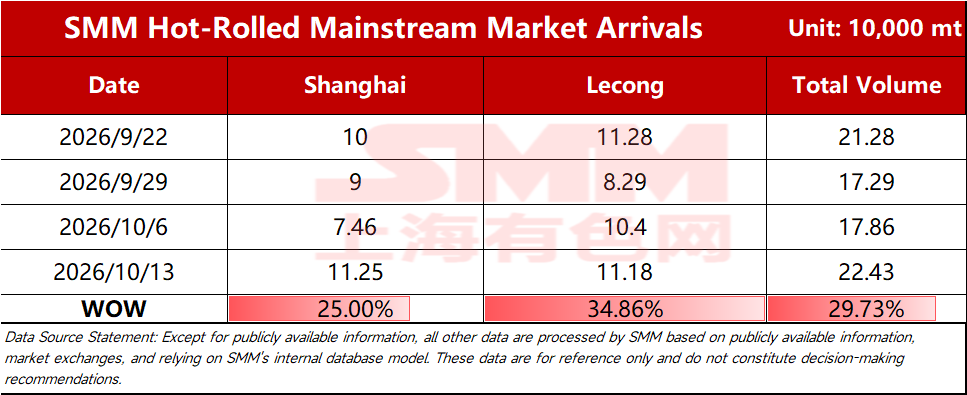
SMM Steel, October 13 – According to SMM statistics, total shipments of mainstream resources across major markets are estimated at 224,300 mt this week, up 29.73% WoW. By market:

Table 1: Arrivals Comparison Across Mainstream Markets
Source: SMM Steel

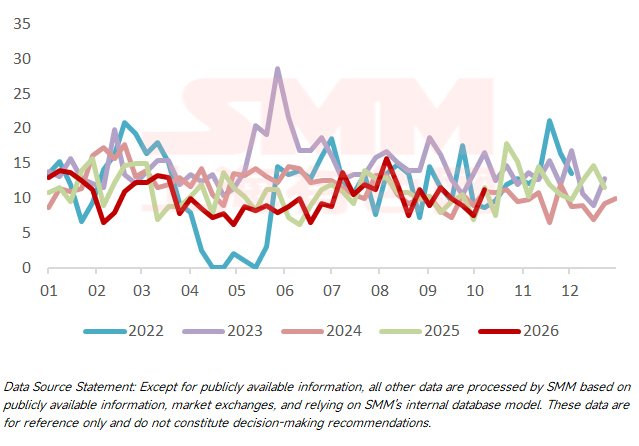
Shanghai market: HRC shipments to Shanghai increased notably this week. Specifically, arrivals of northern resources rose slightly; the main growth came from southern China resources. During the holiday, southern China resources were mostly shipped locally, resulting in lower arrivals to east China, so post-holiday arrivals recovered. Looking ahead, northern resources are expected to remain stable in the short term, while further growth from southern China resources is limited, so SMM expects arrivals to edge down in the near term.

Chart-1: Shanghai Market Arrivals
Source: SMM Steel

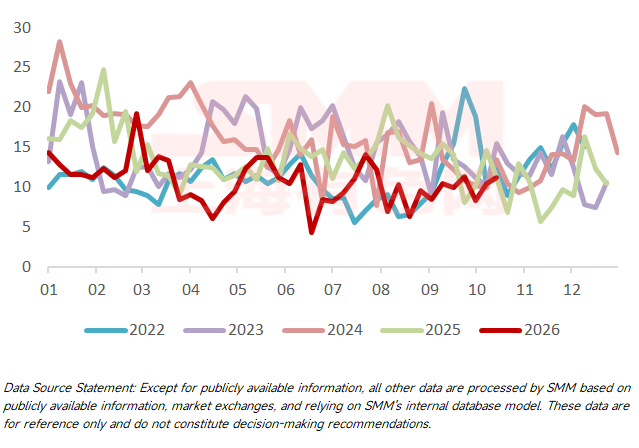
Lecong market: Shipments to Lecong increased slightly this week. Specifically, the increase was mainly driven by higher arrivals from north China ports, while shipments of local mainstream resources remained stable. Overall, total arrivals expanded modestly. Looking ahead, northern resources are expected to continue fluctuating narrowly in the short term, and local mainstream resources may shift toward specialty steel production in mid-to-late October. Arrivals to south China are expected to fluctuate narrowly in the near term.

Chart-2: Lecong Market Arrivals
Source: SMM Steel

SMM releases HRC shipment data for mainstream market destinations every Tuesday. To subscribe or access more data, please scan the QR code below. 

Data Source Statement: Except for publicly available information, all other data are processed by SMM based on publicly available information, market communication, and relying on SMM's internal database model. They are for reference only and do not constitute decision-making recommendations.

For any inquiries or for more information, please contact: lemonzhao@smm.cn
For more information on how to access our research reports, please contact:service.en@smm.cn
Related News
[SMM Analysis] Scrap Procurement Eases; EAF Operating Rate Rises 2.0% in the Period
1 hour ago
[SMM Analysis] Scrap Procurement Eases; EAF Operating Rate Rises 2.0% in the Period
Read More
[SMM Analysis] Scrap Procurement Eases; EAF Operating Rate Rises 2.0% in the Period
[SMM Analysis] Scrap Procurement Eases; EAF Operating Rate Rises 2.0% in the Period
As of October 13, the operating rate of 50 EAF (electric arc furnace) mills nationwide primarily producing construction steel stood at 37.5%, up 2.0% week-on-week. Capacity utilization came in at 38.04%, up 2.24% from the previous period, while average daily construction steel output reached 84,700 tonnes, up 5,000 tonnes from the previous period.
1 hour ago
[SMM Sheets & Plates Daily Review] Futures rose before falling, with intraday trading weak
1 hour ago
[SMM Sheets & Plates Daily Review] Futures rose before falling, with intraday trading weak
Read More
[SMM Sheets & Plates Daily Review] Futures rose before falling, with intraday trading weak
[SMM Sheets & Plates Daily Review] Futures rose before falling, with intraday trading weak
Today, HRC futures rose before falling, with the most-traded HC2701 contract closing at 3,254 yuan/mt, down 0.34% for the day. The spot market fell by 10-20 yuan/mt, with intraday trading average. From a fundamental perspective, in terms of supply, this week's HRC impact from maintenance was 193,800 mt, up 53,400 mt WoW. Next week's HRC impact from maintenance is expected at 144,900 mt, down 48,800 mt WoW. On the demand side, incremental fiscal policies for Q4 have been implemented, but their boost to end-use demand for steel remains to be verified. Looking at the latest industry chain data, the property cycle downtrend is hard to reverse, NEV sales are on a YoY downtrend, and the export tax rebate rate will be cut by another 4 percentage points starting April 1 next year. End-use demand performance is weak, so HRC destocking pressure is expected to increase, and HRC prices will continue to fluctuate weakly.
1 hour ago
[SMM Steel]
2 hours ago
[SMM Steel]
Read More
[SMM Steel]
[SMM Steel]
[Steel Billet] Today, export FOB prices for square billet held steady, with Jiangyin Port quoting USD 460–465/t. Shipment schedules for export orders are mainly concentrated in November, with a small portion extending into December. Feedback indicates that overseas buyers have been making inquiries; however, given the relatively high cost of earlier raw material procurement, some exporters are currently holding firm on their billet export quotes, making orders harder to secure.
2 hours ago
Register to Continue Reading
Gain access to the latest insights in metals and new energy
Already have an account?Sign in here