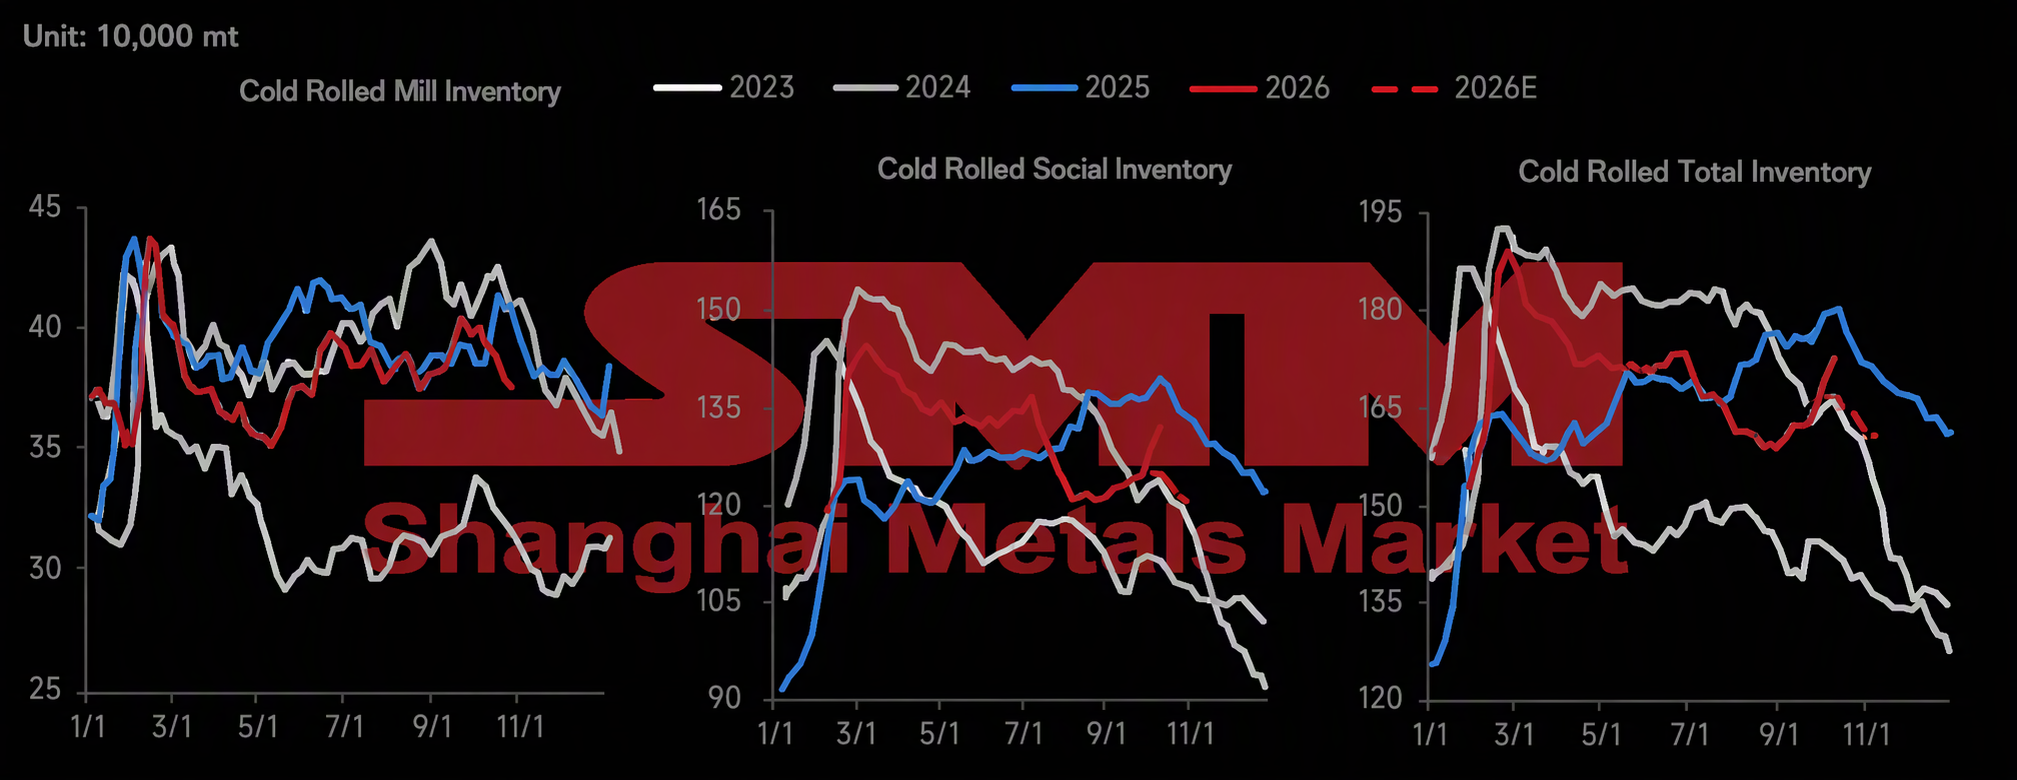
As of October 10, China's total cold-rolled inventory stood at approximately 1.72 million mt, up 140,000 mt MoM, an increase of about 9%. Breaking down the structure, China's cold-rolled social inventory was 1.3 million mt, up 100,000 mt MoM, an increase of about 8%, with the growth in in-factory inventory contributing the remainder of the total inventory rise. Comparing against historical inventory curves, current total cold-rolled inventory and social inventory levels are significantly higher than the same period in 2023 and 2024, and also sit in a relatively high range compared with the same period in 2025, highlighting mounting pressure from overall inventory volume.
Supply side, September cold-rolled production rose MoM from August, with steel mill output staying at a relatively high level and resources continuing to flow into the market, providing a supply foundation for inventory buildup. Demand side, the traditional September peak season for manufacturing did not deliver the expected strong recovery, as downstream end-use industries such as automobiles and home appliances only made just-in-time procurement, with limited order growth. Compounded by the Mid-Autumn Festival and National Day holidays, downstream enterprises held a strong wait-and-see sentiment before the holidays and did not carry out concentrated stockpiling, leaving market transactions weak. Resources flowing out of steel mills could not be quickly absorbed, and starting from end-September, cold-rolled social inventory was the first to enter an inventory buildup pace, driving total inventory higher in tandem.
Looking ahead to October cold-rolled inventory trends, the pace is expected to be a rise followed by a decline. At end-September, cold-rolled social inventory in major Chinese cities had already accumulated ahead of schedule, leaving a high inventory base. In early October, affected by the National Day holiday shutdowns and logistics slowdown, downstream procurement stalled temporarily, with social inventory extending modest gains and reaching a phased high for the period. After the holiday, as downstream enterprises resume production, market transactions are expected to gradually recover, and inventory will enter a slow destocking channel in mid-to-late October. Overall, October inventory is projected to rise first and then decline, with month-end inventory levels slightly below end-September, but still staying high on a YoY basis and unlikely to fall back to the relatively low range seen in the same period in previous years. Persistently elevated inventory pressure will weigh on market bullish sentiment, limiting the upside for cold-rolled prices.
Data source statement:
(Except for publicly available information, all other data in this report are derived from public information (including but not limited to industry news, seminars, exhibitions, corporate financial reports, broker reports, National Bureau of Statistics (NBS) data, customs import and export data, and various data published by major associations and institutions), market communication, and SMM's internal database models, and are obtained through comprehensive analysis and reasonable inference by the research team. They are for reference only and do not constitute decision-making advice.
Shanghai Metals Market reserves the right of final interpretation of this statement and the right to adjust and modify the content of the statement based on actual circumstances.