SMM, October 9: After the National Day holiday, the cobalt industry chain remained in the doldrums overall, with weak demand and lower costs jointly weighing on prices. Refined cobalt consolidated at lows, traders raised their basis, and downstream buyers continued to focus on just-in-time restocking. Cobalt sulphate offers held near 60,000 yuan/mt, but transactions were difficult, and lower raw material coefficients further weakened cost support. Cobalt chloride and Co3O4 continued to grind lower, enterprises expanded production cuts and suspensions, and new purchases remained insufficient... SMM has compiled the price changes of cobalt products in the first week after the holiday as follows:
:
After the National Day holiday, spot refined cobalt offers edged up by 500 yuan/mt and then held steady. As of October 9, spot refined cobalt offers remained stable at 255,000-270,000 yuan/mt, with an average price of 262,500 yuan/mt, up 0.19% from before the holiday.
According to SMM, after the post-holiday decline in refined cobalt futures prices, traders raised their quoted basis. Currently, almost no enterprises are offering at parity, and the minimum quoted basis is 1,000-2,000 yuan. Mainstream smelters have not adjusted prices yet, but if market prices remain at current lows, the likelihood of them lowering their offers remains high. Downstream demand remains sluggish, and enterprises are still making just-in-time restocking purchases. Overall, until various cobalt products stop falling and downstream buyers form sustained restocking, refined cobalt prices do not yet have the conditions to break out of consolidation at lows.
Cobalt salts ( and ):
:
According to SMM spot price data, spot cobalt sulphate offers fell for two consecutive trading days this week. As of October 9, spot cobalt sulphate offers dropped to 58,000-60,000 yuan/mt, with an average price of 59,000 yuan/mt, down 2.47% from September 30.
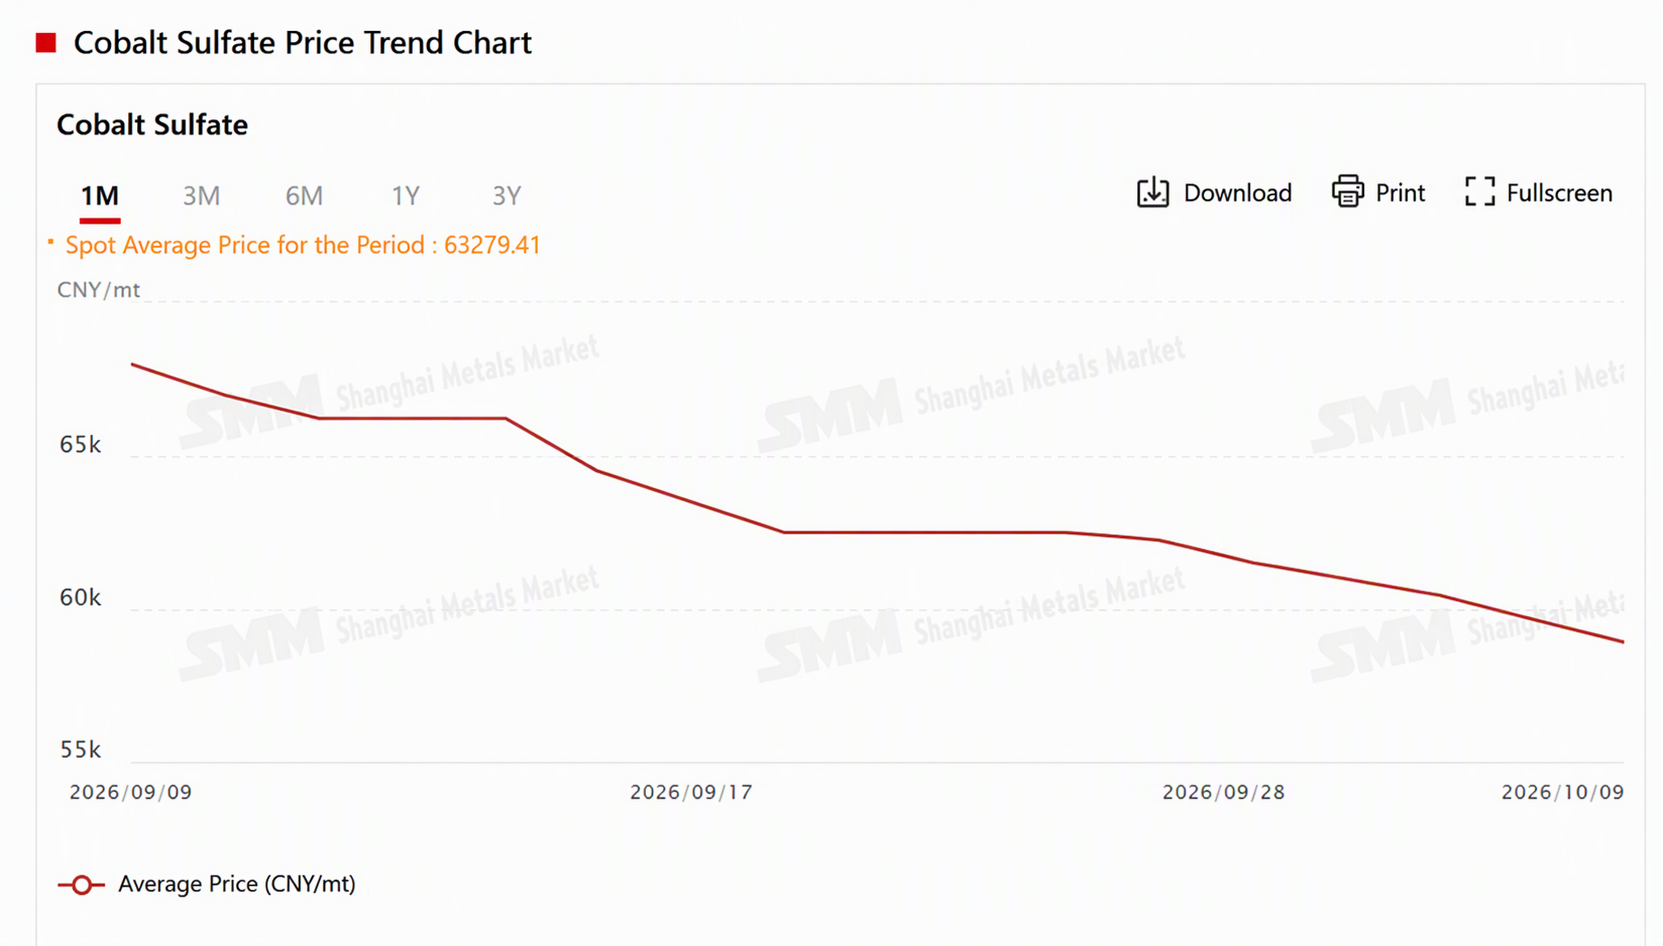
According to SMM, although mainstream enterprises maintained cobalt sulphate offers near 60,000 yuan/mt this week, actual transactions were very difficult, and downstream buyers still showed no purchasing interest. Some downstream players believe cobalt sulphate prices will fall below 50,000 yuan/mt in the future. Under the influence of bearish sentiment, only a few enterprises made just-in-time purchases. Although there were no new transactions for MHP cobalt coefficients and recycled cobalt coefficients, the overall trend remained downward, and cost support continued to weaken, opening up new room for smelters to lower prices and sell. Before there is a substantive improvement on the demand side, the cycle of "price cuts—losses—raw material pressure—cost declines—further price cuts" is expected to continue dominating the direction of the cobalt sulphate market.
:
According to SMM spot quotes, after the National Day holiday, spot cobalt chloride quotes continued the pre-holiday decline. After falling for two trading days, spot cobalt chloride quotes dropped to 67,500-69,500 yuan/mt, with an average price of 68,500 yuan/mt, down 3.52% from pre-holiday levels.
In terms of actual transactions, according to SMM, only a very small number of spot orders have been concluded after the holiday, with existing shipments mostly concentrated in internal self-supply within integrated enterprises for their own Co3O4 production. Non-integrated enterprises have found it difficult to secure spot transactions. On the supply side, demand has yet to improve, and the industry remains in a destocking phase. Cobalt chloride production in September pulled back significantly MoM, with production cuts becoming the main way for producers to relieve inventory pressure. Enterprises that had planned to resume production before the holiday have turned to a wait-and-see stance due to persistently weak downstream demand, and the scope of production suspensions is still expanding. On the demand side, downstream Co3O4 production cuts have continued to widen, further shrinking procurement demand for raw materials. During the National Day holiday, market trading was largely stagnant. After the holiday, sporadic inquiries increased but transactions remained sluggish, with limited room for price fluctuations. Industry participants generally shifted their focus to whether demand would see a substantive recovery after the holiday. Overall, cobalt chloride prices are expected to remain on a narrow downward trend in the short term.
:
According to SMM spot quotes, spot Co3O4 quotes this week also failed to escape the downward trend. According to SMM spot quotes, as of October 9, spot Co3O4 quotes fell to 217,500-232,500 yuan/mt, with an average price of 225,000 yuan/mt, down 5.26% from September 30 before the holiday.
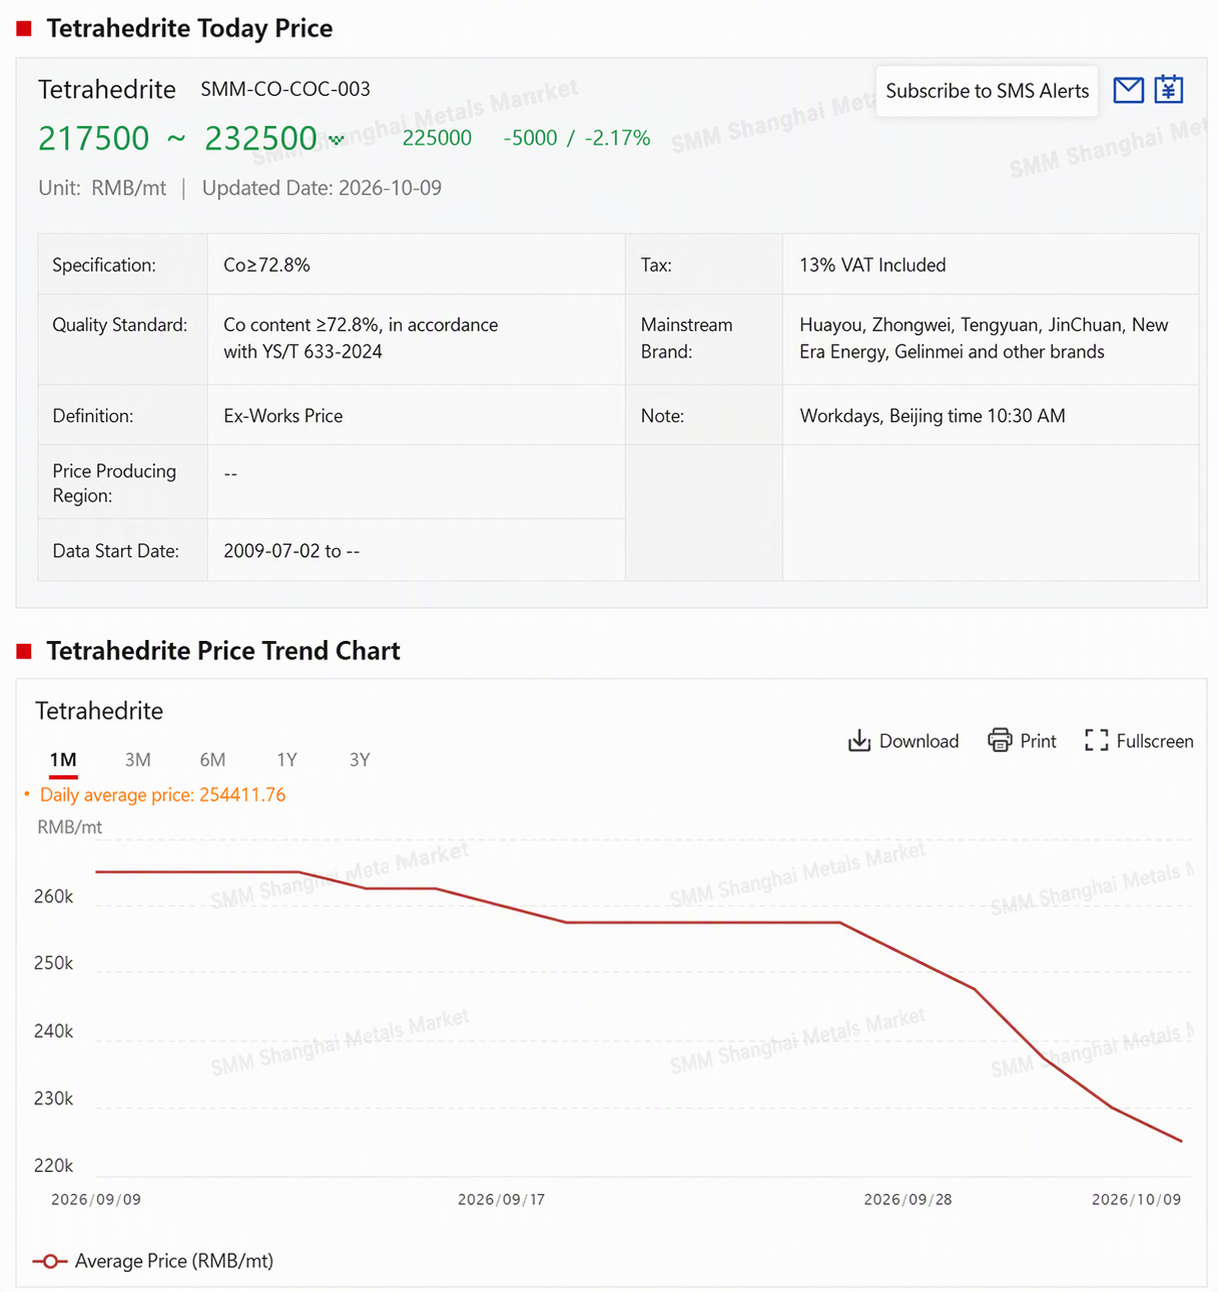
According to SMM, this round of declines stemmed partly from some enterprises actively offering low prices to boost performance, and partly from mutual reinforcement with pessimistic expectations amid the overall grinding lower sentiment. On the supply side, affected by persistently weak downstream demand, multiple enterprises remain in a state of production cuts. On the demand side, existing shipments are mainly for delivering earlier long-term contracts and undertaking processing business, with new procurement nearly absent. The market had already entered a consolidation phase before the holiday, and transactions have not shown a clear recovery after the holiday. The price center is still slowly moving lower, with limited room for further adjustment in the short term, and market focus has shifted to demand realization after the holiday ends. Overall, Co3O4 prices are expected to remain on a narrow downward trend in the short term.
In news, on October 9, the European Commission announced on Friday that it has selected 46 strategic raw material projects that will receive expedited approvals and support in accessing public and private funding. Progress on the projects selected last year has been slow, with some facing difficulties in implementation. The European Commission stated it had mobilized over €2 billion (approximately $2.24 billion) in public funding, but project developers warned in August that without urgent capital injections, more projects could be at risk of failure. The Commission aims to prioritize these projects to help the EU achieve the targets set by the 2024 Critical Raw Materials Act, which stipulates that by 2030, the EU must domestically source 10% of its annual demand for critical raw materials through mining, 40% through processing, and 25% through recycling. These projects are distributed across 16 EU member states, covering 15 of the 17 raw materials listed in the EU’s Strategic Raw Materials List, including copper, lithium, nickel, cobalt, manganese, graphite, rare earths, magnesium, and tungsten. The Commission noted, "These 46 new projects are expected to require approximately €21.1 billion (around $237 billion) in capital investment, with funding to be raised through public and private channels."
Additionally, according to Xinhua News Agency, Indonesian President Prabowo presided over the launch ceremony of 11 Chinese-funded downstream mining projects in the Weda Bay Industrial Park in Central Halmahera Regency, North Maluku Province, on the 8th. These projects involve a total investment of about $10.2 billion, spanning sectors such as power batteries, nickel-cobalt materials, aluminum, new energy construction machinery, and commercial vehicle manufacturing.