Overseas Primary Aluminum Premiums Near a Floor as Selling Pressure Eases [SMM Analysis]

Published: Oct 09, 2026 14:49 (GMT+8)

Overseas primary aluminum premiums remained weak this week, but the pace of decline slowed across several Asian markets. Downstream demand has not shown a clear improvement, although current premium levels are beginning to approach ranges where sellers are less willing to make further concessions.

I. Review of Spot Premiums by Region

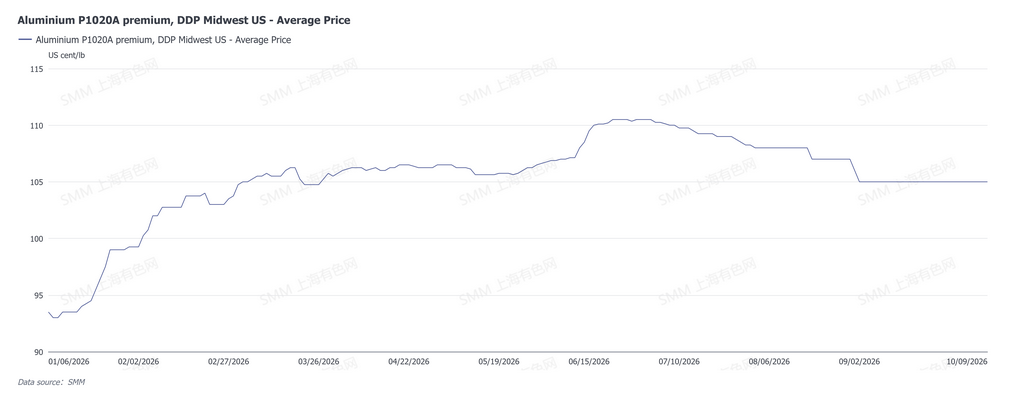
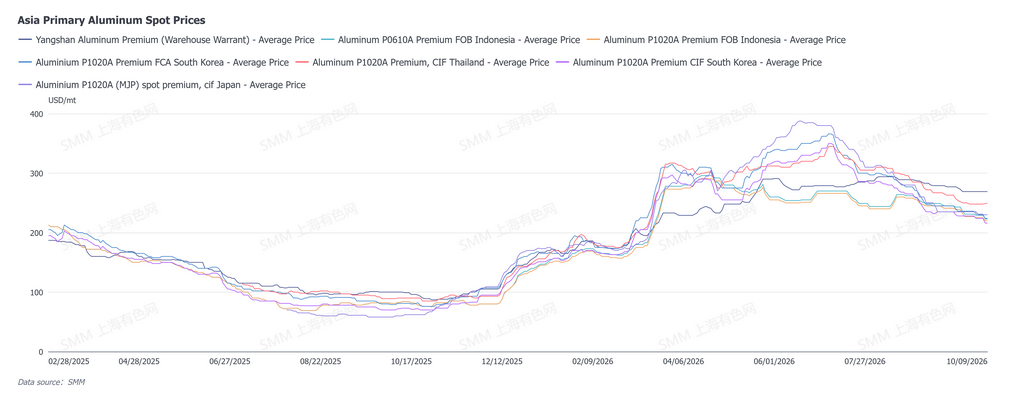
As of October 9, the CIF Thailand P1020A premium stood at USD 249/mt, FCA South Korea at USD 223/mt, CIF South Korea at USD 216/mt, and CIF Japan MJP spot at USD 230/mt. The Japan warehouse-warrant premium was USD 269/mt, while the US Midwest DDP premium remained at 105 US cents/lb.

Across Asia, premiums remained under pressure, although the pace of decline was less pronounced than in previous weeks. Demand was still subdued, but sellers in several markets showed less willingness to make further sizeable concessions, suggesting that prices may be moving closer to a short-term floor.
 

Southeast Asia

Thailand: Downward Momentum Slows

Thailand remained quiet this week, with downstream consumers continuing to purchase mainly for immediate production needs.

The main change was on the offer side. After several weeks of declining premiums, sellers showed less willingness to make further sizeable reductions. With the CIF Thailand premium at USD 249/mt, the market appears to be moving closer to a level where additional downside becomes more limited.

Demand itself has not strengthened, so a sharp rebound is unlikely in the near term. However, the market could gradually stabilize if buying interest improves from current levels.

South Korea: Seller Competitions Begins to Ease

The South Korean market continued to face relatively comfortable supply, while downstream purchasing remained selective.

Earlier weakness was largely driven by sellers competing for limited demand. This pressure has started to moderate as premiums move lower, with the FCA South Korea premium at USD 223/mt and the CIF premium at USD 216/mt.

Buyers are still seeking lower prices, but sellers have become less responsive to aggressive bids. This has helped slow the decline and may allow premiums to move within a narrower range in the near term.

Japan

CIF Japan MJP Primary Aluminum Spot

Japan’s spot MJP market remained slow this week, with limited transactions and no clear improvement in downstream demand.

As of October 9, the CIF Japan MJP spot premium stood at USD 230/mt, while the warehouse-warrant premium was USD 269/mt.

Market attention is increasingly shifting toward where Q4 values may find support. Current market discussions are centered around approximately USD 255/mt as an indicative Q4 offer level. Some recent transactions have also been reported around this level; however, transaction volumes remain limited and are not yet representative of the broader market.

This does not reflect stronger demand. Rather, current price levels are moving closer to a range where sellers are less willing to offer further discounts. If this continues, spot MJP could begin to stabilize even before downstream demand shows a visible recovery.

United States

US Midwest DDP Premium Holds Steady

The US Midwest DDP premium remained at 105 US cents/lb this week.

Trading conditions changed little, with no significant shift in either downstream demand or supply availability. Compared with Asian markets, where premiums are still finding a floor, the Midwest market has remained relatively stable.

Without a major change in regional fundamentals, the premium is expected to stay broadly steady in the near term.

Market Outlook

The outlook for overseas primary aluminum premiums has become less bearish.

Downstream demand remains subdued, but premiums have already moved to relatively low levels, making further reductions less attractive for sellers. This change in offer behavior may provide support for several Asian markets in the coming weeks.

In the near term, premiums may stabilize or recover modestly from current levels. A stronger rebound, however, would still require a clearer improvement in downstream orders and restocking demand.

Data Source Statement: Except for publicly available information, all other data are processed by SMM based on publicly available information, market communication, and relying on SMM's internal database model. They are for reference only and do not constitute decision-making recommendations.

For any inquiries or for more information, please contact: lemonzhao@smm.cn
For more information on how to access our research reports, please contact:service.en@smm.cn
Related News
Data: SHFE, DCE market movement (Oct 09)
9 mins ago
Data: SHFE, DCE market movement (Oct 09)
Read More
Data: SHFE, DCE market movement (Oct 09)
The following table shows the ferrous and nonferrous metals movement on the SHFE and DCE on 09 Oct , 2026
9 mins ago
Greenland Mines Increases Stake in AnorTech, Boosting US Alumina Supply Chain Independence
1 hour ago
Greenland Mines Increases Stake in AnorTech, Boosting US Alumina Supply Chain Independence
Read More
Greenland Mines Increases Stake in AnorTech, Boosting US Alumina Supply Chain Independence
Listed enterprise Greenland Mines announced that it has fully exercised its option to acquire an additional 9.9% stake in Canadian anorthosite producer AnorTech, increasing its shareholding to 19.9%. AnorTech owns the Gronne Bjerg project in Greenland and holds a proprietary, patent-pending process that can produce sustainable smelter-grade alumina and high-purity alumina from anorthosite without generating bauxite residue tailings; the process also yields multiple saleable by-products, including amorphous silica, calcium silicate, CO2-free refractory cement, 3D-printable cement, and alumina-based catalysts. Greenland believes the Gronne Bjerg project has the potential to become a raw material source for US smelter-grade alumina and high-purity alumina production, while US net imports in 2025 are estimated to have met approximately 71% of its alumina consumption. Greenland President Bo Møller Stensgaard stated that the company aims to establish a supply chain from Greenland to the US that can operate independently of Chinese refining, enabling more processing, manufacturing, and value creation in the US. This increased stake further expands its "North Atlantic Critical Metals Corridor" footprint, providing a potential alternative source for the US alumina supply chain and supporting US industrial self-sufficiency goals.
1 hour ago
Sichuan Jiuda Aluminum's $400M High-Tech Battery Materials Project Breaks Ground in Guangyuan
1 hour ago
Sichuan Jiuda Aluminum's $400M High-Tech Battery Materials Project Breaks Ground in Guangyuan
Read More
Sichuan Jiuda Aluminum's $400M High-Tech Battery Materials Project Breaks Ground in Guangyuan
Recently, the high-tech battery materials project with an annual capacity of 50,000 mt, invested by Sichuan Jiuda Aluminum Co., Ltd. and constructed by Gongyi Xingrui Construction Engineering Co., Ltd., officially broke ground in the Yuanjiaba Aluminum Industrial Park of Guangyuan Economic and Technological Development Zone. The project has a total investment of 400 million yuan and is being built on the enterprise's own industrial land, covering an area of 25,073.89 m² (including 7,873.89 m² of the original No. 1 plant and 17,200 m² of newly applied land). The construction scope includes: building production facilities in the planned No. 1 plant on the west side (Class E, 1F, H=15m) and the new plant area, installing five high-precision battery aluminum foil production lines (each with an annual capacity of 10,000 mt of high-precision battery aluminum foil), while also forming an annual capacity of 6,000 mt of aluminum-copper composite plates and 2,400 mt of aluminum-copper composite foil, along with supporting auxiliary production facilities such as slitting, precision cutting, and annealing, as well as utility facilities including quality inspection, circulating water systems, and air compressor stations. The project is planned to be completed and put into operation in October 2026. Once reaching full production, it is expected to achieve an annual output value of 1.3 billion yuan, contribute 90.328 million yuan in taxes, and create employment for over 90 people. After completion and commissioning, the project will further improve the layout of the lithium battery new materials industry chain, enhance regional new energy industry capacity, and support the high-quality development of local green industries.
1 hour ago