SMM, October 9:
In the metals market:
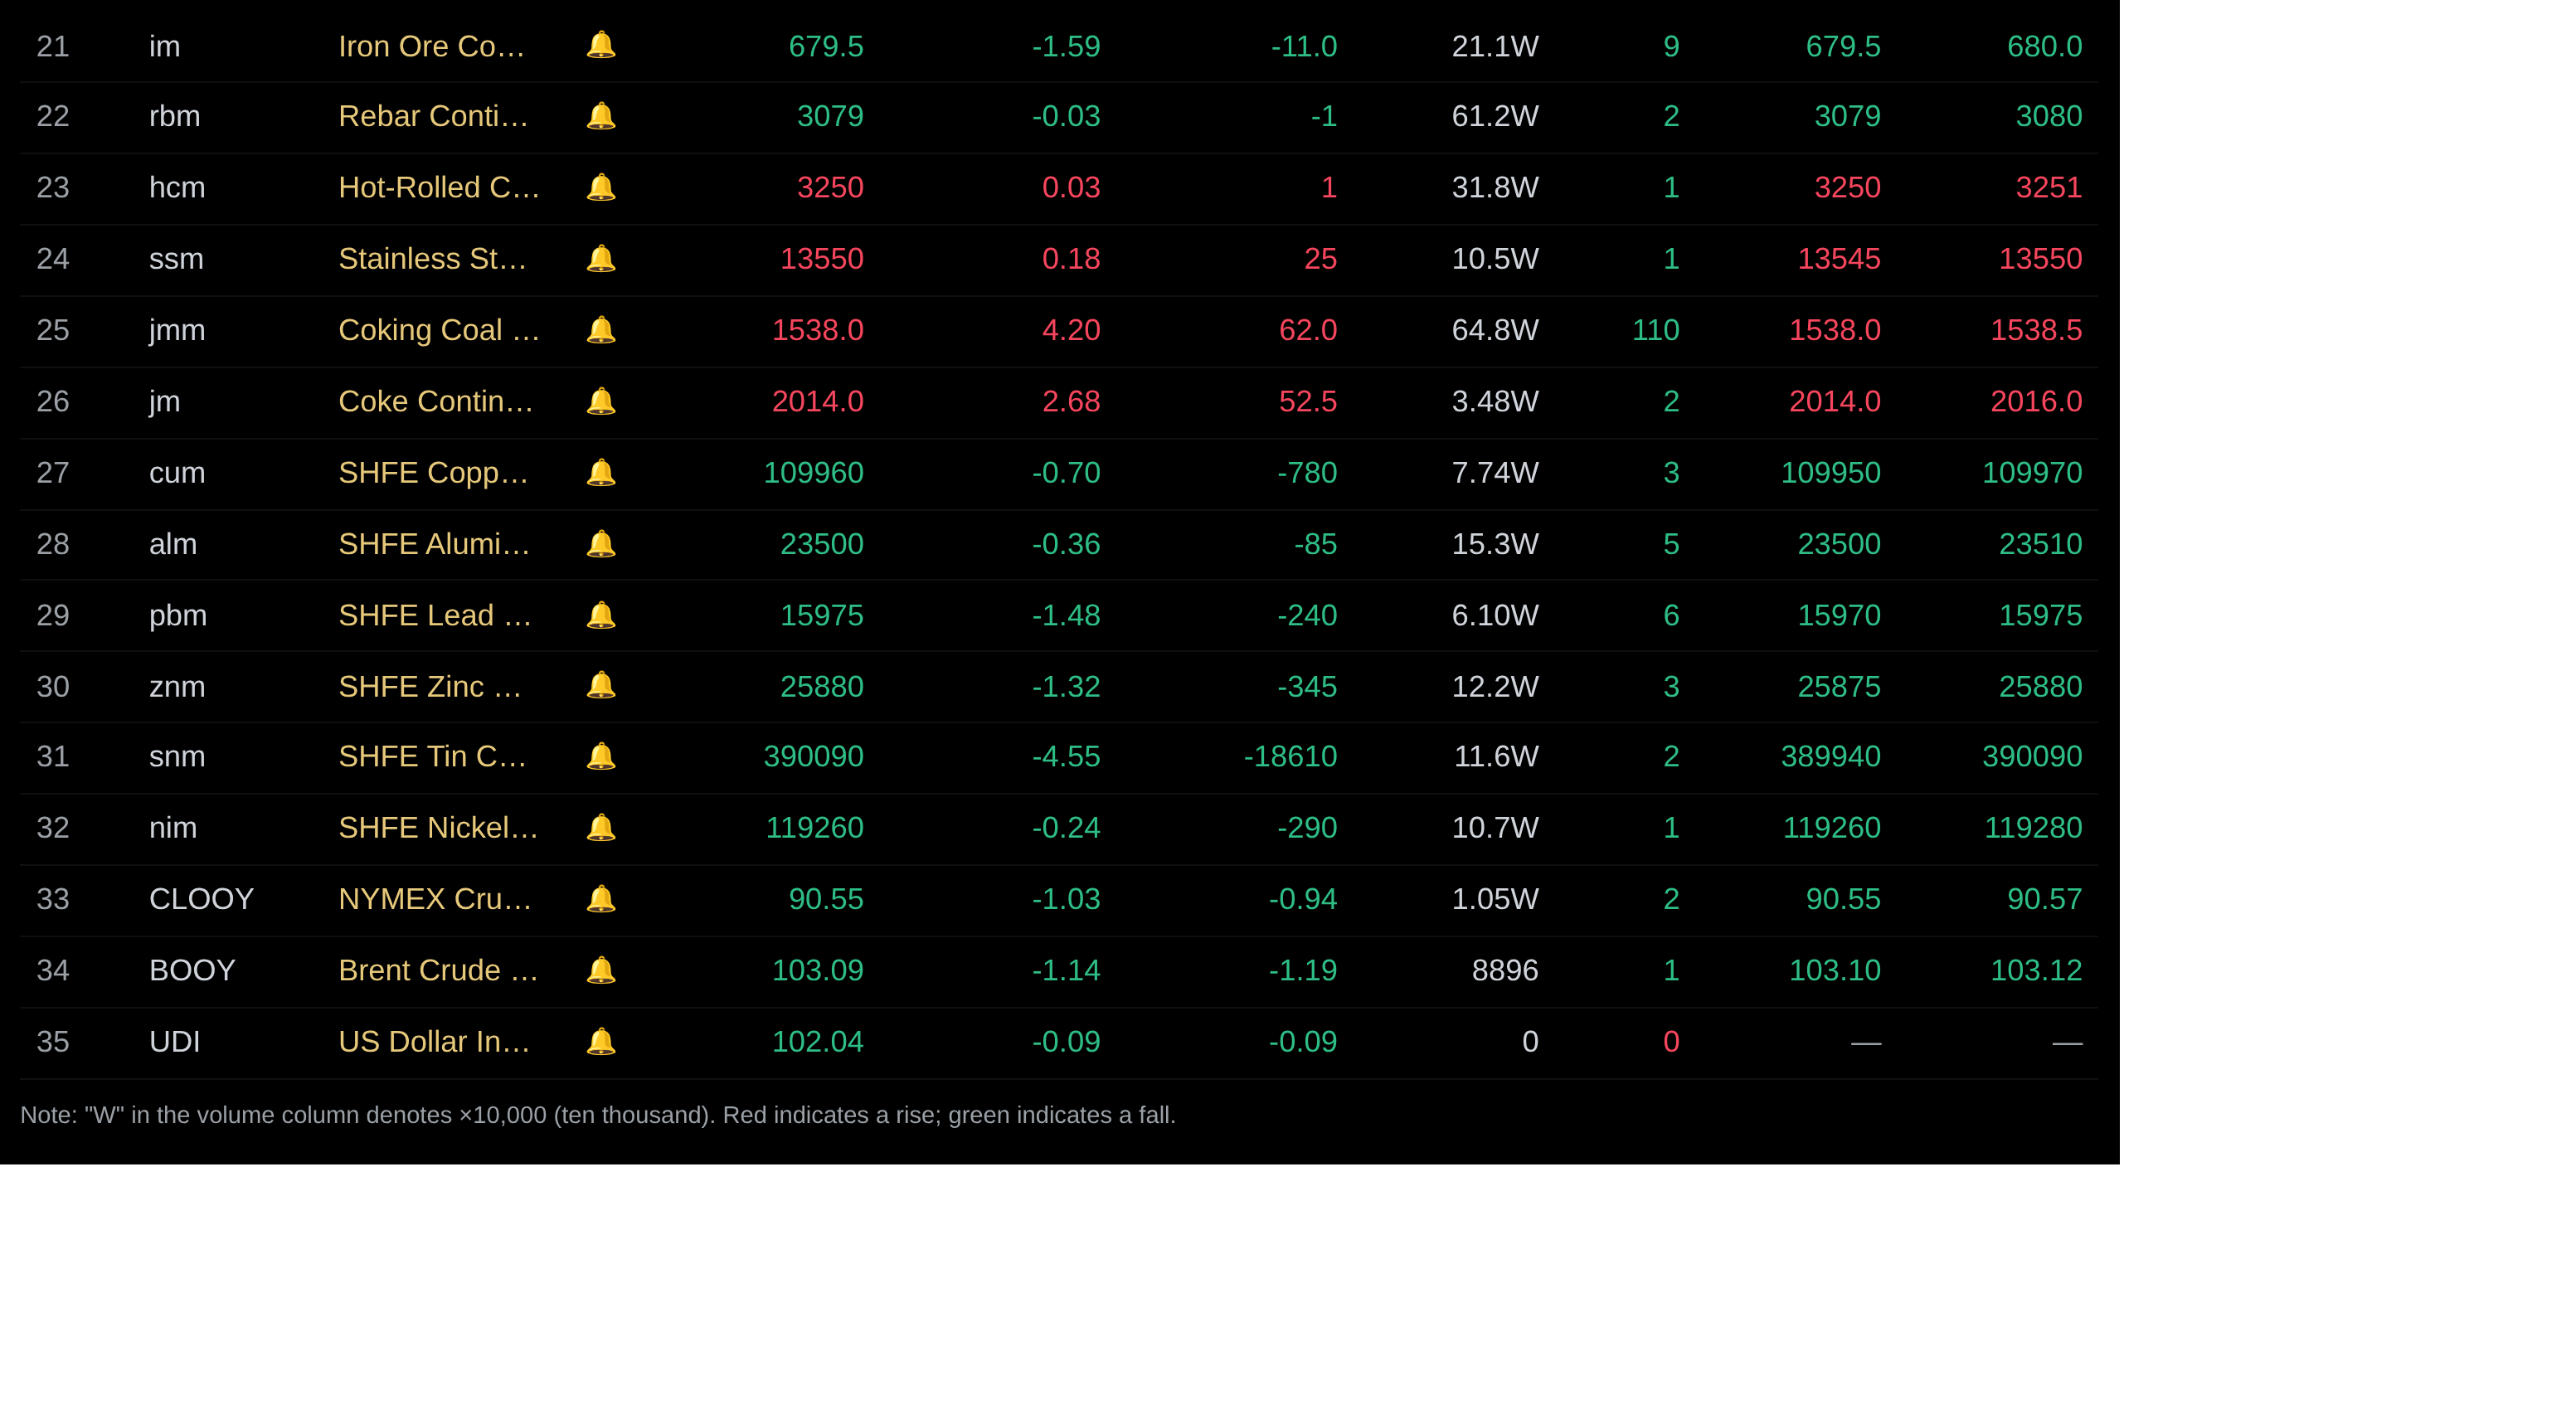
As of the midday close, base metals in the domestic market fell across the board. SHFE copper fell 0.7%, SHFE aluminum fell 0.36%. SHFE lead fell 1.48%. SHFE zinc fell 1.32%. SHFE tin fell 4.55%, and SHFE nickel fell 0.24%.
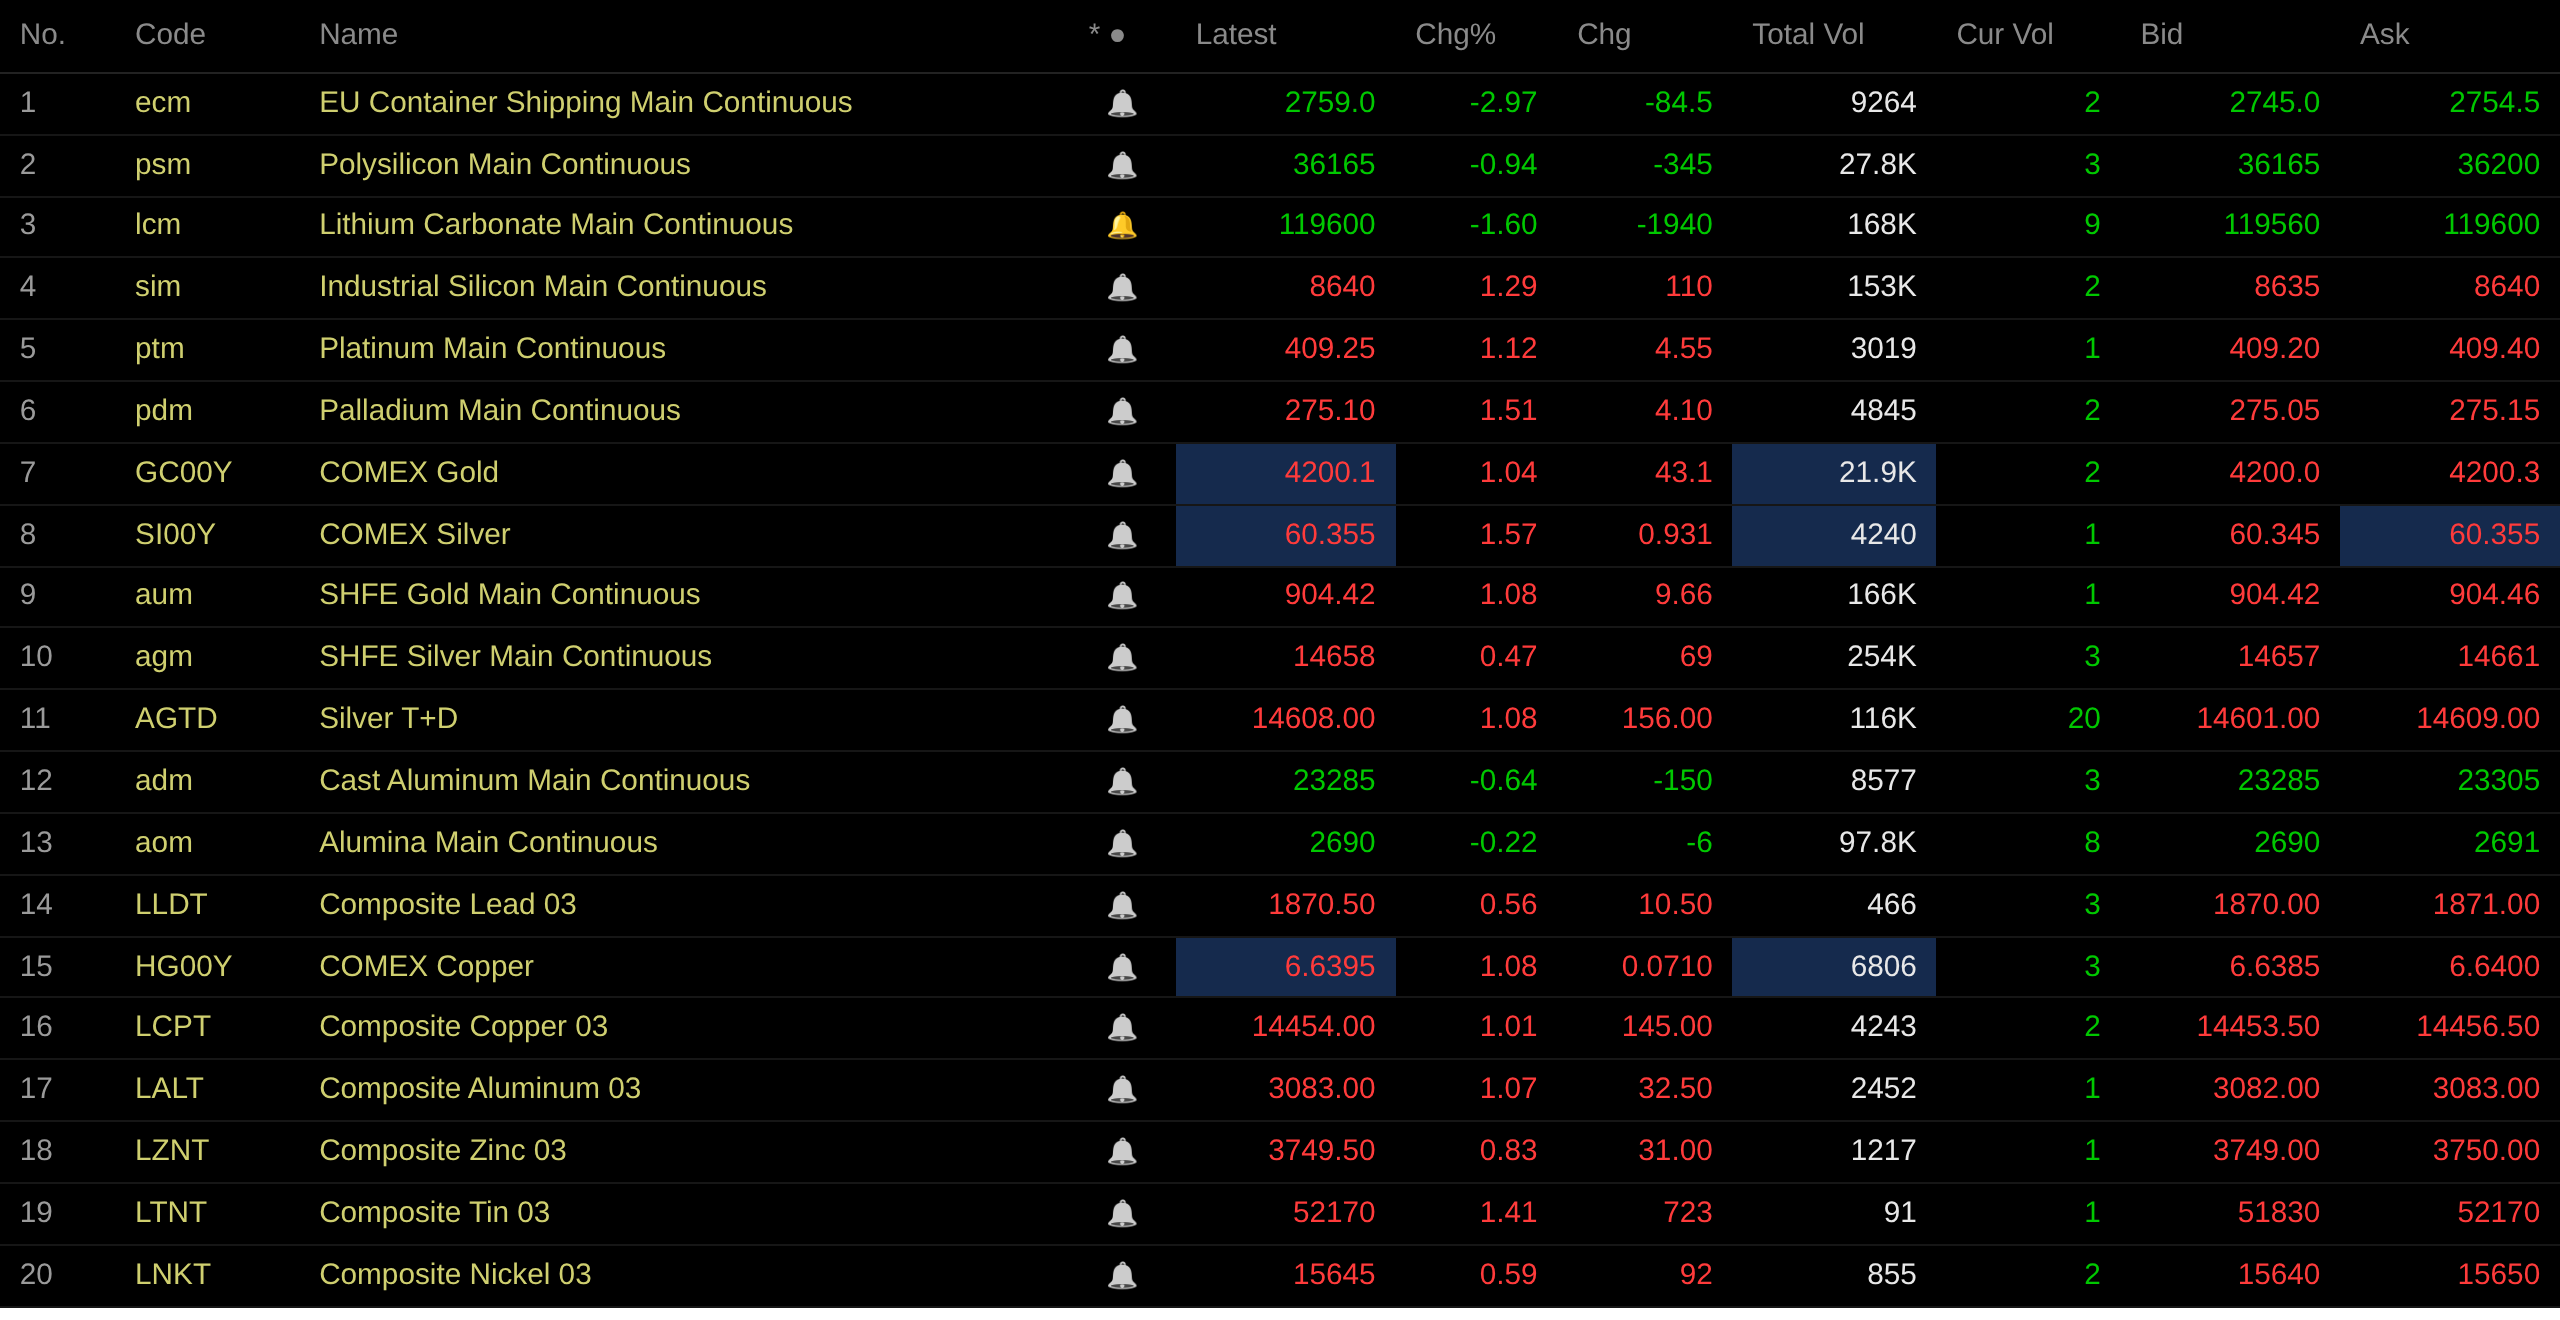
In addition, the most-traded foundry aluminum futures contract fell 0.64%, and the most-traded alumina contract fell 0.22%. The most-traded lithium carbonate contract fell 1.6%. The most-traded silicon metal contract rose 1.29%. The most-traded polysilicon futures contract fell 0.94%.
Ferrous metals mostly rose. Iron ore fell 1.59%, and rebar edged down. Hot-rolled coil edged up 0.03%. Stainless steel rose 0.18%. In coking coal and coke: the most-traded coking coal contract rose 4.2%, and the most-traded coke contract rose 2.68%.
In overseas base metals, as of 11:46, LME metals rose across the board. LME copper rose 1.01%, and LME aluminum rose 1.07%. LME lead rose 0.56%, and LME zinc rose 0.83%. LME tin rose 1.41%. LME nickel rose 0.59%.
In precious metals, as of 11:46, COMEX gold rose 1.04%, and COMEX silver rose 1.57%. In domestic precious metals: SHFE gold rose 1.08%, and the most-traded SHFE silver contract rose 0.47%.
In addition, as of the midday close, the most-traded platinum futures contract rose 1.12%, and the most-traded palladium futures contract rose 1.57%.
As of the midday close, the most-traded European shipping futures contract fell 2.97% to 2,759 points.
As of 11:46 on October 9, midday quotes for some futures:
Spot and fundamentals
Copper: Today, spot Guangdong #1 copper cathode against the front-month contract: high-quality copper was quoted at a premium of 600 yuan/mt, up 300 yuan/mt from the previous trading day; standard-quality copper was quoted at a premium of 300 yuan/mt, up 200 yuan/mt from the previous trading day; SX-EW copper was quoted at a premium of 240 yuan/mt, up 200 yuan/mt from the previous trading day. The average price of Guangdong #1 copper cathode was 111,200 yuan/mt, down 690 yuan/mt from the previous trading day, and the average price of SX-EW copper was 110,990 yuan/mt, down 690 yuan/mt from the previous trading day. Spot market: Guangdong inventory declined again today, mainly due to reduced arrivals and increased warehouse withdrawals, as downstream copper processing enterprises resumed production, boosting demand...
Macro front
Domestic:
[Guangxi Beibu Gulf Port sets a new record for single-voyage roll-on/roll-off vehicle exports] On October 8, the vessel "Changrongkou," loaded with 2,727 Chinese vehicles, departed from the Qinzhou port area of Guangxi Beibu Gulf Port, heading for Duqm Port in Oman, setting a new record for single-voyage roll-on/roll-off vehicle exports at Beibu Gulf Port. Duqm Port is located in southeastern Oman. This voyage travels directly from Qinzhou to the Middle East without any stopovers, taking about 15 days to arrive, opening an efficient new go-global channel for Chinese automakers to expand into the Middle East market. In recent years, as the shipping route network has continued to improve and the multimodal logistics system of sea-rail intermodal transport and road freight has been continuously optimized, the roll-on/roll-off business of Beibu Gulf Port has steadily expanded its reach. Data shows that since the launch of Beibu Gulf Port's roll-on/roll-off business, a total of 10 voyages had been completed as of September this year, exporting more than 11,000 complete vehicles and construction machinery units. (CCTV News)
[PBOC reverse repo operations resulted in a net drain of 604 billion yuan on the day]The PBOC conducted 2 billion yuan of 7-day reverse repo operations today. With 606 billion yuan of overnight reverse repos maturing today, the day saw a net drain of 604 billion yuan. This week, the PBOC conducted a total of 2 billion yuan of 7-day reverse repo operations, 606 billion yuan of overnight reverse repo operations, and 1,200 billion yuan of outright reverse repo operations. With a total of 1,439.5 billion yuan of overnight reverse repos, 281 billion yuan of 7-day reverse repos, and 100 billion yuan of 14-day reverse repos maturing this week, the week saw a net drain of 12.5 billion yuan. (Jin10 Data APP)
US dollar:
As of 11:46, the US dollar index fell 0.09% to 102.04.
On Friday morning, most Asian currencies held steady against the US dollar ahead of US economic data releases. UOB Global Economics and Markets Research noted that the market is watching a series of data, including the University of Michigan preliminary consumer sentiment index. The institution added that the market will closely monitor this data to gauge US household confidence, inflation expectations, and the resilience of consumer spending. UOB wrote in a report that after this week's sharp rise in long-term US Treasury yields, investors will continue to watch developments in the US Treasury market while also paying attention to further remarks from Fed officials to assess the monetary policy outlook. (Jin10 Data APP)
Data released by the US Department of Labor on Thursday showed that for the week ending October 3, initial jobless claims in the US fell by 2,000 WoW to a seasonally adjusted 197,000, below market expectations of 200,000, and remained near a 57-year low for the fourth consecutive week. Meanwhile, the September nonfarm payrolls released last Friday increased by only 29,000, far below market expectations, indicating a clear cooling in hiring demand.
In addition, the International Monetary Fund (IMF) schedule shows that Fed Chairman Warsh will attend the IMF Annual Meetings in Bangkok and deliver a speech at 11:30 am Beijing time on October 16. That day was also the last day before Fed officials entered the quiet period ahead of the FOMC meeting on October 27–28. Markets currently bet that the US Fed will pause rate hikes at the October meeting (probability around 80%) and then hike in December. (Jin10 Data APP)
According to CME "FedWatch": the probability that the US Fed will keep rates unchanged through October is 82.3%, and the probability of a cumulative 25 basis point hike is 17.7%. The probability that the US Fed will keep rates unchanged through December is 18.7%, the probability of a cumulative 25 basis point hike is 67.6%, and the probability of a cumulative 50 basis point hike is 13.7%. (Jin10 Data APP)
Fed Governor Waller said on Thursday that further rate hikes may still be needed to bring inflation back to the US Fed's 2% target, but he stressed that the pace of hikes has some "flexibility" and left room for the US Fed to pause at the upcoming October policy meeting. Waller said: "If economic data continue to meet expectations, I expect further rate hikes will be needed to bring inflation back to the 2% target more quickly." "But there is some flexibility in when those hikes are implemented. We do not have to hike at consecutive meetings, but we should complete the necessary hikes within a reasonable time frame." Waller did not specify how much further the policy rate ultimately needs to rise to curb inflation that is still more than 1 percentage point above the US Fed's target. However, he said that as the US economy strengthens, the energy price shock triggered by the war in Iran has yet to fade, and AI infrastructure construction is driving demand growth for key goods and services and further intensifying inflationary pressure, the need to raise rates has become increasingly clear.
St. Louis Fed President Musalem said the US Fed needs to hike rates again to push inflation back to the 2% target. He said that to achieve the inflation target within a "timely" period, monetary policy needs to be tightened further. Musalem said that if "timely" means about 18 months, then rates may need to be raised further at appropriate times over the next 6 to 9 months. He said inflation remains the main problem facing the US economy, but with strong growth and a stable labour market, the US Fed may be able to bring inflation down without significantly hurting employment. Asked whether the October 27–28 FOMC meeting should hike rates, Musalem said he remains open-minded and has not prejudged the meeting outcome, but the inflation situation requires policymakers to continue considering further tightening. Musalem said that despite the notable rise in US Treasury yields, financial conditions remain loose and supportive of economic growth. He said the rise in yields does not mean investors are losing confidence in the US Fed, but rather reflects market expectations that real interest rates will climb and that competition for capital is intensifying in a strong economic environment. (Jin10 Data App)
On the data front:
Today will bring the release of China's September M2 money supply YoY (TBD), the preliminary US October one-year inflation expectations, the preliminary US October University of Michigan consumer sentiment index, Switzerland's September consumer confidence index, and Canada's September employment change. In addition, 2028 FOMC voting member and St. Louis Fed President Musalem will deliver remarks.
In other currencies:
Japanese Prime Minister Takaichi Sanae said on Friday that the Japanese government will continue to closely monitor exchange rate and price trends and take appropriate countermeasures. Takaichi Sanae made the remarks in the Diet in response to questions from an opposition lawmaker about Japan's economic policies and the potential impact of yen depreciation. She also said the government will take into account various factors affecting the economy, including changes in interest rates and the yen exchange rate, when formulating fiscal policy. Takaichi Sanae has long advocated loose fiscal and monetary policies, but is now facing market pressure to adjust her policy direction. (Jin10 Data App)
In crude oil:
As of 11:46, oil prices fell in both markets, with WTI crude down 1.03% and Brent crude down 1.14%. Easing market concerns over Middle East supply have put oil prices under pressure, though the impact of Hurricane Isaias on capacity in the Gulf of Mexico region is also supporting oil prices.
On October 8 local time, US President Trump said the US and Iran are engaged in productive consultations and that the US will not attack Iran before the November 3 midterm elections. (CCTV)
The US Bureau of Ocean Energy Management said that as of Wednesday morning local time, approximately 511,619 barrels per day of crude oil capacity in the Gulf of Mexico region had been shut in, accounting for 25.08% of current production in the area. Personnel have been evacuated from 8 production platforms and 2 drilling rigs, and one additional drilling rig has been moved out of the storm's path. In addition, 16.37% of natural gas production in the region has also been shut in. The US National Hurricane Center said Isaias strengthened into a hurricane on Wednesday evening and is expected to approach the northern Gulf Coast of the US on Friday. (Jin10 Data App)
CITIC Securities said in a research note that US-Iran negotiations have yet to achieve a major breakthrough, safety incidents involving oil tankers in the Strait of Hormuz have increased, transportation costs have climbed, and combined with escalating conflict between Saudi Arabia and the Houthis, risks to regional energy facilities and shipping through the Bab el-Mandeb Strait have risen, with uncertainty over crude oil supply and transportation continuing to increase. International oil prices are expected to continue to consolidate at highs for the remainder of 2026, with close attention on negotiation progress, the resumption of strait shipping, and actual supply changes.
Spot market overview:
►
►
►
►
►
►
►
►
►
►
►
►
►
►