On October 2, South Korean research firm SNE Research released its latest installation data. From January to August 2026, global power battery installations totaled 844.2 GWh, up 19.7% YoY. In August alone, installations reached 116.8 GWh, up 14.3% YoY, slower than July's 23.3% growth.
Among the top 10 companies, seven Chinese firms held a combined 73.3% market share, up 3.6 percentage points YoY.
What is evident is that the global power battery market continues to expand, with Chinese battery producers steadily growing their market share and further consolidating their leading positions. Meanwhile, the combined market share of Japanese and South Korean companies continues to be squeezed, with competitive dominance increasingly concentrated in the Chinese camp.
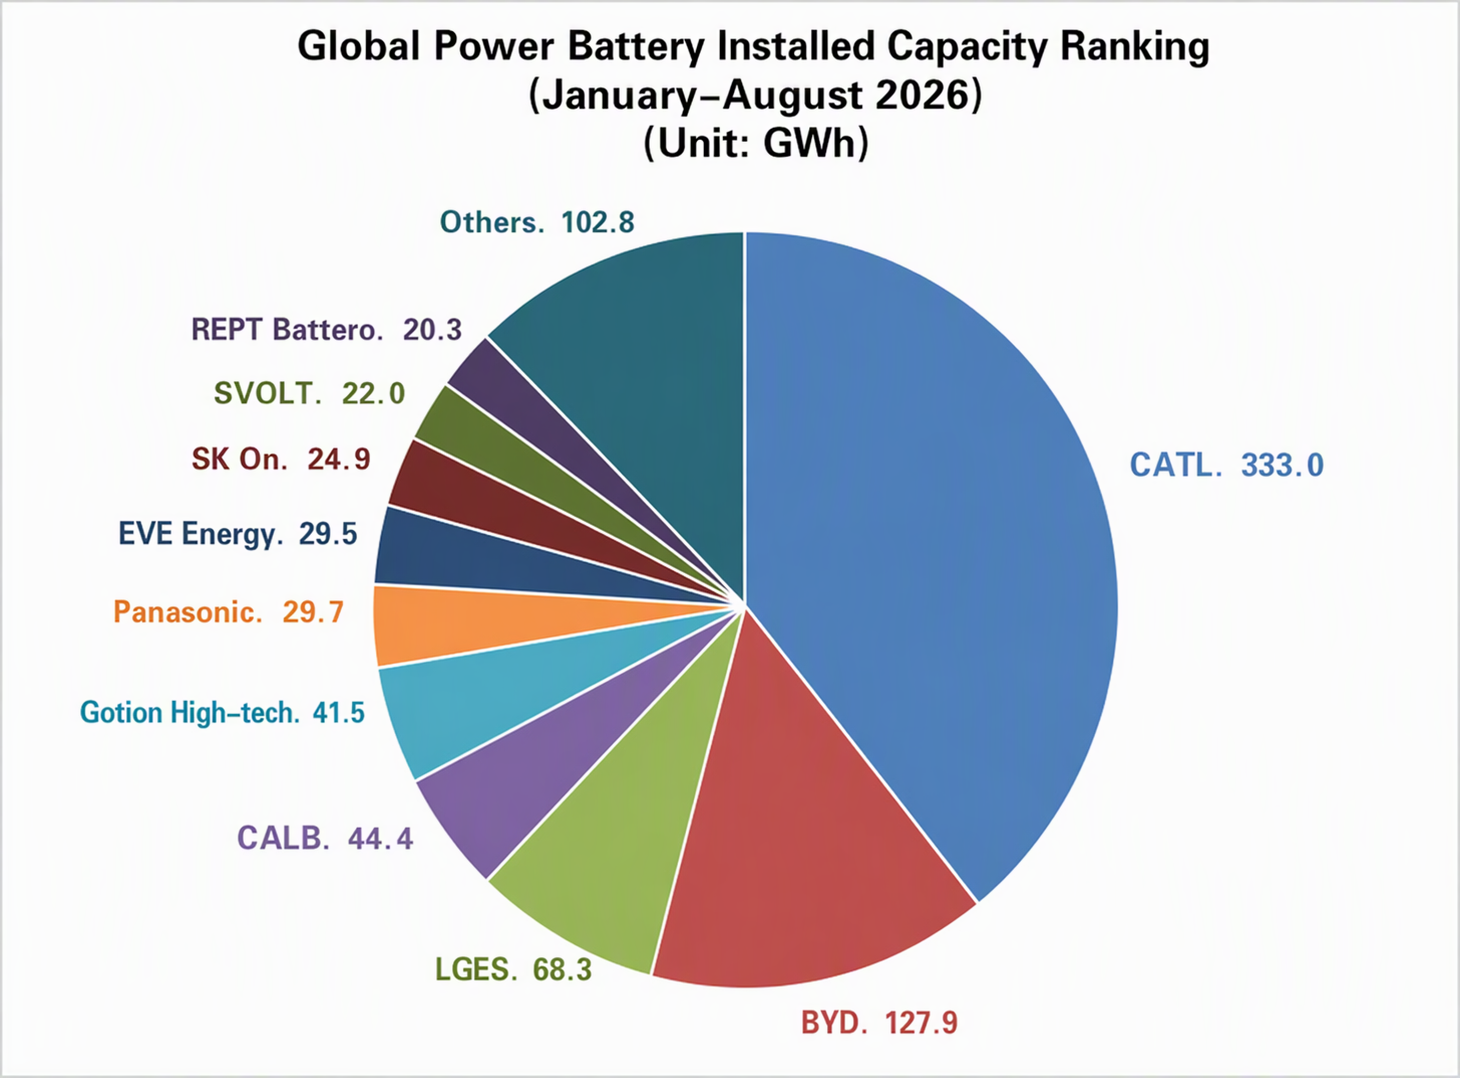
In terms of YoY changes in installations, from January to August 2026, among the global top 10 power battery installation companies, only SK On posted a YoY decline, down 14.5%. The remaining nine companies all achieved YoY growth, with REPT Battero newly entering the list at a growth rate of 126.3%, and EVE growing over 50%.
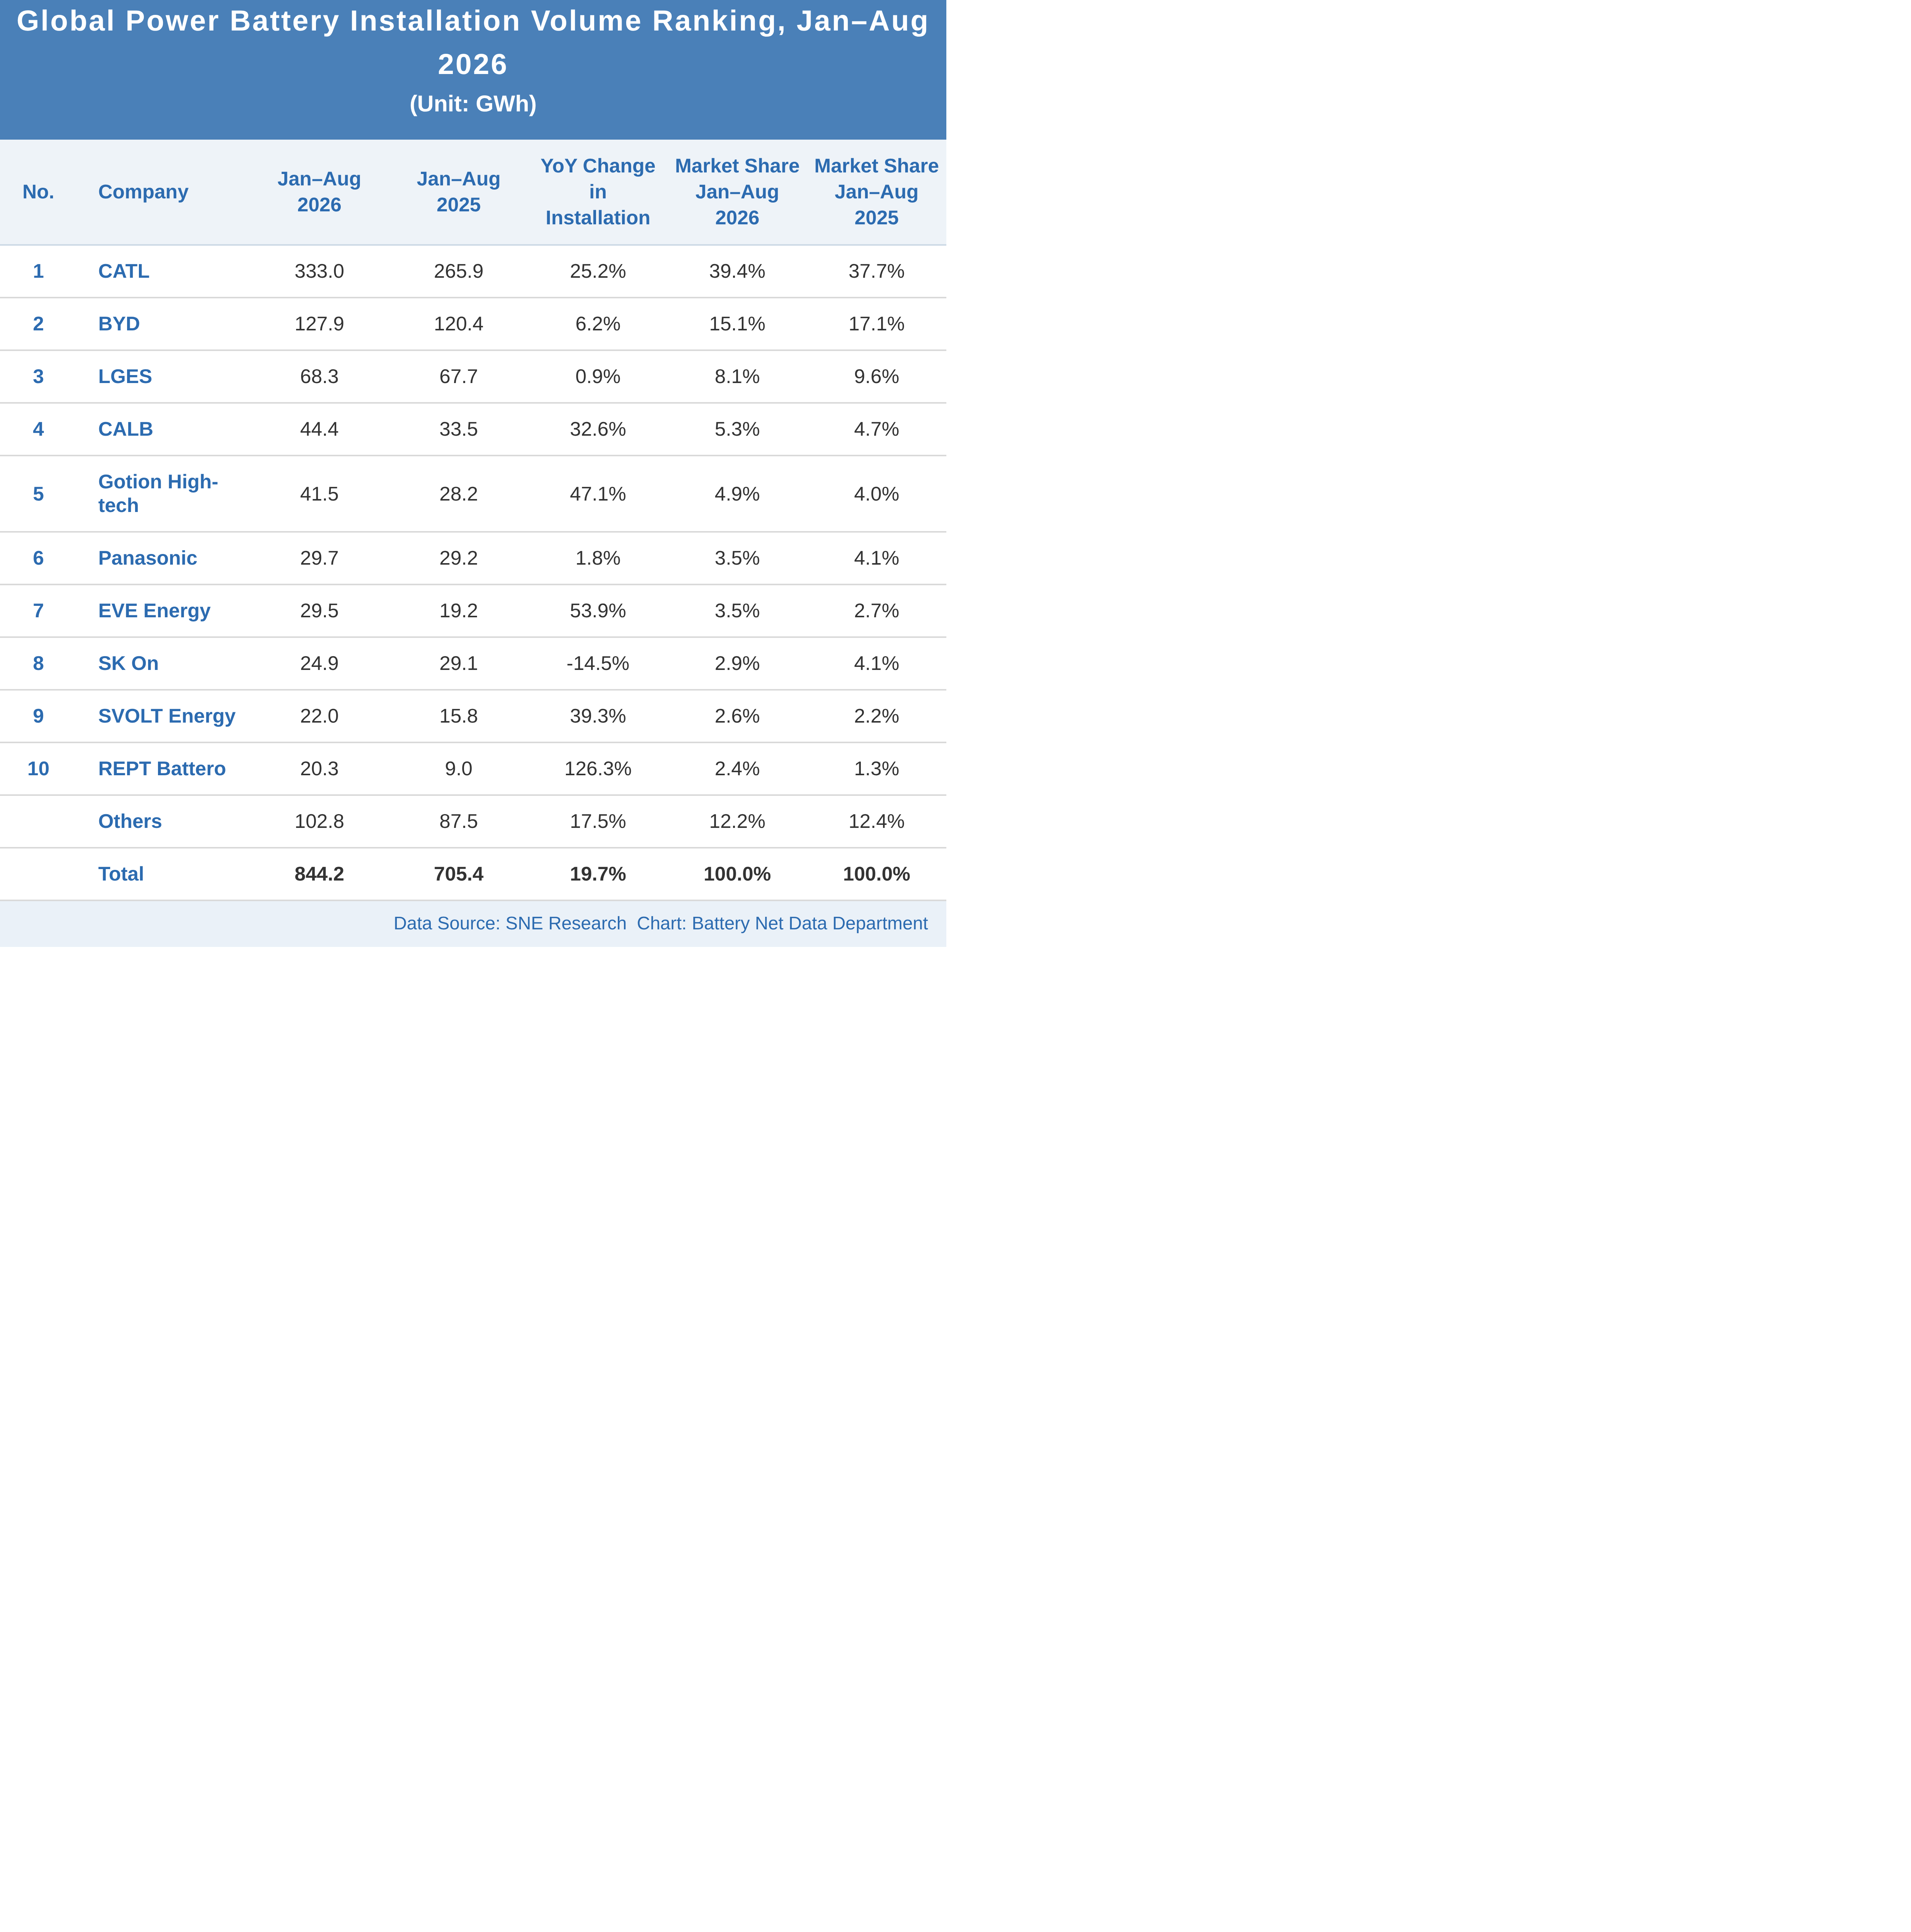
In terms of market share, compared with the same period in 2025, among the global top 10 power battery installation companies from January to August 2026, CATL, CALB, Gotion High-tech, EVE, SVOLT, and REPT Battero achieved positive YoY growth, while BYD, LGES, Panasonic, and SK On saw declines of varying degrees.
In terms of ranking changes, compared with the same period last year, the top 10 installation rankings from January to August 2026 underwent a significant reshuffle:
the top four remained unchanged—CATL, BYD, LGES, and CALB. Gotion High-tech moved up sharply from 7th place last year to 5th, displacing SK On, which fell to 8th. Panasonic held steady at 6th. EVE climbed two spots to 7th. SVOLT rose one spot from 10th to 9th.
In addition, compared with the same period last year, REPT Battero newly entered the list at 10th place, with installations 1 GWh ahead of 11th-place Sunwoda. Samsung SDI, previously ranked 8th, dropped out of the top 10.
On a MoM basis, compared with January-July 2026, battery company rankings remained unchanged.
In terms of the competitive landscape, from January to August, the combined share of CATL, BYD, CALB, Gotion High-tech, EVE, SVOLT, and REPT Battero rose from 72.8% in January-July to approximately 73.3%, up 3.6 percentage points YoY. Among them, CATL and BYD together held 54.5% of the market, with Chinese companies performing strongly overall.
Specifically, CATL's market share reached 39.4%, up 1.7 percentage points YoY, maintaining its global No. 1 position with 333 GWh of installations, up 25.2% YoY.
BYD's market share slipped to 15.1%, but it remained firmly in second place with installations of 127.9 GWh, up 6.2% YoY.
CALB ranked fourth with 44.4 GWh of installations, up 32.6% YoY, holding a 5.3% market share.
Gotion High-tech ranked fifth with 41.5 GWh of installations, up 47.1% YoY, holding a 4.9% market share.
EVE ranked seventh with 29.5 GWh of installations, up 53.9% YoY, holding a 3.5% market share.
SVOLT ranked ninth with 22 GWh of installations, up 39.3% YoY, holding a 2.6% market share.
REPT Battero ranked tenth with 20.3 GWh of installations, up 126.3% YoY, holding a 2.4% market share.
SNE noted that the continued rise in Chinese battery companies' market share is attributable to leveraging their domestic client base and LFP-driven cost competitiveness to expand sales, while also extending supply arrangements to overseas OEMs and the commercial vehicle segment.
Among them, BYD's installations grew only 6.2% YoY, mainly because its EV deliveries in China fell 33.6%. By contrast, its usage in markets outside China grew 66.5% from 23.8 GWh to 39.7 GWh, with overseas sales in August setting a new monthly record. As BYD expands its sales network and local production in Europe, Southeast Asia, and South America, the impact of the domestic market slowdown is expected to ease as its overseas market share rises.
In stark contrast to the strong momentum of Chinese companies, Japanese and South Korean battery makers have seen their growth pace slow noticeably, with cracks appearing in their camp's structure.
After Samsung SDI dropped out of the top 10, LGES and SK On together recorded installations of 93.2 GWh, with their combined global market share shrinking from 13.7% in the same period last year to 11%.
Among them, LGES ranked third with 68.3 GWh, but its 0.9% growth rate lagged the broader market. SK On, affected by the electrification pace adjustments of its North American and European clients, recorded installations of only 24.9 GWh, down 14.5% YoY, with its market share falling to 2.9%.
Japan's Panasonic maintained 6th place with 29.7 GWh of installations, up a slight 1.8% YoY. The rebound in installations came from Tesla's sales growth in North America, but the company's growth rate also trailed the average, with its market share declining from 4.1% to 3.5%.
SNE noted that from January to August 2026, the global power battery market grew 20% YoY, but regional divergence intensified. In China, a 2% consumption tax on domestically sold lithium-ion batteries took effect in September, and the battery export VAT rebate is planned to be canceled in January next year. As a result, Chinese battery suppliers' pricing policies and the pace of their overseas production are likely to affect competition at year-end.
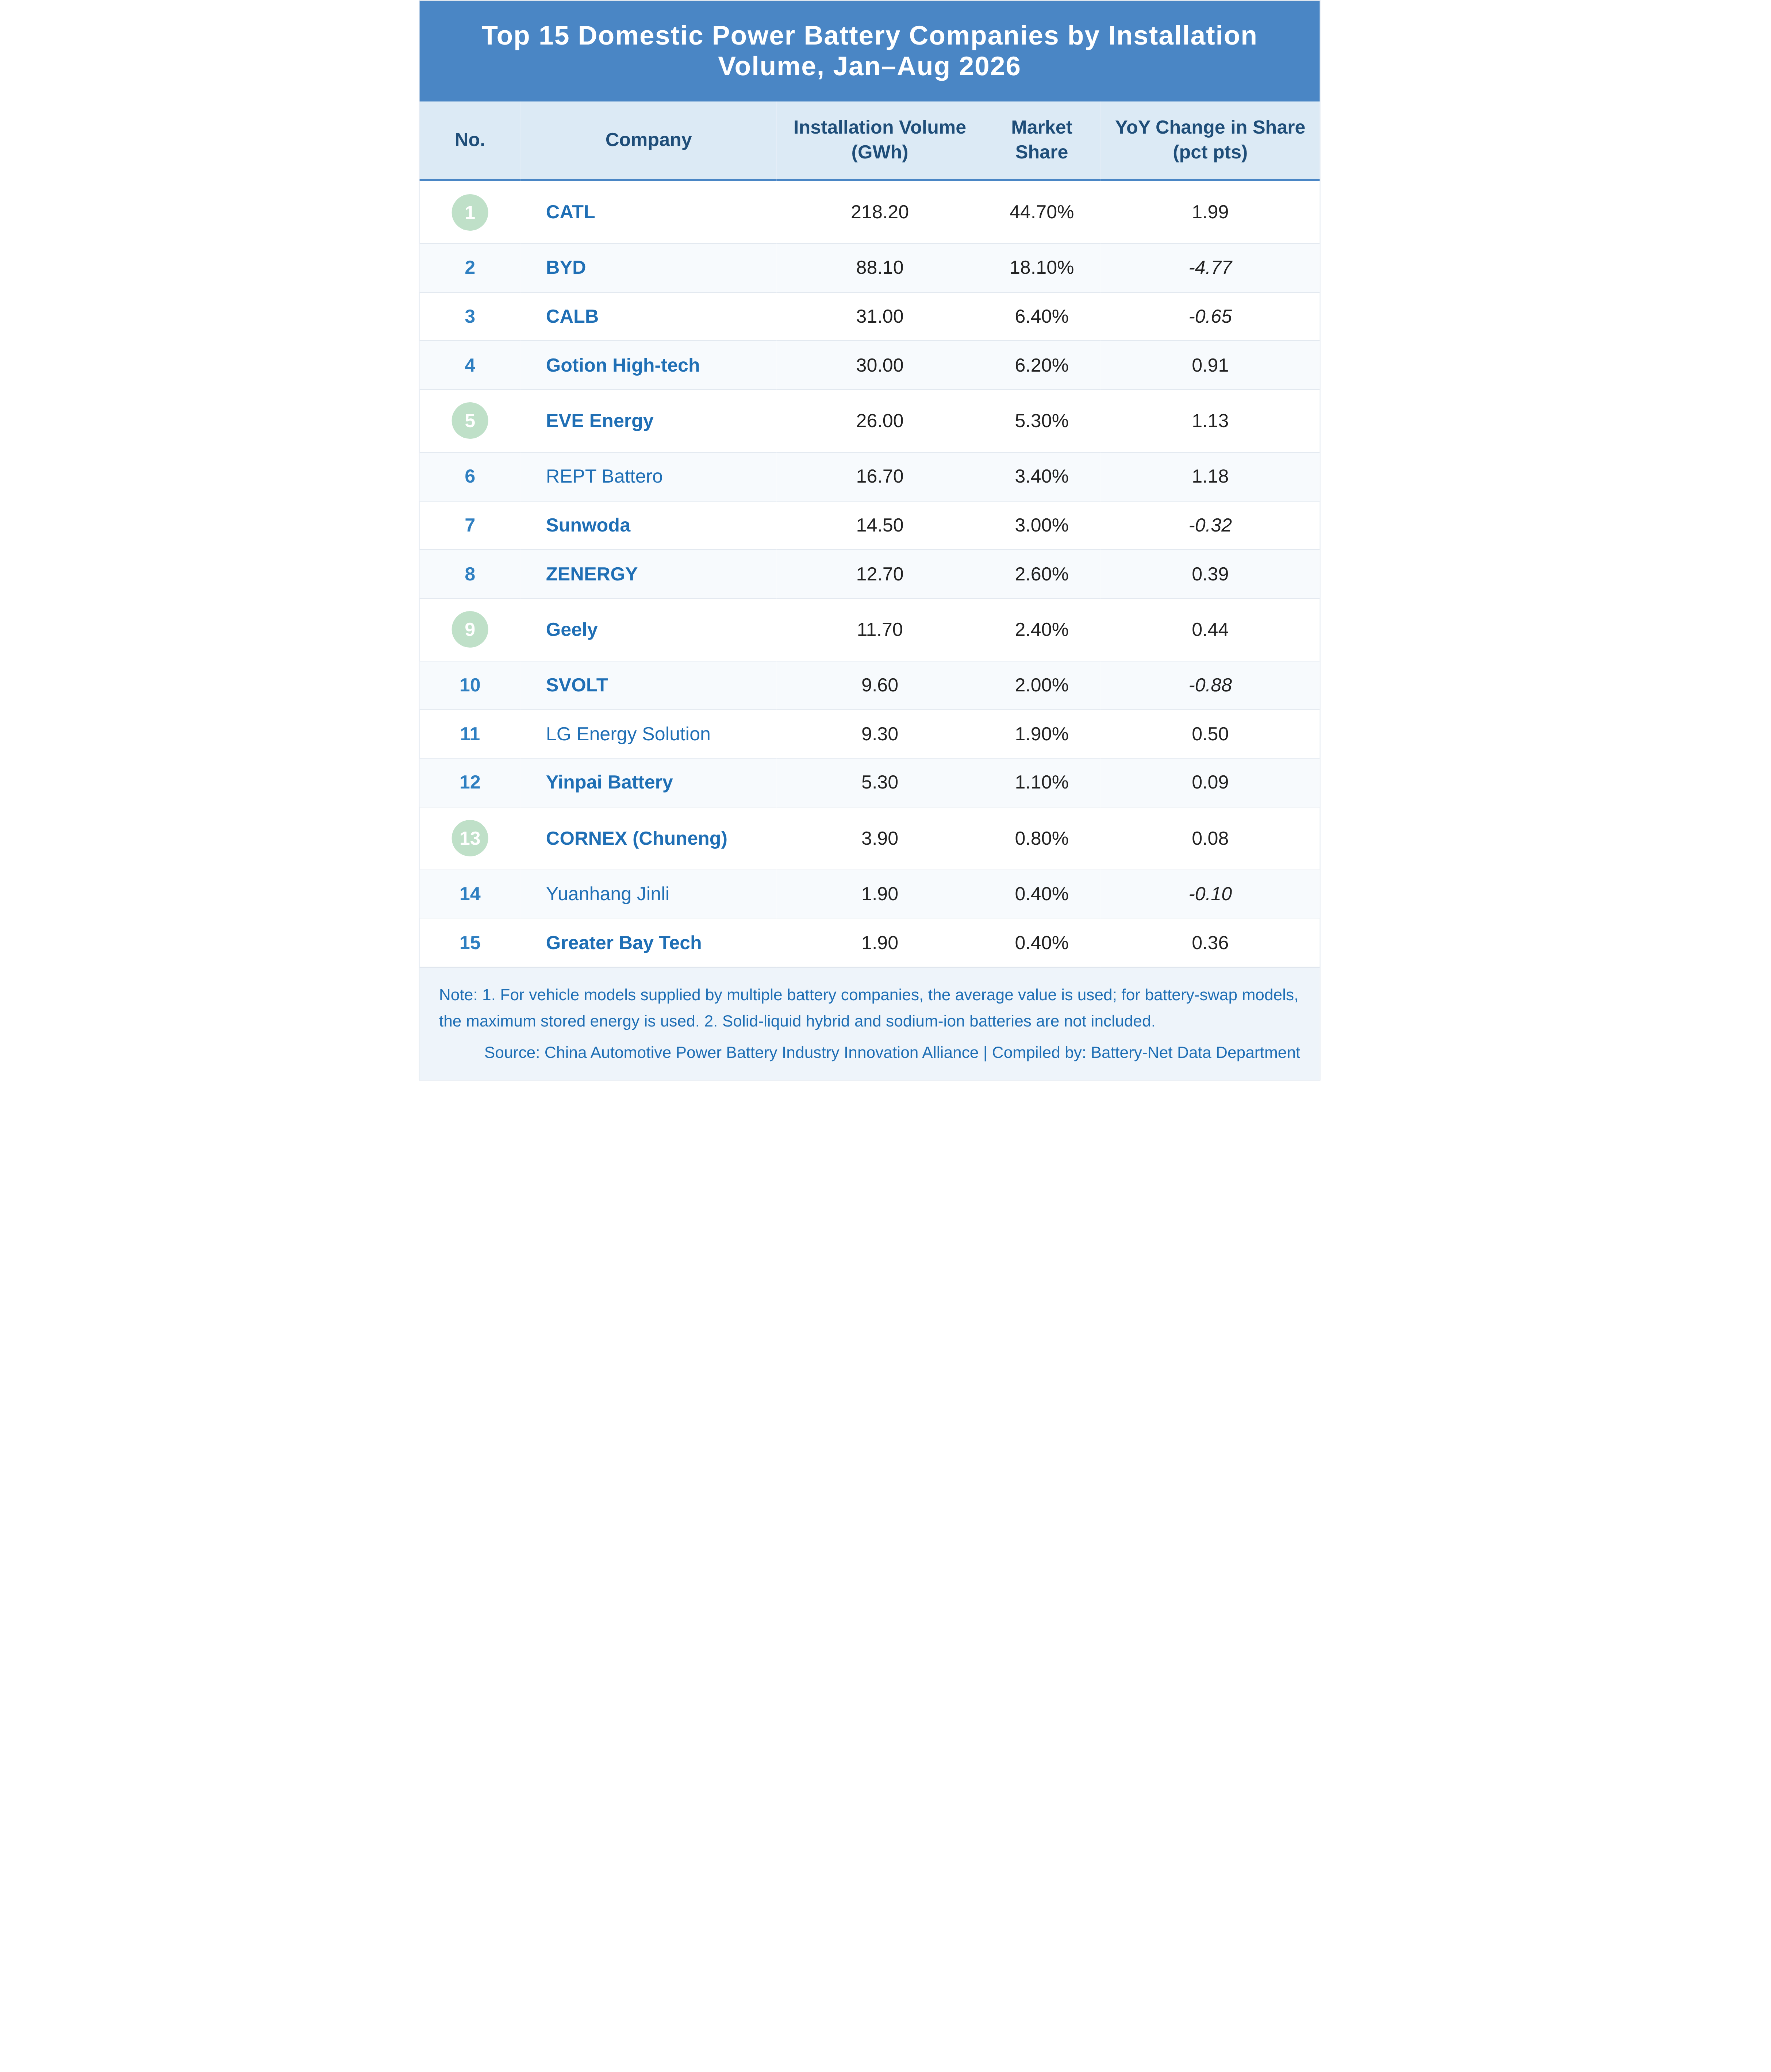
According to data released by the China Automotive Power Battery Industry Innovation Alliance, from January to August, China's cumulative power battery installations reached 489.1 GWh, up 17.0% YoY.
Compared with the same period in 2025, from January to August this year, CATL, REPT Battero, EVE, Gotion High-tech, LG Energy Solution, Jiyao Tongxing, Zenergy, Greater Bay Technology, Inpai Battery, and CORNEX New Energy achieved improvements of varying degrees. Among them, CATL posted the largest gain at 1.99 percentage points.