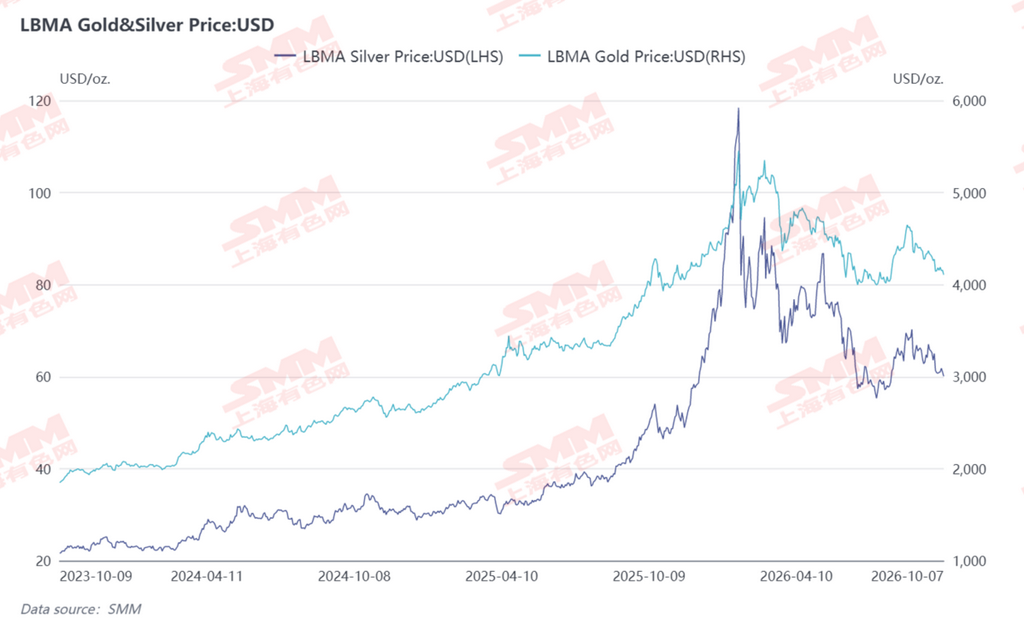
During the National Day holiday, international silver moved sideways in a range after rising first and then falling, closing the holiday down about 1.1% overall (60.43→59.77). Early in the week, supported by mild inflation expectations and central bank "de-dollarization" buying, silver rebounded above $61, and on Monday and Tuesday it rose for two consecutive days to a range high of 61.34, helped by a weaker US dollar. However, on Wednesday, the Fed minutes confirmed that most officials expected another rate hike before year-end, the 1-year inflation expectations hit a three-year high, and the US dollar climbed back above 102.3. Silver plunged 2.54% in a single day to 59.77, giving back all of the week's gains and testing the lower end of the range, while gold also fell below the $4,100 level. The specific macro timeline is as follows:
- 10.1-10.2: Mild rebound in the early post-holiday period. 10.1 closed at 60.98 (+0.98%), and 10.2 closed at 60.35 (-1.04%). US August core PCE came in below expectations, and US Treasury yields shot up before briefly pulling back. In addition, the Bank of Korea resumed gold purchases after a 13-year hiatus, providing allocation support from central bank buying. However, the US dollar index continued to strengthen and held above 102, and the market awaited non-farm payrolls data. Bullish momentum was limited, and silver pulled back again after the rebound.
- 10.3-10.4: No trading over the weekend, with events accumulating. There was no international trading session over the weekend. On the event front, Malaysia announced the removal of a 10% import tariff on some gold in November, improving expectations for physical precious metals demand. Middle East geopolitical news remained mixed, causing only sentiment-driven fluctuations without direct price impact.
- 10.5-10.6: A surprisingly weak non-farm payrolls report drove a sharp rally to the weekly high. 10.5 closed at 61.05 (+1.17%), and 10.6 closed at 61.34 (+0.47%). US September non-farm payrolls added only 29,000 jobs, far below the expected 90,000. The market immediately slashed the probability of an October rate hike, and cooling expectations for tightening became the strongest bullish driver of the week. The rise in US Treasury yields paused temporarily, the US dollar briefly pulled back, and silver shot up to a weekly high of $61.34. Russia's Finance Ministry announced increased gold purchases, and global gold ETFs absorbed substantial inflows in Q3, further reinforcing allocation support.
- 10.7: Hawkish FOMC minutes erased all gains, and silver broke down. 10.7 closed at 59.77 (-2.54%), with an intraday low of $58.96. The September FOMC meeting minutes released in the evening sent hawkish signals, with most officials expecting one more rate hike before year-end. The New York Fed's 1-year inflation expectations rebounded to 3.9%, a three-year high. The US dollar rebounded again to stand above 102.27, and long-end US Treasury yields remained near their highest levels since 2002. Multiple macro headwinds intensified, and silver sold off sharply, breaking below the psychological level of $60 and largely erasing the gains driven by the earlier non-farm payrolls report.
[Bearish for precious metals]
FOMC minutes release a hawkish tone, expectations for a December rate hike reheat
The Fed's September monetary policy meeting minutes showed that most participating officials believed it might be appropriate to further raise the target range for the federal funds rate before year-end, with the high-rate maintenance cycle extending further than previously expected. Although the September hike had been fully priced in by the market, the signal conveyed in the minutes that "there is still one more hike this year" exceeded the market's dovish expectations, and market pricing for a December hike gradually recovered. The easing expectations previously generated by weak employment data were partially revised. The tail risk of policy tightening remains unresolved, continuing to weigh on the valuation of non-yielding precious metals.
US Treasury yields hold at two-decade highs, US dollar index consolidates on a strong note
During the National Day holiday, long-end US Treasury yields shot up again, with the 10-year Treasury yield briefly touching 5.36%, refreshing a more than two-decade high since April 2002. Although it subsequently pulled back slightly to around 5.28%, the absolute level remains in a historically high range; the 2-year Treasury yield moved sideways in the 4.80%-4.83% range, highlighting the stickiness of short-end policy rates. The US dollar index maintained its strong pattern in tandem, rising to an intraday high of 102.11 before pulling back to 101.84 at the close, still at a high level over the past six months. Elevated real US Treasury yields continue to raise the opportunity cost of holding precious metals, while a stronger dollar directly suppresses dollar-denominated precious metal prices, with the dual pressures jointly forming a ceiling constraint on valuations.
Global inflation pressures rebound marginally, BOJ rate hike expectations roil global bond markets
Inflation stickiness risks have resurfaced, with the New York Fed's 1-year inflation expectations rebounding to 3.9%, a three-year high, underscoring the bumpy nature of the price decline process. Meanwhile, the Bank of Japan released signals hinting that underlying inflation has reached the 2% policy target, and market expectations for the BOJ to exit its ultra-loose policy and initiate rate hikes have heated up again. Rising Japanese bond yields could trigger a chain reaction in global bond markets, pushing up the global risk-free rate center and indirectly exerting peripheral pressure on precious metals.
US-Iran geopolitical conflict escalates again, oil prices support inflation-tightening logic
Middle East geopolitical tensions persist, US-Iran confrontation escalates, and a senior adviser to Iran's Islamic Revolutionary Guard Corps explicitly stated that "illegal shipping lanes" in the Strait of Hormuz will be closed, leaving regional shipping security risks in place. Although the geopolitical conflict itself carries safe-haven attributes, the current core market logic remains focused on inflation and the policy path - the conflict raises the risk of an energy price rebound, reinforces sticky inflation expectations, and in turn supports the US Fed's tightening logic of maintaining high rates and even subsequent hikes, indirectly weighing on precious metal valuations.
[Bullish for precious metals]
Non-farm payrolls sharply disappoint, October rate hike expectations largely dissipate
US September non-farm payrolls rose by only 29,000, far below market expectations of 90,000, while the unemployment rate climbed to 4.2%, a near two-year high, and July-August employment data were revised down by a combined 60,000, sending a clear signal of labour market cooling. After the data release, the market's implied probability of an October Fed rate hike fell quickly from around 70% to below 25%, and CME rate futures showed a more than 70% probability that rates would be left unchanged in October. Short-term tightening pressure eased significantly, making this the most direct bullish driver during the holiday and fuelling a rapid rebound in precious metals.
Divergence emerges within the Fed, neutral remarks ease one-sided tightening expectations
Clear divisions have appeared among Fed officials: Minneapolis Fed President Kashkari and Boston Fed President Collins struck a relatively neutral tone, arguing that current policy is already in restrictive territory and that patience is needed to assess the data before making further judgements; Fed Governor Bowman stated more explicitly that no further rate adjustment is needed this year. In contrast to the hawkish tone of the meeting minutes, the divergence among officials implies that policy is not tightening on a one-sided basis, preserving room for the market to imagine a marginal policy pivot and easing the pressure on precious metals from one-sided tightening expectations.
China's monetary policy adds further easing, liquidity conditions improve at the margin
The PBOC announced that on 8 October it would conduct 1.2 trillion yuan in outright reverse repo operations with a tenor of 3 months, an increase of 200 billion yuan over the maturing amount, with the injection exceeding market expectations. Further easing in domestic monetary policy and marginal improvement in market liquidity conditions help boost domestic allocation demand for precious metals, while stable RMB exchange rate expectations also support domestic precious metal prices, indirectly benefiting futures sentiment through the linkage between domestic and overseas markets.
Energy supply eased on multiple fronts, and falling oil prices weakened the inflation-rate hike chain
The global energy supply landscape saw multiple marginal easing: the G7 decided to coordinate through the IEA to release up to 100 million barrels of crude oil and diesel reserves within four months; Trump explicitly denied that a diesel export ban would be implemented; Saudi Arabia gradually resumed exports after repairing its east-west pipeline, with Middle East crude oil exports rebounding to near pre-war levels; OPEC+ decided to postpone the capacity assessment and keep current production unchanged. Under the combined effect of multiple factors, international oil prices pulled back in stages, and the secondary inflation pressure from rising energy prices eased marginally, which in turn weakened the underlying logic of continued rate hikes by the US Fed and provided indirect support for precious metals.
[Macro Summary]
During the National Day holiday, bullish and bearish factors intertwined in the precious metals market, which overall retreated after a rapid rise. Mid-week, the sharply weaker-than-expected nonfarm payrolls drove a rapid cooling of October rate hike expectations, and together with easing energy supply and loose liquidity in China, pushed precious metals to rebound in stages. However, the subsequent hawkish signals from the FOMC minutes, US Treasury yields holding at two-decade highs, the US dollar index consolidating on a strong note, and escalating geopolitical conflicts supporting the inflation-tightening logic jointly pressured the futures to give back most of their gains.
In the short term, the largely dissipated October rate hike expectations provide a buffer, but December rate hike expectations remain, and the consolidation of US Treasury yields and the US dollar index at highs remains the core suppressing force; fluctuations in energy prices and geopolitical situations will also continue to disturb inflation expectations. Over the medium and long term, the underlying logic of continued gold purchases by global central banks, the accumulation of US debt risks, and the de-dollarization trend remains unchanged, which will still provide long-term bottom support for precious metals. Going forward, close attention should be paid to US inflation data, statements from US Fed officials, and marginal changes in the Middle East situation.