[SMM Analysis] Sheets & Plates Holiday Review, HRC Prices Mostly Down 10-20 yuan/mt
During the National Day holiday, HRC prices in mainstream cities across the country remained stable.
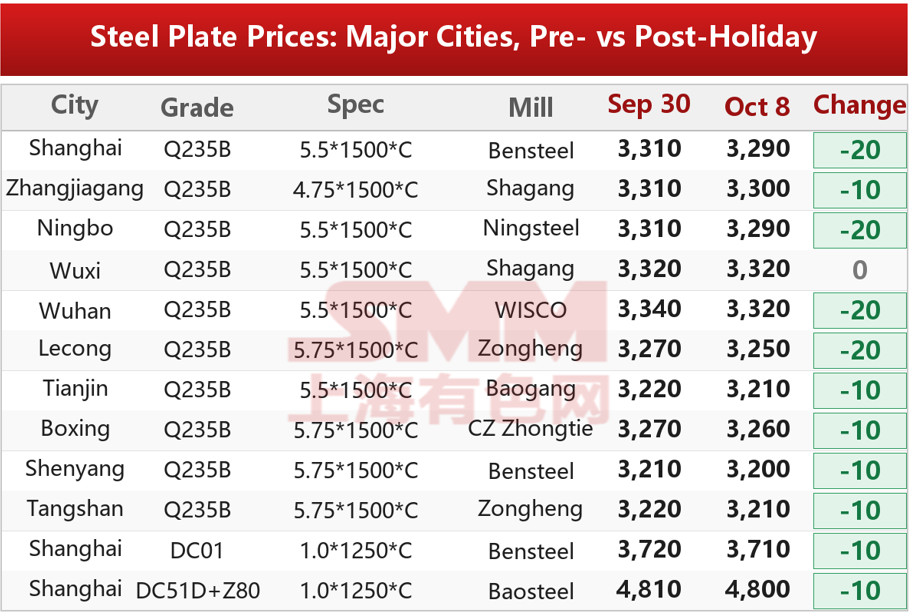
On the first trading day after the holiday, in the east China market, Shanghai quotes were down 20-30 yuan/mt from pre-holiday levels, with mainstream resource quotes at 3,280-3,290 yuan/mt and average market inquiry sentiment. Ningbo spot cargo was quoted at 3,280-3,290 yuan/mt, down 20-30 yuan/mt from pre-holiday levels, with market trading sentiment improving slightly, but some end-user purchasing enthusiasm remained weak, mainly wait-and-see. Hangzhou spot cargo was quoted at 3,300-3,310 yuan/mt, down 20 yuan/mt from pre-holiday levels, with traders mostly holding prices firm for now.
On the first trading day after the holiday, in the south China market, Lecong quotes were down 10-20 yuan/mt from pre-holiday levels, with mainstream resource quotes at 3,260-3,270 yuan/mt. Traders were relatively firm on prices, market inquiry sentiment was average, and no significant inquiry release was seen.
On the first trading day after the holiday, quotes in the northern Tangshan area were down about 10 yuan/mt from pre-holiday levels, with mainstream resource quotes at 3,210-3,220 yuan/mt. Traders currently hold weak expectations for the market outlook, but due to their own low inventory, they have the willingness to hold prices firm. Similarly, downstream wait-and-see sentiment is strong, market trading sentiment is average, and overall trading volume is low.
In the cold-rolled market, on the first trading day after the holiday, Bensteel Group cold-rolled in Shanghai was quoted at 3,710 yuan/mt, down 10 yuan/mt from pre-holiday levels. There was no significant restocking after the holiday, the market was mostly in a wait-and-see state, and prices edged down with limited declines.
Data Source: SMM
Looking ahead, with the holiday over, nationwide inventory is expected to accumulate significantly. Attention should be paid to demand recovery and inventory destocking pace in the first 1-2 weeks after the holiday. In the short term, HRC prices are likely to trade within a weak range, with focus on the 3230-3300 range for the most-traded contract.
Copyright and Intellectual Property Statement:
This report is independently created or compiled by SMM Information & Technology Co., Ltd. (hereinafter referred to as "SMM"), and SMM legally enjoys complete copyright and related intellectual property rights.
The copyright, trademark rights, domain name rights, commercial data information property rights, and other related intellectual property rights of all content contained in this report (including but not limited to information, articles, data, charts, pictures, audio, video, logos, advertisements, trademarks, trade names, domain names, layout designs, etc.) are owned or held by SMM or its related right holders.
The above rights are strictly protected by relevant laws and regulations of the People's Republic of China, such as the Copyright Law of the People's Republic of China, the Trademark Law of the People's Republic of China, and the Anti-Unfair Competition Law of the People's Republic of China, as well as applicable international treaties.
Without prior written authorization from SMM, no institution or individual may:
1. Use all or part of this report in any form (including but not limited to reprinting, modifying, selling, transferring, displaying, translating, compiling, disseminating);
2. Disclose the content of this report to any third party;
3. License or authorize any third party to use the content of this report;
4. For any unauthorized use, SMM will legally pursue the legal responsibilities of the infringer, demanding that they bear legal responsibilities including but not limited to contractual breach liability, returning unjust enrichment, and compensating for direct and indirect economic losses.
Data Source Statement:
(Except for publicly available information, other data in this report are derived from publicly available information (including but not limited to industry news, seminars, exhibitions, corporate financial reports, brokerage reports, data from the National Bureau of Statistics, customs import and export data, various data published by major associations and institutions, etc.), market exchanges, and comprehensive analysis and reasonable inferences made by the research team based on SMM's internal database models. This information is for reference only and does not constitute decision-making advice.
SMM reserves the final interpretation right of the terms in this statement and the right to adjust and modify the content of the statement according to actual circumstances.