Ahead of the National Day holiday, China's social copper inventories saw slight destocking, and spot supply in the market tightened. Affected by production suspensions during the two holidays, operating rates at domestic copper cathode rod enterprises fell notably this week, with raw material and finished product inventories at processing plants showing structural divergence. Based on the National Day holiday situation, under the combined impact of tight spot supply, high premiums, and weak end-use demand, copper rod enterprises extended their holiday production suspensions this year, and the market remained generally cautious about a recovery in the traditional October peak season.
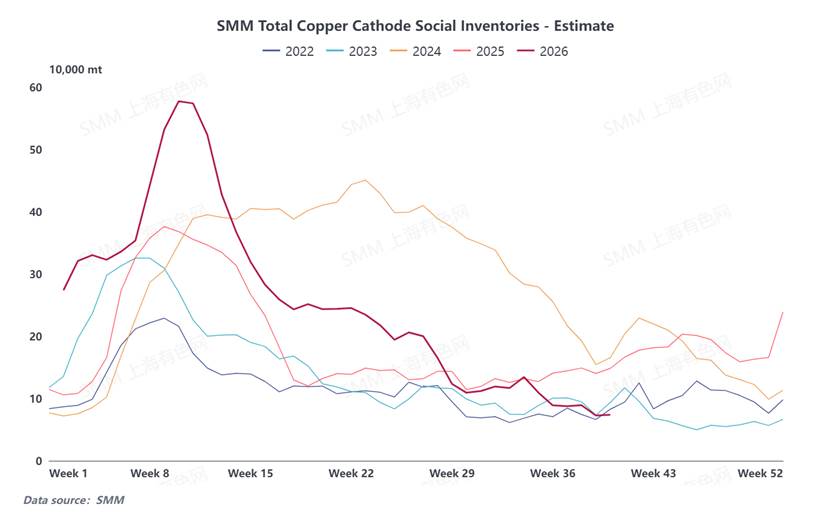
On the inventory side, as of September 30, copper inventories in major regions across China edged down MoM, with the total pulling back by 1,100 mt to 73,700 mt. Previously accumulated point-price stockpiling orders were settled in a concentrated manner, and batch cargo pick-ups drove a slight decline in social inventories.
Affected directly by the holiday, the production pace of copper cathode rod in China slowed down on a phased basis this week. In the last week before the holiday (September 25–October 1), the operating rate of major copper cathode rod enterprises in China was recorded at 64.75%, down 5.15 percentage points WoW. The core reason for the decline in operating rates this week was the disruption from the Mid-Autumn Festival holiday and the production halt on the first day of the National Day holiday, with most enterprises suspending work for the holiday starting October 1. However, before the holiday, rigid downstream demand was released in a concentrated manner, and enterprises actively rushed to fulfill orders and stockpiled in advance, effectively offsetting part of the decline in operating rates and making actual operating performance this week better than earlier market expectations. Meanwhile, core downstream copper end-users such as wire and cable and enamelled wire were also affected by the holiday shutdowns, with operating loads generally lowered, and the overall production and raw material consumption pace of end-users slowed down in tandem.
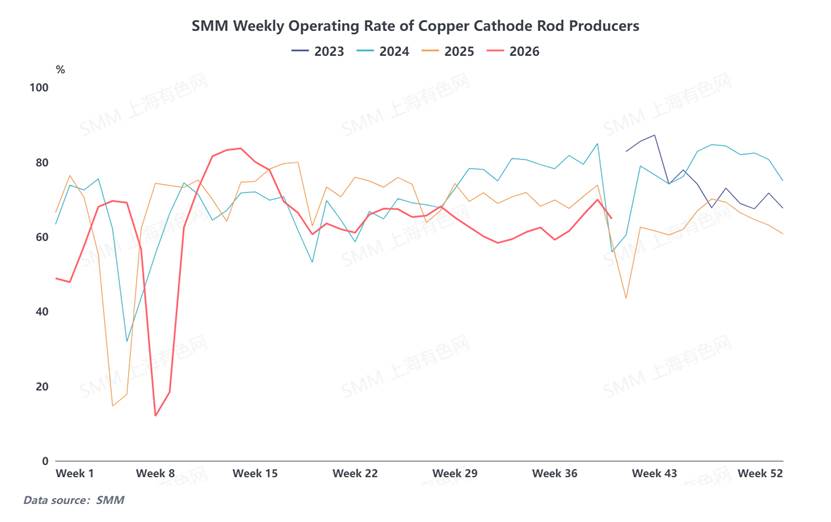
Inventory divergence among processing enterprises is pronounced. On the raw material side, thanks to concentrated pre-holiday cargo pick-up, raw material inventories at copper rod producers rose MoM, with enterprises completing a round of pre-holiday raw material stockpiling. On the demand side, end-use production slowed and purchasing willingness cooled, with downstream pick-up pace weakening. Finished product inventory pressure at copper rod producers continued to build, with finished product inventory growth outpacing the raw material side, highlighting insufficient momentum in pre-holiday end-use demand and weak willingness to stockpile proactively. 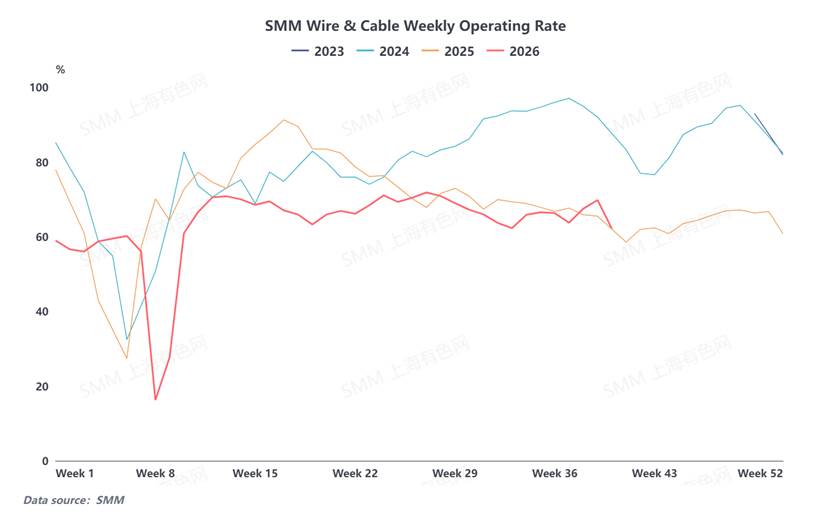
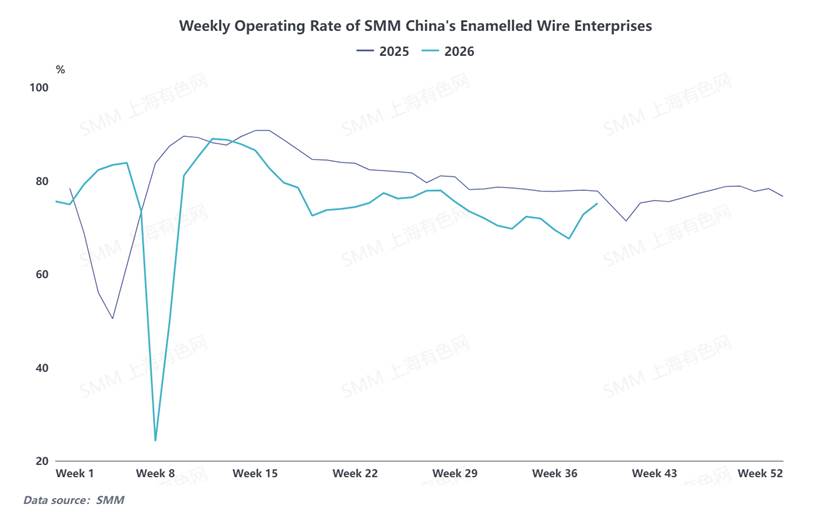
SMM surveyed 20 major copper cathode rod enterprises in China regarding their National Day holiday schedules and pre-holiday stockpiling, with the sample covering an annual capacity of 7.66 million mt. This year, the industry's overall National Day holiday duration increased compared with previous years. Pre-holiday market conditions and demand trends reversed several times. Earlier, copper prices fluctuated at highs for an extended period, continuously suppressing downstream purchasing enthusiasm. Near the holiday, copper prices pulled back in the short term, briefly releasing rigid demand and driving a surge in copper rod orders. The market initially anticipated that enterprises would shorten their production stoppages. However, affected by subsequent tightening of spot supply and a sharp rise in premiums, end-users found it difficult to bear high-priced raw materials. Stockpiling sentiment cooled rapidly, and new orders weakened again. Ultimately, enterprise holiday days increased rather than decreased.
In terms of holiday days, same-caliber sample comparisons show that in 2025, enterprises took an average of 4.05 days off for National Day, while in 2026, the average holiday duration increased to 4.4 days, up 0.35 days YoY. Meanwhile, downstream end-users such as wire and cable and enamelled wire producers saw holiday durations basically unchanged from last year due to no clear demand recovery. Analyzing the overall production pace within the year, in Q1, the industry achieved improved operating rates supported by copper price pullbacks and sluggish secondary rod supply. However, since mid-year, copper prices have fluctuated at highs, continuously suppressing end-user order-taking and enterprise production schedules. Combined with the pre-holiday pattern of high premiums and weak orders, industry production pressure has remained prominent.
Looking ahead to October, multiple factors are weighing on industry sentiment. The long holiday production stoppage will significantly drag down the monthly operating rate. Combined with high copper prices suppressing consumption, the traditional "Golden October" has yet to show clear recovery signals. The October copper cathode rod operating rate is expected to continue declining, with consumption weaker than the same period last year. Post-holiday copper cathode social inventory is expected to shift into an inventory buildup phase, and the subsequent production pace remains to be observed. Current uncertainties persist in spot premiums and order recovery. Enterprises will dynamically adjust production schedules in line with copper price trends and downstream order changes.