SMM, September 30:
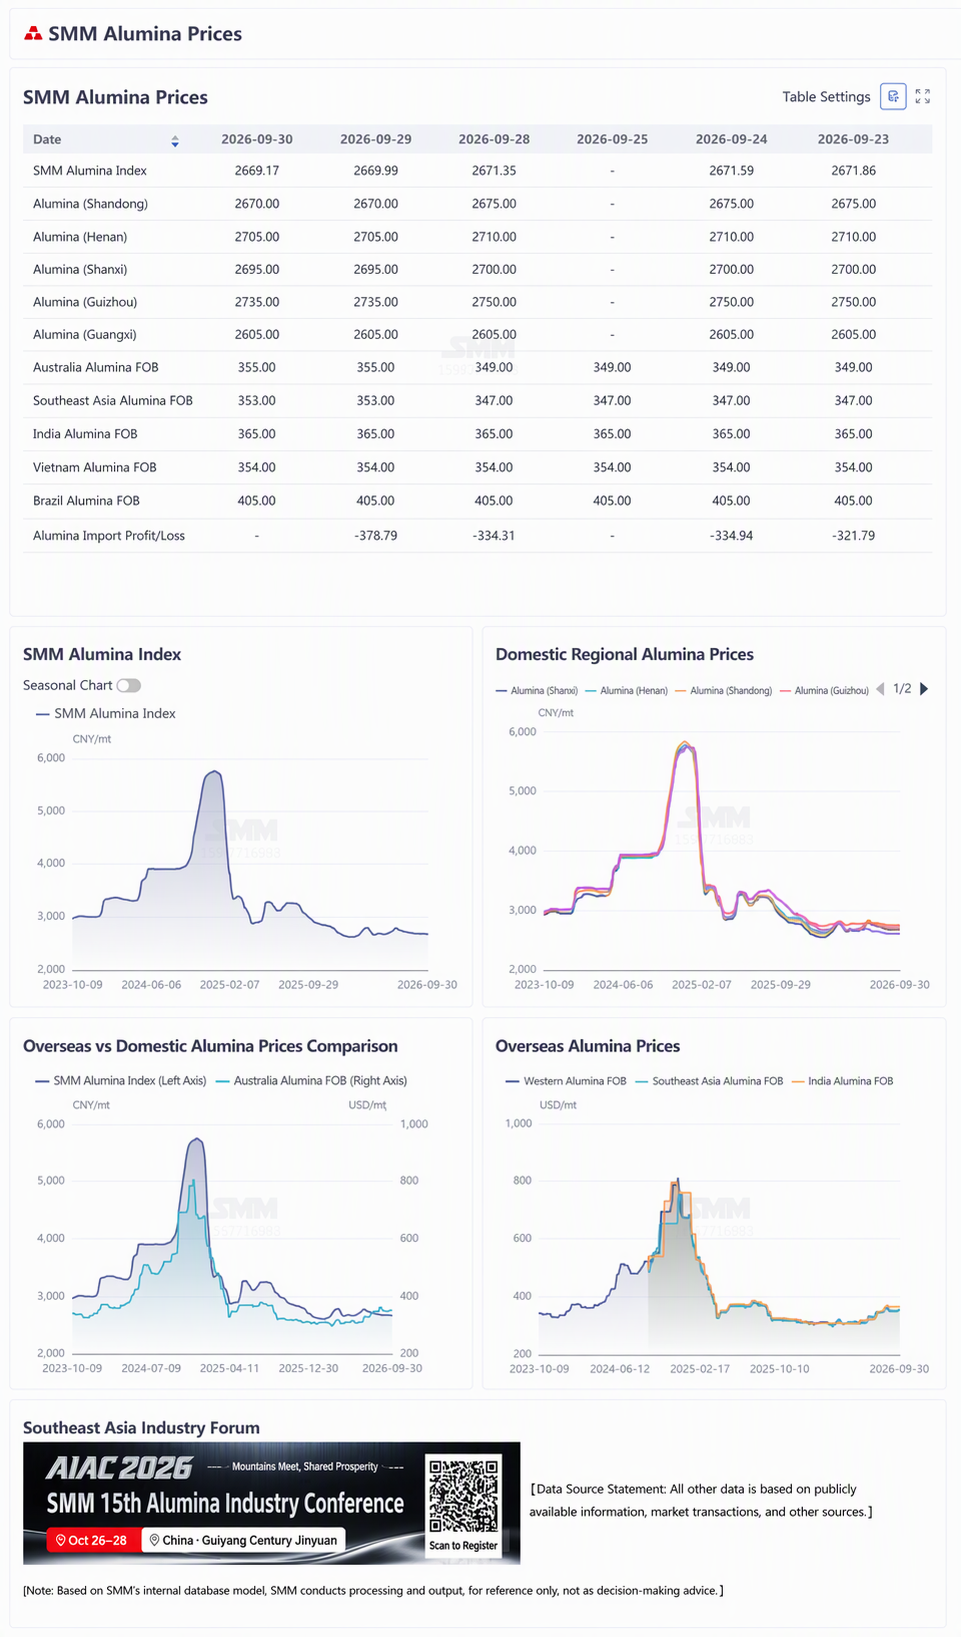
According to SMM data, as of Wednesday this week, the SMM alumina index stood at 2,669.17 yuan/mt, down 2.42 yuan/mt from last Thursday. In Shandong, prices were reported at 2,630-2,710 yuan/mt, down from last Thursday; in Henan, prices were reported at 2,670-2,740 yuan/mt, down from last Thursday; in Shanxi, prices were reported at 2,670-2,720 yuan/mt, down from last Thursday; in Guangxi, prices were reported at 2,580-2,630 yuan/mt, flat from last Thursday; in Guizhou, prices were reported at 2,710-2,760 yuan/mt, down from last Thursday.
Markets outside China: As of September 30, 2026, the FOB Western Australia alumina price was $355/mt, with an ocean freight rate of $35.95/mt and a USD/CNY selling rate around 6.72. This translates to an external selling price of approximately 3,050.18 yuan/mt at major Chinese ports, 381.01 yuan/mt above the alumina index price. Two overseas spot alumina transactions were reported this week, with details as follows:
(1) On September 30, 2026, 30,000 mt of alumina was traded overseas at $369/mt FOB Western Australia for November shipment.
(2) On September 28, 2026, 30,000 mt of alumina was traded overseas at $363/mt FOB Western Australia for late October shipment.
According to SMM data, as of Wednesday this week, China's total built metallurgical-grade alumina capacity was 119.62 million mt/year, with operating capacity at 92.44 million mt/year. The national weekly operating rate for metallurgical-grade alumina rose 0.39 percentage points WoW to 77.28%. Among regions, Shandong's weekly alumina operating rate fell 3.76 percentage points WoW to 85.44%; Shanxi's weekly alumina operating rate rose 1.76 percentage points WoW to 74.24%; Henan's weekly alumina operating rate fell 5.00 percentage points WoW to 54.83%; Guangxi's weekly alumina operating rate rose 2.65 percentage points WoW to 82.10%; Guizhou's weekly alumina operating rate rose 3.17 percentage points WoW to 84.50%.
In the spot market, one transaction was concluded this week. A Xinjiang-based buyer procured 10,000 mt of spot alumina at a delivered price of 2,960 yuan/mt.
This week, China's total alumina inventory increased by 106,000 mt to 7.479 million mt, with the pace of inventory buildup accelerating. By segment: aluminum smelter raw material inventories rose 66,600 mt to 3.5592 million mt, as downstream stocking willingness improved ahead of the holiday; alumina refinery finished product inventories rose 32,200 mt to 1.3157 million mt, continuing to accumulate amid high production levels; port inventories edged down 5,000 mt to 961,000 mt, largely stabilizing; in-transit and platform stockpiles rose 11,000 mt to 1.402 million mt; warrant inventories inched up to 240,900 mt. Industry-wise, national weekly alumina production was 1.773 million mt this week, up 9,000 mt WoW, with the growth mainly from the continued release of new capacity in Guangxi, coupled with full recovery of enterprises in Shanxi previously affected by red mud pond issues, while operating rates in Shandong and Henan pulled back somewhat, keeping overall supply high. In September, national metallurgical-grade alumina production rose 0.7% MoM, further intensifying the supply-demand surplus. Futures prices consolidated on a weak note at low levels with shrinking volume ahead of the holiday, while futures and spot trends diverged somewhat, market trading activity declined, and both long and short sides turned cautious and wait-and-see. Downstream aluminum smelters mainly purchased as needed with slight pre-holiday restocking of raw materials, with no concentrated stockpiling observed. Looking ahead, SMM expects metallurgical-grade alumina operating capacity in October to be around 93.44 million mt, with existing capacity maintained at 119.62 million mt/year, and the weekly operating rate is expected to continue rising to around 78%. No maintenance or production cut plans have been reported by enterprises so far, and with winter approaching, aluminum smelters will gradually begin stockpiling, so supply pressure is expected to keep increasing. On the inventory side, high production and downstream stockpiling will offset each other, and national alumina total inventory is expected to continue its buildup trend after the holiday. On the price side, with the supply-demand surplus unchanged and limited upward drivers, spot prices are expected to remain stable with slight fluctuations on the weak side.
[All data other than public information are processed by SMM based on public information, market communication, and SMM's internal database models, and are for reference only and do not constitute decision-making advice.]