SMM, September 30:
On Tuesday, a number of US Fed officials made intensive remarks, setting the tone for the monetary policy path for the rest of the year. New York Fed President John Williams said in a speech in Buffalo, New York, that if the economy evolves broadly in line with his expectations, another rate hike later this year may be appropriate to bring inflation back to target in a more timely manner. However, he also stressed that the Fed's September rate hike has already bought policymakers more time to observe, and "there is no need to rush." The remarks were a mix of dovish and hawkish signals, and market expectations for a Fed rate hike in October quickly pulled back from around 70% to about 50%. In addition to cooling rate hike expectations, multiple factors also supported the strength of precious metals: the US dollar index weakened; global geopolitical uncertainty persisted, with safe-haven funds continuing to flow into the gold market; meanwhile, central banks around the world maintained strong gold purchase demand, building a medium and long-term structural floor for gold prices.
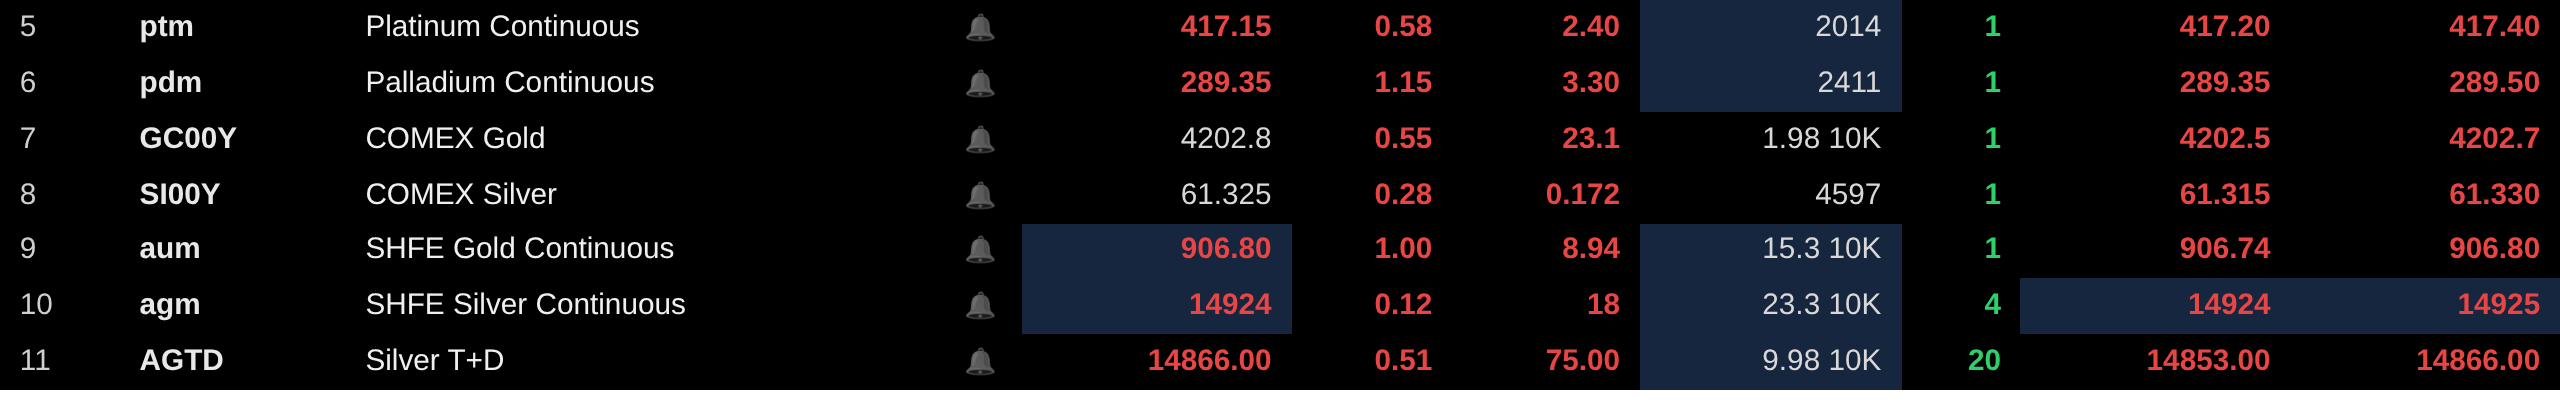
Boosted by the above factors, precious metals prices rebounded. As of 13:32 on September 30, COMEX gold rose 0.55% to $4,202.8/oz; SHFE gold main contract rose 1% to 906.8 yuan/g; COMEX silver rose 0.28% to $61.325/oz; SHFE silver main contract rose 0.12% to 14,294 yuan/kg; silver T+D rose 0.51% to 14,866 yuan/kg. In addition, platinum main futures rose 0.58% to 417.15 yuan/g, and palladium main contract rose 1.15% to 289.35 yuan/g.
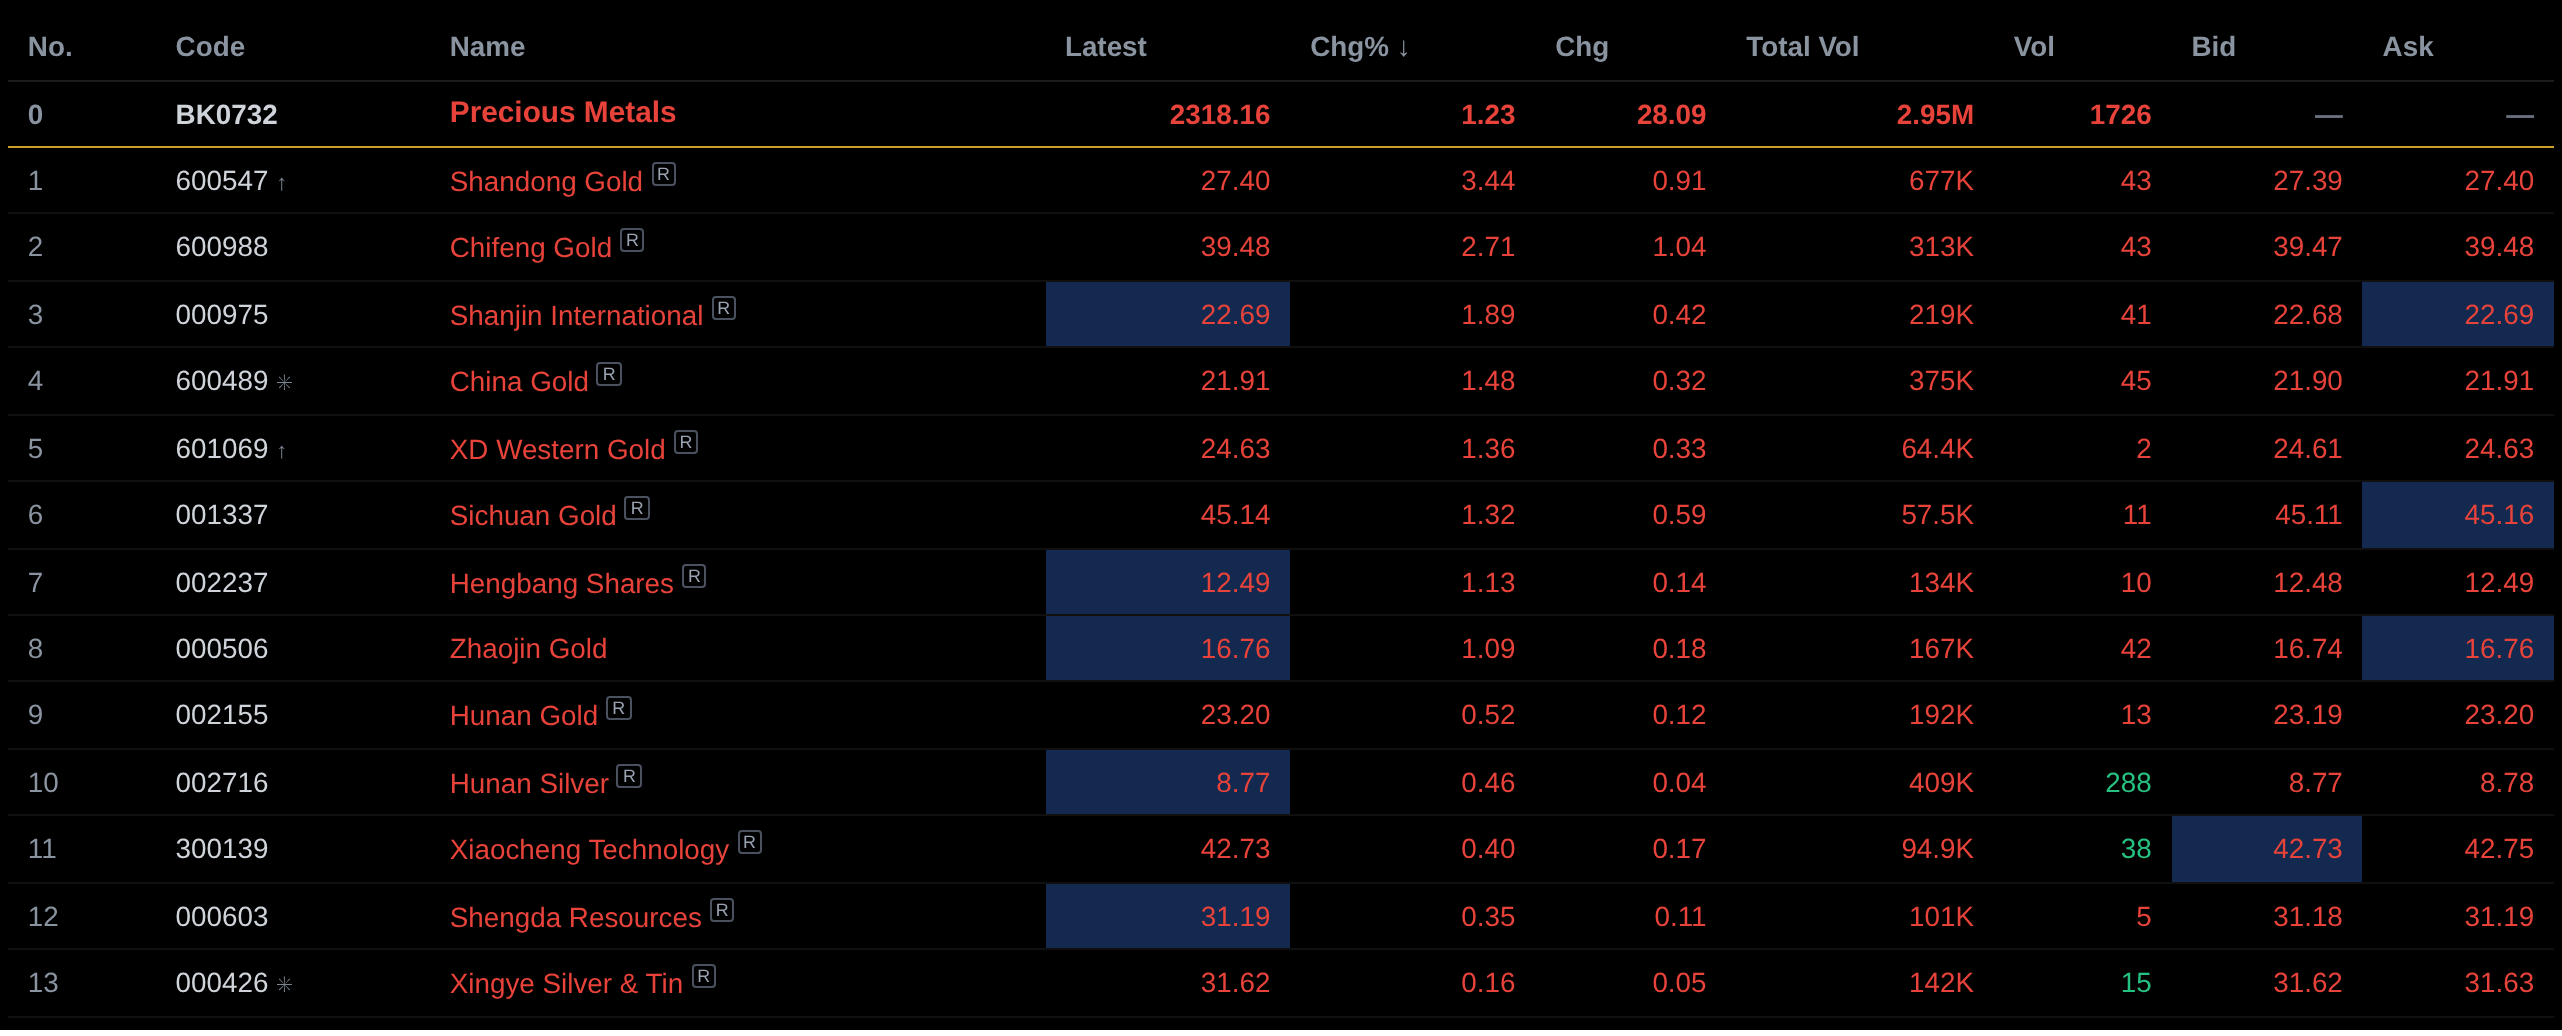
In the stock market: as of 13:38 on September 30, the precious metals sector rose 1.23%. Among individual stocks, Shandong Gold rose more than 3%, and Chifeng Gold, Shanjin International, Zhongjin Gold, and Western Gold were among the top gainers.
News
[Several Fed officials support further rate hikes; "No. 3" says another hike is needed this year but no rush, cooling October hike expectations] A number of Fed officials made intensive remarks on Tuesday, reinforcing expectations that further monetary tightening is still needed this year, but market bets on a near-term rate hike cooled somewhat. New York Fed President John Williams said in a speech in Buffalo, New York, that if the economy evolves broadly in line with his expectations, another rate hike later this year may be appropriate to bring inflation back to target in a more timely manner. At the same time, he stressed that the Fed's September rate hike has bought policymakers more time to observe, and "there is no need to rush." "Williams has clearly opposed the Fed making two consecutive rate hikes in October," analysts at Evercore ISI wrote in a note to clients. "We believe the most likely outcome is to skip October and hike in December."After Williams' remarks were released, market expectations for a rate hike at the Fed's October 27-28 meeting quickly pulled back from about 70% to around 50%.On Tuesday, three Fed officials sent similar signals on different occasions, reinforcing the market's judgment that policy still needs to be tightened. Fed Governor Michael Barr spoke in Detroit and again warned that controlling inflation may require further rate hikes.
Spot market
Silver
On September 30, the SMM #1 silver ex-factory reference average price in the morning edged up from the previous trading day.
In the spot market, the spot-futures price spread between the most-traded SHFE silver contract and the SGE silver T+D remained in the 50-60 yuan/kg range. On the last trading day before the National Day holiday, market trading was relatively sluggish, with some suppliers suspending quotations for the holiday or holding prices firm with symbolic quotations, resulting in a wide price spread in market quotes. Morning quotations in Shanghai were at discounts of 60-50 yuan/kg against the most-traded SHFE 2612 contract, or on par with to a premium of 10 yuan/kg against the SGE Ag (T+D), basically flat from the previous trading day. Some downstream buyers made normal inquiries and purchases, with ton-level and above transactions leaning toward parity on TD, while premium transactions were mainly small orders.
Overall, Fed officials' remarks drove down the probability of an October rate hike, and combined with falling oil prices, the macro pressure on precious metals eased slightly. The silver spot market was steeped in holiday sentiment with sluggish trading, and transactions were concentrated in the SGE Ag (T+D) parity to slight premium range.
Platinum
On September 30, the average spot price of platinum rose from the previous trading day.
In the spot market, mainstream quotations from platinum traders were concentrated at a discount of around 1 yuan/g against the PT 2612 contract, or at a premium of 0.5-1 yuan/kg against the PT 2610 contract. As the holiday approached, market trading sentiment was sluggish, with some suppliers suspending quotations for the holiday, and downstream purchases were mainly small-volume rigid demand. Overall, the platinum spot market was steeped in holiday sentiment with sluggish trading today.
Market voices
Regarding the future trend of precious metals, some institutions' views are as follows:
CSC Financial's research report stated that the University of Michigan 1-year inflation expectations released this Friday jumped from 4.0% to 4.6%, and Fed officials took turns releasing hawkish remarks. Hammack said "underlying inflation may be above target and policy must remain restrictive," and Schmid said "the Fed has still not resolved the inflation problem."Combined with the less-than-ideal US Treasury auction results, yields rose across all maturities. Fortunately, progress in US-Iran talks on a phased reopening of the Strait of Hormuz sent oil prices lower, pulling back short-end Treasury yields, while the long end remained strong on inflation expectations and supply logic. The shock from the September rate hike has passed, and gold has completed its bottom test. However, as a non-yielding asset, gold's upside is limited by elevated Treasury yields.
Minmetals Futures research noted: On Tuesday, influenced by Williams' dovish remarks, the market lowered its expectations for subsequent hawkish policy, and precious metals began a recovery after the prior sharp pullback. This week's PCE inflation data and US employment report will be the core variables for validating Fed policy expectations. If inflation and employment data remain resilient, hawkish market expectations may persist, and resistance above gold prices will not ease. If inflation data weaken, market pricing for further rate hikes is expected to cool, providing support for precious metals. Strategically, short-term observation is recommended. The most-traded SHFE gold contract is expected to trade in the 850-950 yuan/g range, and the most-traded SHFE silver contract in the 14,500-15,500 yuan/kg range.
Jinyuan Futures research believes: Yesterday, the latest US job openings came in below expectations, and Fed voter New York Fed President Williams signaled no urgency to raise rates. Market expectations for an October Fed rate hike pulled back, boosting gold and silver prices. US August JOLTS job openings fell to 7.079 million, the lowest in five months and the third consecutive month below expectations. The September consumer confidence index also fell to its lowest since 2014. The labor market's rigid characteristics of low hiring, low layoffs, and low turnover persist. Yesterday, multiple officials reiterated their hawkish stance. Fed Governor Barr expects further rate hikes will be needed to bring down inflation. However, Fed "third-in-command" New York Fed President Williams said there may be one more rate hike later this year but there is no need to rush. Market pricing for an October rate hike fell from about 70% to around 50%. On the Middle East situation, US-Iran negotiations have made little progress, with neither side willing to compromise. Market expectations for an October Fed rate hike have pulled back, but persistently tense Middle East geopolitics continue to push up inflation and support the hawkish direction. The adjustment in precious metals is expected to be not yet over. The National Day holiday is approaching, and heavyweight non-farm payrolls data will be released during the holiday. Gold and silver prices are expected to fluctuate significantly, so observation before the holiday is advisable.
Silver remains under pressure after Monday's sell-off, with futures prices hovering near $61/oz. Rising US Treasury yields and a stronger US dollar are weighing on this non-yielding asset. The former raises the opportunity cost of holding silver, while the latter makes silver more expensive for buyers outside China. Market expectations of another US rate hike in October further intensified pressure on silver. However, Zaye Capital Markets analyst Naeem Aslam said the long-term supply outlook remains supportive, with silver set to post a supply deficit for the sixth consecutive year and limited growth in mine supply. Industrial demand remains a key risk. Aslam said, "If yields soften and the US dollar weakens, silver could quickly find support, but if both stay high, the market may continue to test lower technical levels before a sustained recovery emerges." (Jin10 Data APP)
Everbright Futures research reports show: Looking ahead to Q4, the precious metals price center is expected to shift gradually higher, driven by multiple structural bullish factors, but the upside remains constrained by Warsh's "hawkish" policy stance. The first layer of logic lies in the re-anchoring of gold's pricing benchmark to "US dollar credit." Q3 already showed a divergence where "yields rose but gold prices did not fall." Geopolitical fragmentation, coupled with market concerns over US fiscal soundness and dollar credit, continues to fuel robust demand for alternative reserve assets. As the only metallic reserve asset, gold naturally enjoys strong favour. The second layer of logic comes from rigid central bank gold purchases. Global central bank gold buying in Q2 hit a quarterly record high, and the PBOC's monthly purchases from June to August were 480,000, 640,000, and 650,000 ounces respectively. This "buying more as prices fall" pattern, backed by strong central bank credit endorsement, forms the gold price's most solid floor support. The third layer of logic is event-driven catalysts from the midterm elections. With the November 3 US midterm elections approaching, Trump's repeated policy setbacks raise great uncertainty over whether Republicans can hold their ground and whether Democrats can regain control of Congress. US equities face the risk of a sharp reversal, risk assets are under pressure, and gold, as a safe-haven asset, may seek progress amid stability. Risks to watch include the fact that Warsh's "hawkish" thinking has not shifted significantly. If inflation does not return to a downward path, a second rate hike this year could land in December, and gold prices may face periodic pullback pressure. Overall, in early-to-mid Q4, gold may continue to show a slow recovery, and gold prices are expected to retest the market buying sentiment at $4,800-$5,000/oz, but caution is warranted in mid-to-late Q4. The market may turn to a wait-and-see stance or even pull back again due to the Fed's December policy stance and uncertainty over next year's monetary policy.
KCM Trade chief market analyst Tim Waterer said, "The combination of high bond yields and high oil prices continues to pressure gold. Oil prices rose due to uncertainty over the oil supply outlook, bringing inflation back into focus for investors. "Investors will watch a slew of US employment and inflation data this week, including job openings, the ADP employment report, the PCE inflation report, and the nonfarm payrolls report. Waterer said, "If inflation or employment data come in stronger than expected, it could continue to push bond yields higher and further weigh on gold prices." (Jin10 Data APP)
Mitsubishi UFJ analysts said, "Fed officials also maintained a hawkish stance, with Governor Barr saying further policy tightening may be needed. With the market now pricing in at least three more rate hikes by April, elevated yields and persistent energy-driven inflation remain significant headwinds for gold." (Jin10 Data APP)
Intesa Sanpaolo economist Daniela Corsini said in a report, "In our baseline scenario, we expect the precious metals market to lack clear direction, though volatility may continue to stay high. Gold prices may continue to fluctuate around an average of about $4,200 per ounce over the coming quarters."
Recommended reading:
►
►
►