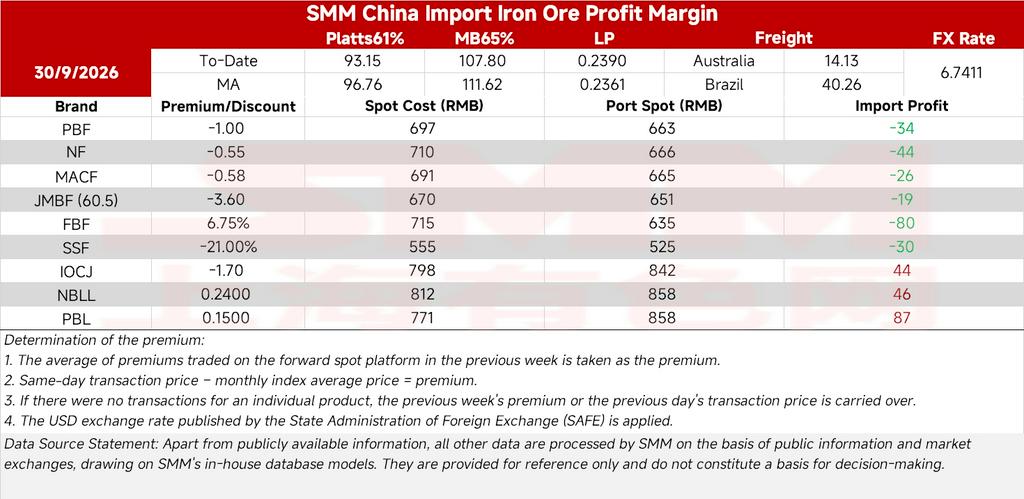
The average imported iron ore margin narrowed from -5.08 yuan/mt to -6.12 yuan/mt this period, dragged down by a modest decline in spot prices.
Iron ore demand remains weak. SMM data showed hot metal output lost to blast furnace maintenance at 1.6288 million mt this week (26 September to 2 October), up 35,800 mt week on week. The figure is expected to rise further to 1.6839 million mt next week (3 to 9 October), up 55,100 mt.
On the news front, market talk points to a first round of coke price cuts, expected to take effect in early October. That would ease cost pressure on mills and could loosen the constraint that has been weighing on iron ore procurement. With iron ore still lacking bullish drivers, however, prices are likely to stay soft within a range in the near term, and imported margins are likely to narrow further.