The coke market in September maintained high‑level stalemate with slowing price gains. The core conflict lay in the interplay between cost support from coking coal and restraint stemming from steel mill losses. Following several rounds of price hikes implemented in early September, losses at coking enterprises narrowed, and coking operating rates edged higher. On the supply side, ongoing safety supervision at coal mines in major producing regions kept high‑grade primary coking coal relatively tight, forming floor support for coke. Coking enterprises held low inventories in the early period and showed strong willingness to defend prices. On the demand side, hot‑metal output stayed elevated, coupled with rigid restocking by steel mills ahead of the National Day holiday, which underpinned spot prices on a temporary basis. Nevertheless, end‑user finished‑steel demand under the traditional “Golden September” failed to meet expectations. Steel mill profitability kept deteriorating, raising resistance to high‑priced coke. The sixth round of proposed price hikes failed to materialize. Mid‑to‑late September saw the market shift from a price‑rising phase to sideways consolidation, with limited room for further price advances. Toward month‑end, pre‑holiday restocking wound down, shipments from coking enterprises slowed, and industrial‑chain inventories built up marginally. The market began pricing in blast‑furnace maintenance at steel mills and expectations for the first round of coke price cuts. Overall, coke price levels moved higher in September yet upward momentum gradually ebbed. Profit recovery for coking enterprises brought about marginal supply release, while downstream steel mills faced mounting loss pressure. The tight supply‑demand balance loosened marginally, and market logic shifted from supply contraction to demand‑side validation.
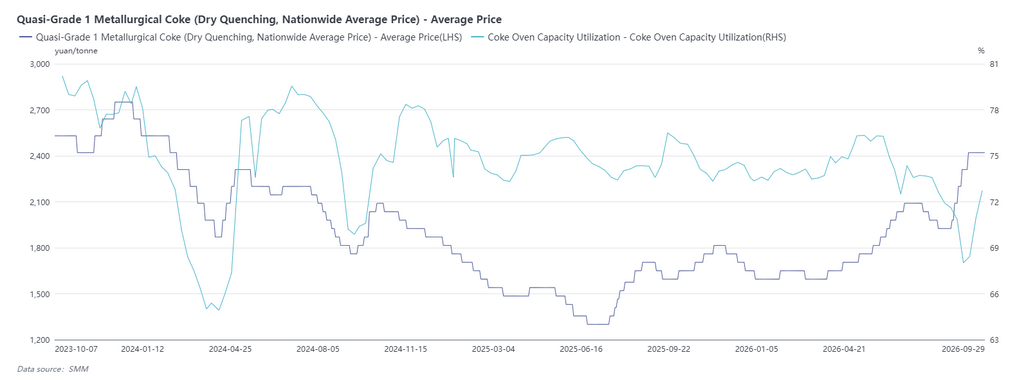
Looking ahead to October, coke will most likely trend sideways‑to‑weaker with risks of periodic corrections. On the supply side, coking enterprises retain flexible operating rates after profit improvements in September. Should prices stay high, coke output may see further increases. On the coking‑coal front, previously constrained mines resume production in an orderly manner, easing tightness in coking‑coal supplies and weakening cost support. Demand will serve as the core driver shaping market performance. In October, should end‑user steel demand for the traditional “Silver October” continue to disappoint, steel‑mill losses will persist, the scope of blast‑furnace maintenance may expand, hot‑metal output will decline, and rigid coke demand will recede. After the National Day holiday, pre‑holiday restocking by steel mills will be complete. Proactive purchasing sentiment will cool, steel mills will be more inclined to push coke prices lower, and steel mills will gain greater pricing power. From an inventory perspective, industrial‑chain inventories are expected to build after pre‑holiday restocking, adding further downward pressure on spot prices. That said, uncertainties remain surrounding coal‑mine safety inspections. Should safety supervision tighten anew, coking coal and coke prices will receive periodic support, limiting the scope of sharp declines.