SMM, September 26:
Metals market:
Last Friday overnight, the domestic base metals market was closed for the Mid-Autumn Festival holiday.
Last Friday overnight, the ferrous metals market was closed for the Mid-Autumn Festival holiday.
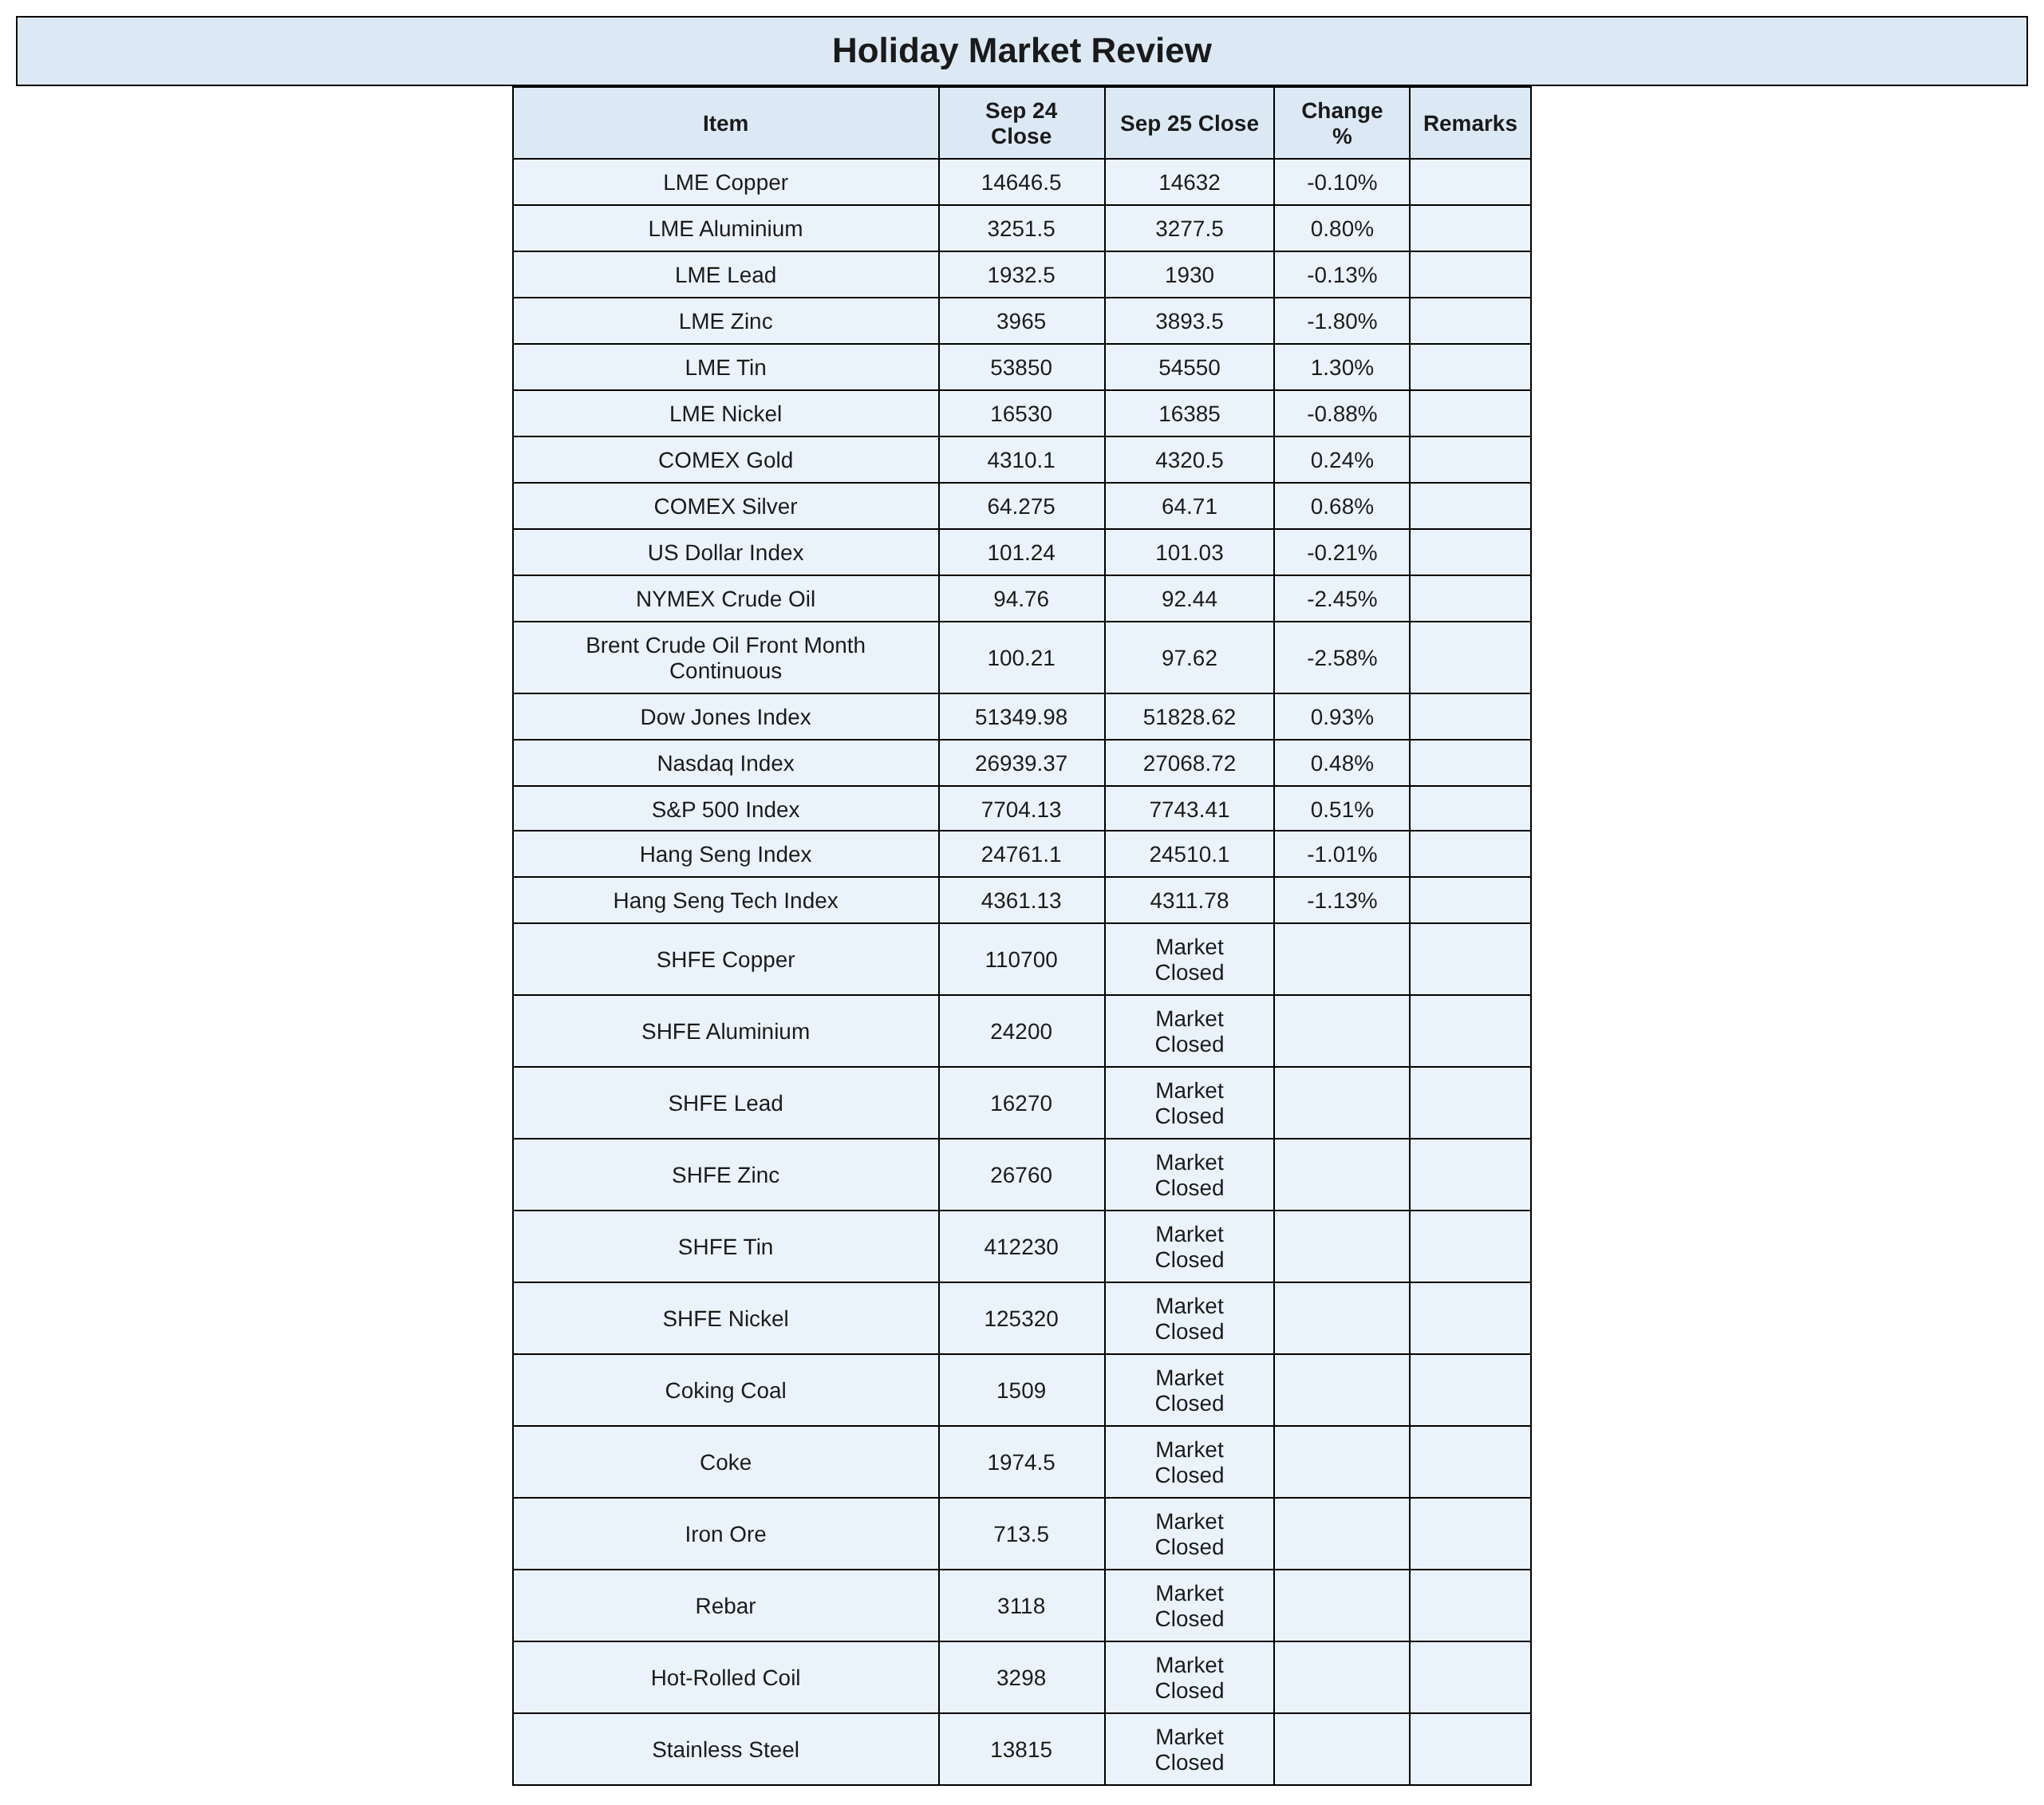
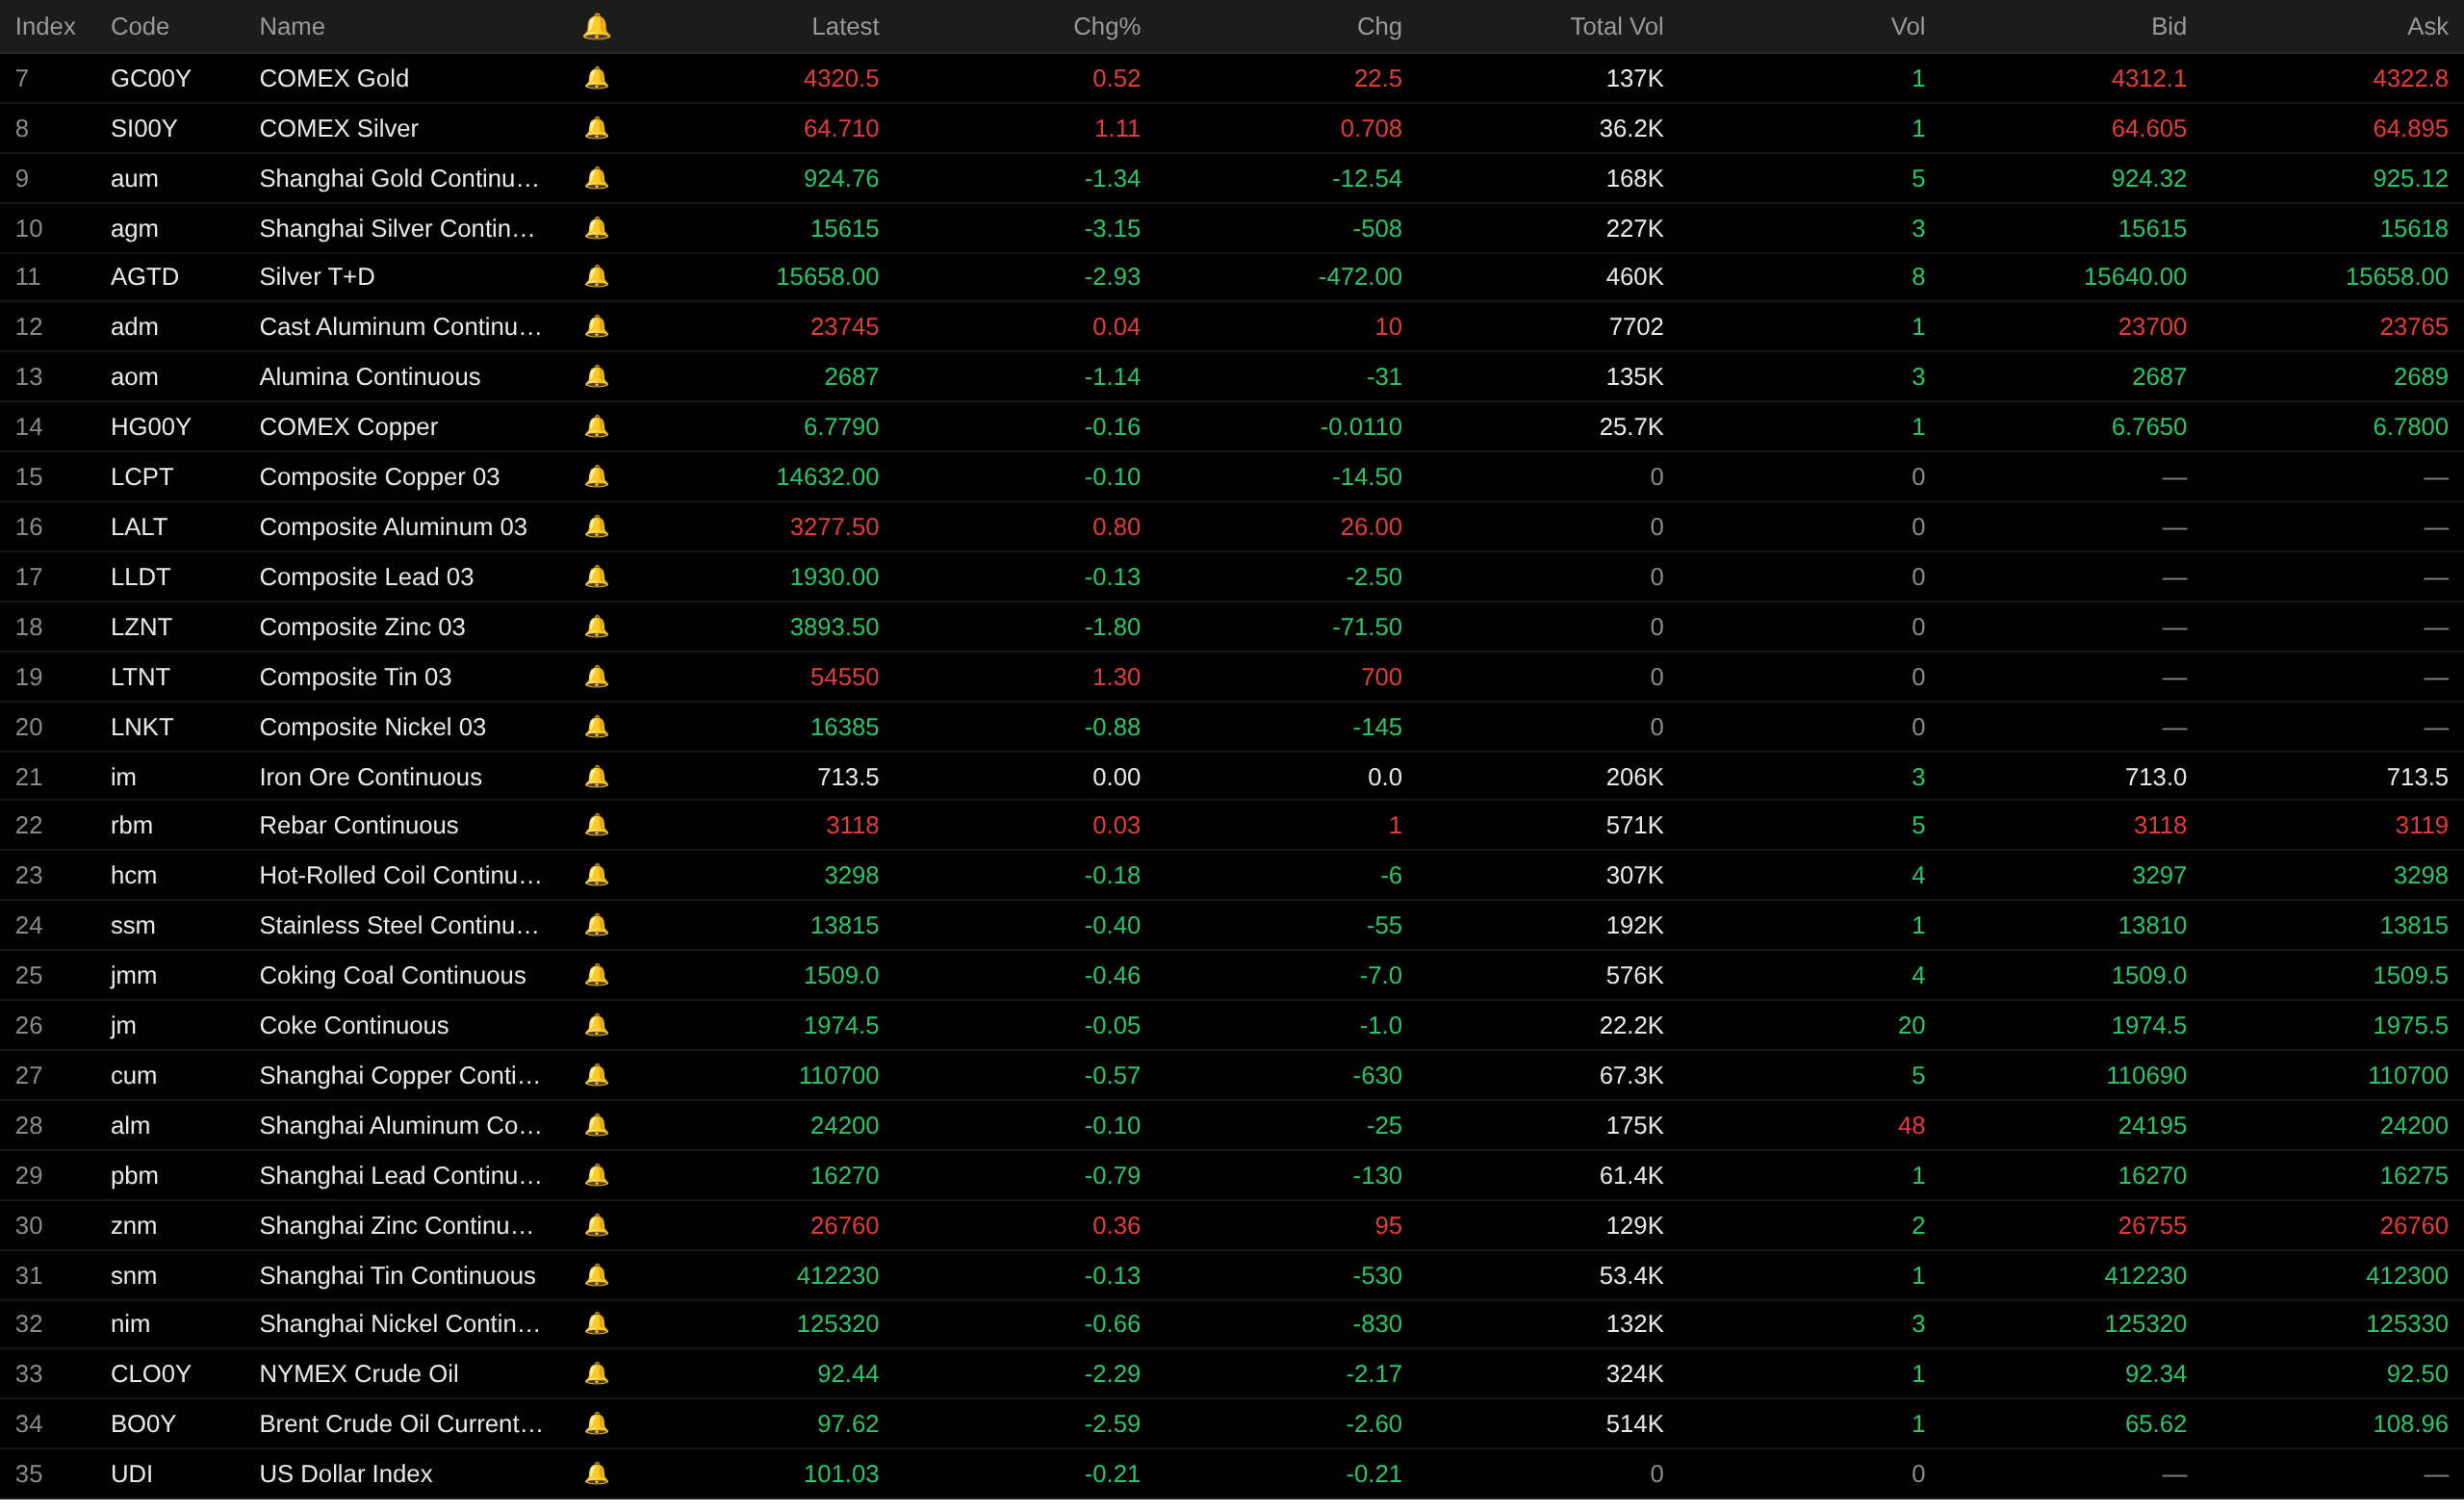
Last Friday overnight in the overseas metals market, LME base metals broadly declined. LME copper fell 0.1%, LME aluminum rose 0.8%. LME lead fell 0.13%. LME zinc fell 1.8%. LME tin rose 1.3%. LME nickel fell 0.88%.
Last Friday overnight in the precious metals market: COMEX gold rose 0.52%, with COMEX gold posting a weekly decline of 2.36%; COMEX silver rose 1.11%, with COMEX silver posting a weekly decline of 3.63%. Last Friday overnight, the SHFE gold main contract was closed for the Mid-Autumn Festival holiday, with SHFE gold posting a weekly decline of 1.97%; the SHFE silver main contract was closed for the Mid-Autumn Festival holiday, with SHFE silver posting a weekly decline of 2.75%.
Other financial markets:
In addition, US stocks: On Friday, September 25, US stocks drifted higher. Intraday volatility in early trading was notably driven by US economic data. After the final reading of the University of Michigan consumer sentiment index for September was released, the S&P 500 and Nasdaq both briefly turned lower, and the Dow gave back most of its gains. Shortly thereafter, the three major indices regained their upward momentum, with the Dow snapping a three-day losing streak. As of the close on September 25, the Dow Jones Industrial Average rose 0.93% to 51,828.62 points; the Nasdaq Composite rose 0.48% to 27,068.72 points; the S&P 500 rose 0.51% to 7,743.41 points.
Hong Kong stocks: As of the close on September 25, the Hang Seng Index fell 1.01% to 24,510.09 points; the Hang Seng Tech Index fell 1.13% to 4,311.78 points.
As of 8:15 a.m. on September 26, last Friday's overnight closing prices:
Macro front
China:
[On the first day of the Mid-Autumn Festival holiday, cross-regional passenger trips nationwide exceeded 243 million] According to the latest data from the Ministry of Transport, on the first day of the Mid-Autumn Festival holiday, cross-regional passenger trips nationwide were expected to exceed 243 million, up 6.4% from the previous day. Passenger flows on highways, railways, civil aviation, and waterways all increased notably, and transport authorities added capacity to ensure orderly travel. (CCTV)
[HKEX's derivatives clearing houses to accept China government bonds, policy bank bonds, and MOF bonds as non-cash collateral from November] Hong Kong Exchanges and Clearing Limited (HKEX) announced today (Friday) that its wholly-owned subsidiaries and on-exchange derivatives clearing houses, HKFE Clearing Corporation Limited (HKCC) and The SEHK Options Clearing House Limited (SEOCH), will, from November 2026, accept China government bonds and policy bank bonds held through Bond Connect "Northbound Trading" (collectively, Bond Connect bonds), as well as offshore bonds issued by the Ministry of Finance of the People's Republic of China (MOF bonds), as eligible non-cash collateral for margin requirements, subject to regulatory approval. Bonnie Liu, Chief Operating Officer of HKEX, said the implementation of this enhancement will increase the use cases for China government bonds in the Hong Kong market. By accepting these bonds as collateral for meeting clearing house margin requirements, HKEX will help provide market participants with more flexible collateral management options, improve capital efficiency, and promote the continued development of Hong Kong's fixed income and RMB ecosystem. (Jin10 Data APP)
US dollar:
The overnight US dollar index fell 0.21% last Friday to 101.03. Weekly: The US dollar index posted two consecutive weekly gains, rising 0.81% for the week.
Data: University of Michigan survey data showed US consumers' assessments of their current and future personal finances both fell about 10%, with concerns over high prices continuing to intensify. Durable goods purchasing conditions improved slightly, partly because consumers believe completing such purchases now helps avoid future price increases. Consumer expectations for short-term business conditions deteriorated sharply amid renewed concerns over high fuel prices and the potential spillover of escalating trade disputes into the broader economy. Overall, the survey showed respondents across political affiliations broadly agreed that the US economic outlook has weakened compared with the start of the year. After this month's sharp drop in consumer confidence, sentiment among Republicans fell 20% from January 2026, while sentiment among Democrats fell 13% over the same period. One-year-ahead inflation expectations rose to 4.6% this month from 4.0% last month, the highest since June. This level is now notably above the 3.4% recorded in February before the Iran conflict began, and above all monthly readings in 2024. Long-term inflation expectations edged up to 3.4%, ending three consecutive months at 3.3%. This expectation remains above the 2.8% to 3.2% range seen in 2024. (Jin10 Data APP)
A gauge of US Treasury volatility is heading for its biggest gain in more than a year after bond yields climbed to multi-decade highs, shaking the market out of its recent lull. ICE BofA's MOVE index, a measure of bond market volatility, has risen about 29.69% this week, the largest gain since last April's so-called "Liberation Day," when Trump's sweeping import tariffs triggered global market turmoil. The index has now climbed to its highest level since March this year, when the Iran war first broke out. The market has swung wildly, and many traders have opted to stay on the sidelines. For example, Adam Kurpiel, head of rates strategy at Societe Generale, said his team currently holds a neutral view on US rates and is waiting for "volatility to decline before trading." (Jin10 Data APP)
Cleveland Fed President Beth Hammack said the recent sharp rise in US Treasury yields was not driven by a loss of confidence in the pullback of inflation, but primarily by higher real rates, a strong economic outlook, fiscal policy, and competition for investor funds. She said inflation expectations remain "fairly well anchored" at present, but inflation that remains persistently above the Fed's 2% target still imposes real costs and may affect economic planning and wage pressures. Hammack said the biggest risk to inflation right now is the formation of an "inflation mentality," where the public begins to believe high inflation will persist over the long term. She noted that inflation has been above target for several consecutive years, and the Fed needs to ensure monetary policy remains restrictive to drive inflation back to the 2% target. On the bond market, Hammack said the rise in yields partly reflects market repricing of Fed policy and government fiscal policy, while investment demand in the AI and technology sectors is also competing with the bond market for investment funds. She also said the current US fiscal path is unsustainable. (Jin10 Data APP)
Apollo Global Management Chief Economist Torsten Slok warned that the inflationary threat from record diesel prices could exceed the Fed's current expectations, as fuel costs are feeding through into the core consumer price index. Slok said diesel-related transportation costs differ from the impact of gasoline prices. Because transporting goods is critical to economic activity, from retail supply chains to data center construction, demand is highly inelastic, and price increases will ultimately be passed on to enterprises and consumers. The impact of rising diesel prices is particularly critical as the Fed formulates monetary policy after its first rate hike since 2023. Inflation remains significantly above the central bank's 2% target. The so-called core inflation measure strips out energy factors, and Slok believes the Fed cannot simply treat rising diesel prices as a temporary phenomenon, because they affect core inflation categories through spillover effects. (Jin10 Data APP)
On the macro front:
This week will see the release of China's August year-to-date industrial profits above designated size YoY, the US September Dallas Fed business activity index, Australia's RBA rate decision through September 29, Switzerland's September KOF economic leading indicators, UK August mortgage approvals, Eurozone September industrial sentiment, Eurozone September economic sentiment, Canada July GDP MoM, US July FHFA house price index MoM, US July S&P/CS 20-city unadjusted house price index YoY, US August JOLTs job openings, US September Conference Board consumer confidence, China September official manufacturing PMI, Australia August unadjusted CPI YoY, China September RatingDog manufacturing PMI, China September RatingDog services PMI, UK Q2 GDP final YoY, UK Q2 current account, France September CPI preliminary MoM, Germany September seasonally adjusted unemployment change, Germany September seasonally adjusted unemployment rate, Switzerland September ZEW investor confidence, Germany September CPI preliminary MoM, US September ADP employment change, US August core PCE price index YoY, US August personal spending MoM, US Q2 real GDP annualized QoQ final, US Q2 real personal consumption expenditures QoQ final, US Q2 core PCE price index annualized QoQ final, US August core PCE price index MoM, US September Chicago PMI, Switzerland September CPI MoM, Switzerland August real retail sales YoY, France September manufacturing PMI final, Germany September manufacturing PMI final, Eurozone September manufacturing PMI final, UK September manufacturing PMI final, Eurozone August unemployment rate, US September Challenger job cuts, US initial jobless claims for the week ending September 26, US September S&P Global manufacturing PMI final, US September ISM manufacturing PMI, US August construction spending MoM, Japan August unemployment rate, Eurozone September CPI preliminary YoY, Eurozone September CPI preliminary MoM, US September unemployment rate, US September seasonally adjusted nonfarm payrolls, US September average hourly earnings YoY, US September average hourly earnings MoM, US August factory orders MoM, and other data.
In addition, this week, attention should also be paid to: Bank of England Deputy Governor Ramsden speaking on quantitative tightening; the Reserve Bank of Australia announcing its interest rate decision; RBA Governor Bullock holding a monetary policy press conference; 2027 FOMC voting member and Chicago Fed President Goolsbee speaking; 2028 FOMC voting member and St. Louis Fed President Musalem speaking at the London School of Economics; FOMC permanent voting member and New York Fed President Williams delivering a keynote speech at the University at Buffalo; 2027 FOMC voting member and Richmond Fed President Barkin delivering welcome remarks at an event; Fed Governor Lisa Cook speaking; 2027 FOMC voting member and Chicago Fed President Goolsbee speaking; 2026 FOMC voting member and Minneapolis Fed President Kashkari speaking; the Bank of Japan releasing the summary of opinions from the September monetary policy meeting; Bank of England Governor Bailey speaking; Richmond Fed President Barkin, Boston Fed President Collins, and Kansas City Fed President Schmid speaking; ECB President Lagarde speaking; FOMC permanent voting member and New York Fed President Williams moderating a discussion at a central bank symposium hosted by the New York Fed, with Fed Governor Lisa Cook attending the same discussion; 2026 FOMC voting member and Dallas Fed President Logan speaking; 2026 FOMC voting member and Dallas Fed President Logan delivering welcome remarks at the fifth "Macroeconomic Implications of Migration" symposium.
It is worth noting that: On September 30, China's SGE, SHFE, Zhengzhou Commodity Exchange, and DCE will have no night session due to the eve of the National Day holiday; on October 1, the Hong Kong Stock Exchange will be closed for one day for National Day, with northbound and southbound trading suspended; China's Shanghai and Shenzhen stock exchanges, Beijing Stock Exchange, and domestic futures exchanges will be closed from Thursday, October 1 to Wednesday, October 7 for National Day; on October 2, October 5, October 6, and October 7, the Hong Kong Stock Exchange will be open as usual, with northbound and southbound trading suspended.
On the crude oil front:
Last Friday, both oil futures fell in overnight trading, with WTI down 2.29% and Brent down 2.59%. On the weekly chart: WTI futures posted a second consecutive weekly decline, falling 3.79% for the week; Brent posted a second consecutive weekly decline, falling 1.68% for the week.
Oil prices fell on Friday as the market assessed the possibility of US-Iran ceasefire talks while also worrying that escalating Houthi attacks on Saudi Arabia could disrupt supply from this major Middle Eastern oil producer. The market had just experienced a week of wild swings. According to sources close to the discussions, US and Iranian negotiators meeting in New York this week have explored a phased path to ending the conflict, including Tehran reopening the Strait of Hormuz and Washington lifting its economic blockade on Iran. Iranian President Pezeshkian said on Thursday that when the war ends still depends on the US decision. In any case, vessel traffic data released by Reuters still shows that the situation on the physical supply side remains fragile. On Wednesday, only 10 commodity vessels passed through the Strait of Hormuz, up from 7 the previous day but still significantly below the daily average of about 17 over the past 10 days. Positive news on diplomatic progress may help oil prices shed some of the geopolitical premium, but shipping data still indicates that any true normalization is still some distance away. (Jin10 Data APP)
On September 25 local time, a US official revealed that the US is engaged in "active and constructive" discussions with Iran following Iran's plan to reopen the Strait of Hormuz and resume negotiations after the proposal is accepted. The official said the US is in no rush, as it is currently in a favorable position; he noted that in the past 48 hours, nearly 40 million barrels of oil have passed through the Strait of Hormuz under US escort. (CCTV)
According to people familiar with the matter, Iraq's state marketing company is offering last-minute crude cargoes to buyers, as high freight costs complicate purchases from the deep Persian Gulf. Given its geographic distance from the Strait of Hormuz, Iraq faces more difficulties in transportation than some neighboring countries and instead relies on trading firms to market and transport its crude. It has offered steep discounts to incentivize buyers, lowering prices for Basrah Medium and Heavy crude in recent tenders. (Jin10 Data APP)
In addition, Russia's seventh-largest refinery by crude processing volume, the Perm refinery, has halted operations after a Ukrainian drone attack. Two industry sources said the attack sparked a fire on Friday and caused damage to pipelines, storage facilities, and process units. The refinery is located about 1,460 km (907 miles) northeast of Moscow and processed about 12.6 million mt of crude in 2024, or 252,000 barrels per day; it produced 2 million mt of gasoline, 5.3 million mt of diesel, 200,000 mt of fuel oil, and 700,000 mt of petroleum coke. (Jin10 Data APP)
Recommended reading: