[SMM Rebar Daily Review] Building materials fundamentals continue to improve but with limited drivers, short-term steel prices may maintain a fluctuating trend

Published: Sep 24, 2026 17:21 (GMT+8)

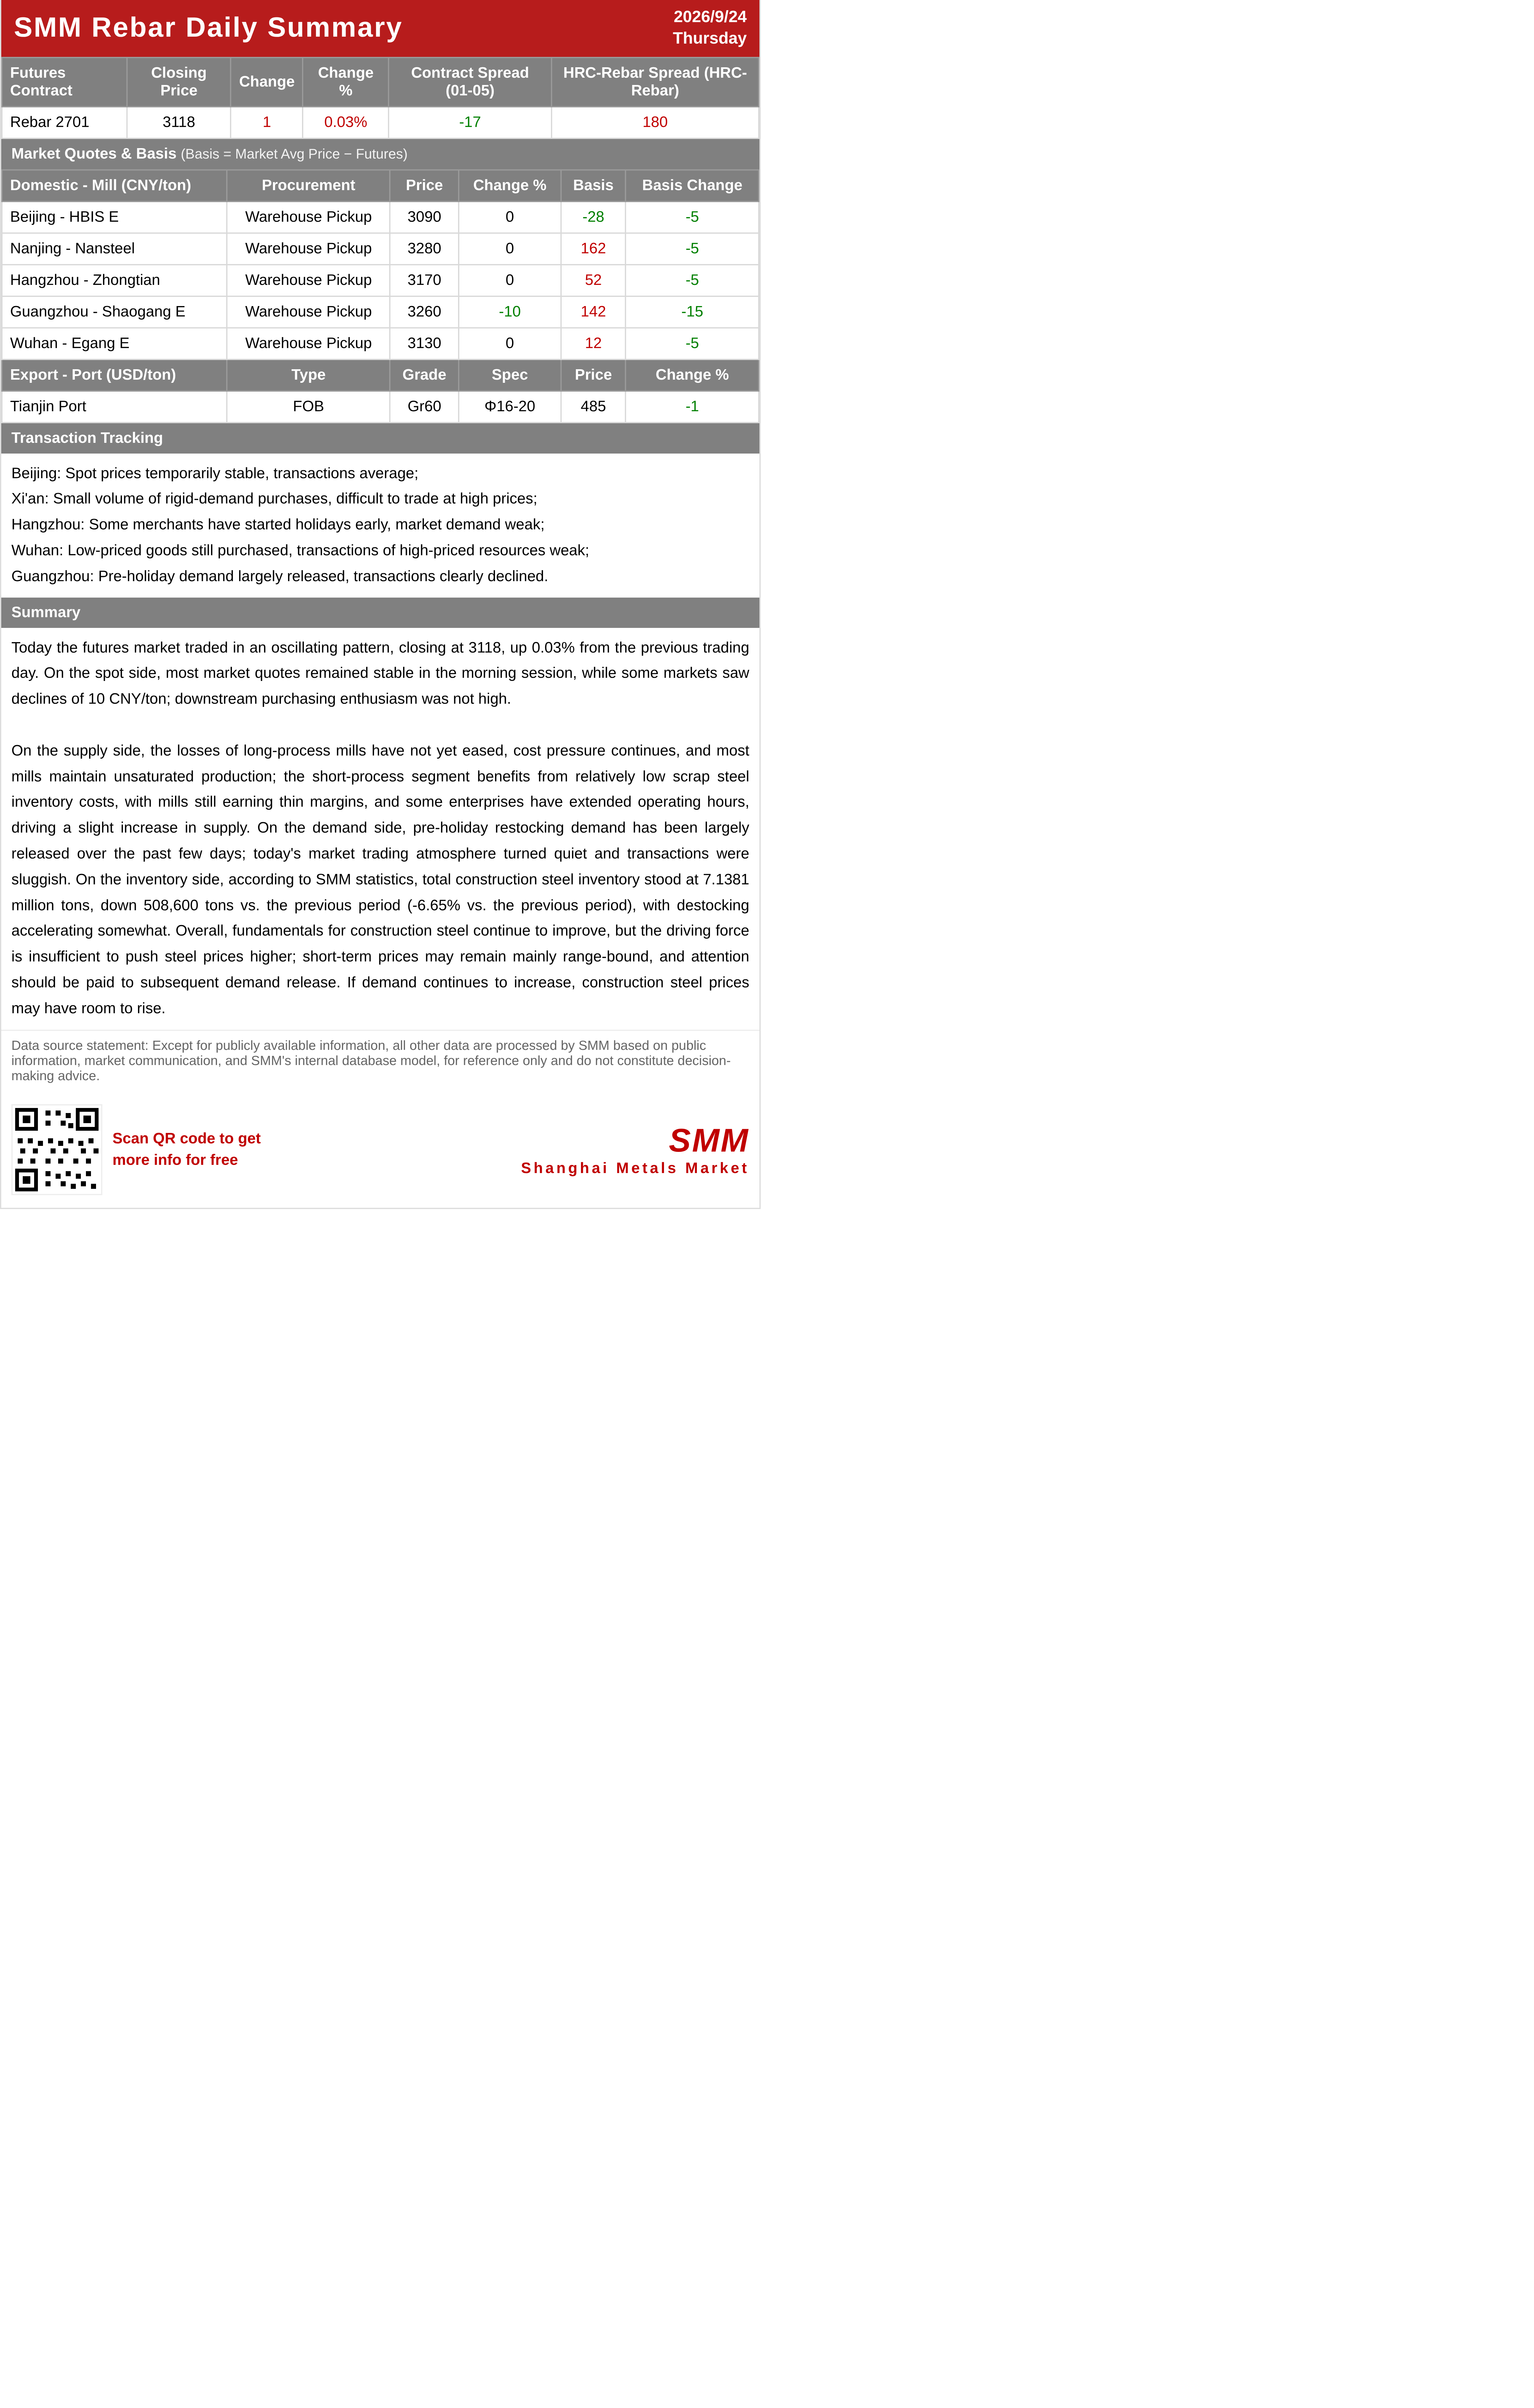
Futures consolidated today, closing at 3,118, up 0.03% from the previous trading day. In the spot market, most quotes were stable in early trading, while some markets saw declines of 10 yuan/mt, with downstream purchases remaining sluggish.
Supply side, blast furnace steel mills are still grappling with losses, with the cost side under persistent pressure, and most mills maintaining unsaturated production. On the EAF side, mills still have thin margins thanks to lower-cost steel scrap stocked earlier, and some enterprises have extended operating hours, driving a slight increase in supply. Demand side, pre-holiday restocking demand was largely released in the previous days, and today's market activity turned sluggish, with lackluster transactions. Inventory side, according to SMM statistics, total construction steel inventory stood at 7.1381 million mt, down 508,600 mt WoW, or -6.65% WoW, with destocking accelerating. Overall, construction steel fundamentals continue to improve, but the driving force is not enough to push steel prices higher. In the short term, prices are likely to consolidate, with attention needed on subsequent demand releases. If demand continues to increase, construction steel prices may have room to rise.
Data Source Statement: Except for publicly available information, all other data are processed by SMM based on publicly available information, market communication, and relying on SMM's internal database model. They are for reference only and do not constitute decision-making recommendations.

Images in this article contain AI-translated captions for reference only.

For any inquiries or for more information, please contact: lemonzhao@smm.cn
For more information on how to access our research reports, please contact:service.en@smm.cn
Related News
Maintenance Increase Coincides With Restocking End, Iron Ore Demand Faces Significant Contraction [SMM Iron Ore Daily Review]
20 mins ago
Maintenance Increase Coincides With Restocking End, Iron Ore Demand Faces Significant Contraction [SMM Iron Ore Daily Review]
Read More
Maintenance Increase Coincides With Restocking End, Iron Ore Demand Faces Significant Contraction [SMM Iron Ore Daily Review]
20 mins ago
Heavier maintenance and the end of restocking point to sharply weaker iron ore demand 【 SMM Daily Iron Ore Brief】
21 mins ago
Heavier maintenance and the end of restocking point to sharply weaker iron ore demand 【 SMM Daily Iron Ore Brief】
Read More
Heavier maintenance and the end of restocking point to sharply weaker iron ore demand 【 SMM Daily Iron Ore Brief】
21 mins ago
HRC Prices Flat, Pre-Holiday Restocking Boosts Demand; Inventories Down, Prices to Hold Firm Next Week
23 mins ago
HRC Prices Flat, Pre-Holiday Restocking Boosts Demand; Inventories Down, Prices to Hold Firm Next Week
Read More
HRC Prices Flat, Pre-Holiday Restocking Boosts Demand; Inventories Down, Prices to Hold Firm Next Week
This week, HRC prices were basically flat WoW, while overall transactions increased from the previous week. Supply side, the impact from rolling line maintenance decreased MoM, and overall HRC production rebounded. Demand side, pre-holiday restocking demand surged, driving apparent demand up WoW. Inventory side, this week SMM's nationwide HRC social inventory across 86 warehouses (large sample) stood at 4.5356 million mt, down 116,200 mt WoW, or -2.5% WoW, and up 23.27% YoY. By region, inventories across the country declined to varying degrees, with central China and north China seeing the most notable drops. Cost side, the cost side showed no significant fluctuations this week. Looking ahead, the current peak-season demand trend remains weak, and steel mills and traders are under price pressure. However, with the Mid-Autumn Festival and National Day holidays combined, the extended break still provides support from pre-holiday restocking demand. Prices are expected to hold firm and consolidate around current levels, with the most-traded contract likely to trade in the 3,270-3,340 range.
23 mins ago
Register to Continue Reading
Gain access to the latest insights in metals and new energy
Already have an account?Sign in here