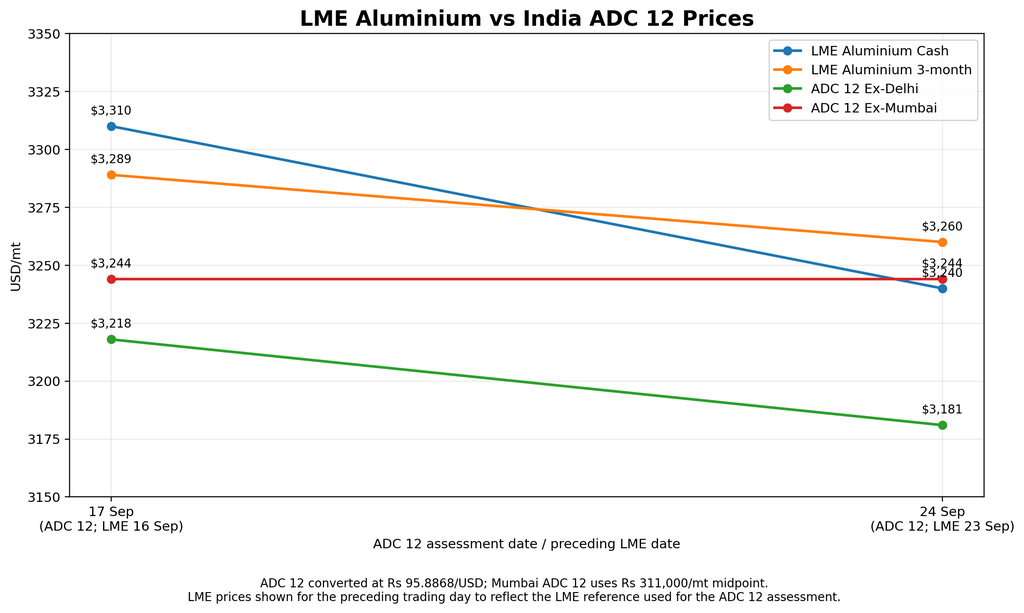
Indian ADC 12 sentiment was mixed to slightly weaker this week. In Delhi, ADC 12 prices eased to Rs 305,000/mt ($3,181/mt) on September 24 from Rs 308,500/mt ($3,218/mt) a week earlier, following a reduction in the procurement price of a major northern Indian automotive OEM to Rs 305,000/mt from Rs 317,000/mt. The OEM is estimated to consume around 12,000 mt/month. Market participants said the lower OEM purchase price encouraged smaller downstream producers to seek discounted material, putting further pressure on Delhi prices.
In Mumbai, ADC 12 prices remained at Rs 310,000–312,000/mt ($3,233–3,254/mt), averaging Rs 311,000/mt ($3,244/mt), supported by restocking ahead of the festive season. However, market participants in western India expect prices to come under pressure as input costs decline. Domestic Purja/general scrap prices fell to around Rs 250,000/mt ($2,607/mt), while auto scrap declined to Rs 254,000/mt ($2,649/mt), from Rs 254,000–259,000/mt a week earlier.
Export sentiment remained subdued. Indian ADC 12 offers to Japan were heard at $3,080–3,100/mt, down from $3,100–3,125/mt a week earlier, while Japanese buyers showed limited enthusiasm at current levels. China-origin ADC 12 CIF Japan was assessed at $3,090–3,110/mt, averaging $3,100/mt, unchanged from the previous week.
Thailand FOB ADC 12 was assessed at $3,120/mt, up $5/mt from the previous week, while Malaysia FOB ADC 12 was also assessed at $3,120/mt, unchanged week on week. Indian export offers were therefore broadly aligned with regional FOB levels, while China-origin CIF Japan prices remained slightly lower.
The weaker underlying aluminium market also capped upside. The LME aluminium price used as the reference for the September 17 ADC 12 assessment was $3,310/mt for Cash and $3,289/mt for 3-month aluminium on September 16, with Cash trading at a $21/mt premium, indicating backwardation. For the September 24 ADC 12 assessment, the September 23 LME aluminium prices were $3,240/mt for Cash and $3,260/mt for 3-month aluminium, putting Cash at a $20/mt discount, indicating contango. Thus, the LME Cash price fell $70/mt, or 2.1%, over the reference period, while the Cash-3M structure shifted by $41/mt, from $21/mt backwardation to $20/mt contango.
Despite the weaker LME aluminium market, lower OEM procurement prices and subdued Japanese buying interest, Mumbai ADC 12 prices remained relatively resilient, supported by festive-season restocking. However, the shift in the LME aluminium curve into contango, together with lower domestic scrap costs, suggests increasing pressure on ADC 12 prices, particularly in northern India, where OEM-linked pricing is more influential.
($1=Rs95.89)