

After the 2026 HRC-rebar price spread shot up to its yearly high in August, it has pulled back over the past month, driven mainly by a shift in the relative strength of cold- and hot-rolled demand and adjustments in steel mill supply structures.
In August, the market traded on the logic of a weak property sector and resilient manufacturing, supported by export orders for sheets & plates, which pushed HRC significantly stronger than rebar and drove the spread higher. Entering September, the traditional September peak season gradually materialized, with infrastructure rush to meet deadlines boosting rebar apparent demand, construction site transactions recovering, and rebar inventory destocking accelerating. In contrast, HRC faced overseas trade barriers weighing on exports, while orders from the automobile and home appliance manufacturing sectors fell short of expectations, leading to weakening downstream demand and a lack of upward momentum in HRC prices. Meanwhile, the previously elevated spread incentivized steel mills to reallocate hot metal, increasing HRC production, while sustained losses in rebar led to production cuts. This shift in supply and demand dynamics drove the spread to narrow from highs.
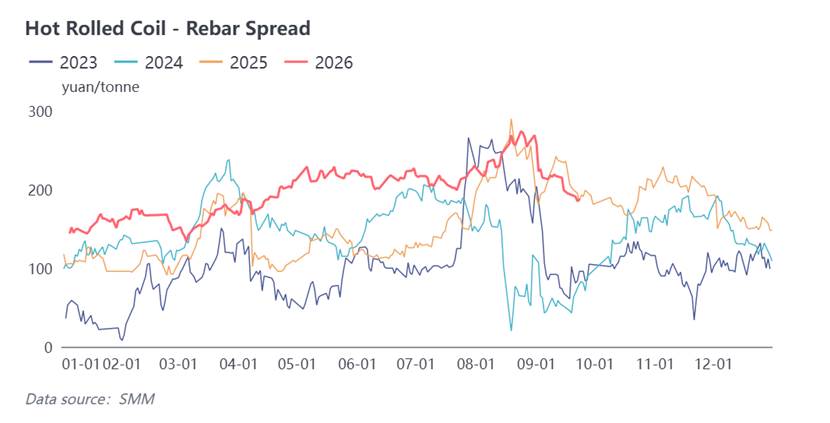
Looking ahead to October, the HRC-rebar price spread is likely to maintain a fluctuating trend with a drifting lower center, making a return to August highs difficult. On the demand side, October remains a window for infrastructure construction, but falling temperatures in northern China will gradually limit site activity, weakening rebar demand growth MoM. For HRC, downstream manufacturing is unlikely to see a stronger-than-expected recovery, and export pressure persists. On the supply side, the supply pressure from earlier steel mill shifts to HRC production will continue to be released, while rebar production resumptions as profits recover will further compress the spread.
However, downside in the spread has bottom support, as HRC rolling costs are naturally higher than rebar, with a historical reasonable center of around 120-180 yuan/mt, making a significant inversion unlikely. Overall, the HRC-rebar price spread in October is expected to consolidate within the 150-200 yuan/mt range, with continued monitoring of cold- and hot-rolled apparent demand, inventory, and the pace of steel mill hot metal reallocation.
[SMM Analysis] HRC-Rebar Price Spread Retreats from Highs, Likely to Narrow Further in October
Data Source Statement: Except for publicly available information, all other data are processed by SMM based on publicly available information, market communication, and relying on SMM's internal database model. They are for reference only and do not constitute decision-making recommendations.
For any inquiries or for more information, please contact: lemonzhao@smm.cn
For more information on how to access our research reports, please contact:service.en@smm.cn
Related News
7 mins ago
[SMM Steel] India Domestic Steel Prices Ease on Slow Demand, Cautious Buying
Read More
[SMM Steel] India Domestic Steel Prices Ease on Slow Demand, Cautious Buying
[India Domestic] Domestic steel prices extended decline amid weak demand and cautious buying. The small decline looks like a short pause after a big rise as buyers wait to see whether prices hold. Mandi ingot down 8 USD/tonne (800 INR/tonne) to 485 USD/tonne (46,500 INR/tonne) EXW Mandi. HMS 1&2 (80:20) down 7 USD/tonne (700 INR/tonne) to 394 USD/tonne (37,800 INR/tonne) delivered Mandi. Raipur billet down 5 USD/tonne (500 INR/tonne) to 453 USD/tonne (43,500 INR/tonne) EXW Raipur. Domestic demand and firm raw-material costs are supporting local billet prices, while overseas buyers remain cautious and are resisting higher offers. Mumbai Rebar decreased 5 USD/tonne (500 INR/tonne) to 537 USD/tonne (51,500 INR/tonne) EXW Mumbai. Sponge iron PDRI down 3 USD/tonne (300 INR/tonne) to 289 USD/tonne (27,800 INR/tonne) EXW Raipur. Domestic steel market may pick up after the monsoon and prices may likely to go up in coming weeks which could support rebar demand.
7 mins ago
12 mins ago
[SMM Steel]
Read More
[SMM Steel]
[SMM Steel] Market feedback indicates that for Q235B medium-thickness plates with specifications of 14-30mm for December shipment, the selling price is $545/mt FOB, with the port of departure being Tianjin Port.
12 mins ago

13 mins ago
[SMM Steel]
Read More
[SMM Steel]
[Steel Billet] Billet export FOB prices held stable with a soft tone today, with offers at Jiangyin Port at $465–470/mt. According to market research, billet exports have seen inquiries recently, but buyers' ideal price levels are relatively low. Considering the pressure of absorbing supply amid domestic demand, some mills made slight price concessions in their sales.
13 mins ago

Register to Continue Reading
Gain access to the latest insights in metals and new energy
Already have an account?Sign in here