SMM, September 24:
With the Mid-Autumn Festival and National Day holidays approaching, SMM reached out to die-casting zinc alloy and zinc oxide enterprises in the market to learn about their holiday arrangements. The details are as follows.
Die-casting zinc alloy:
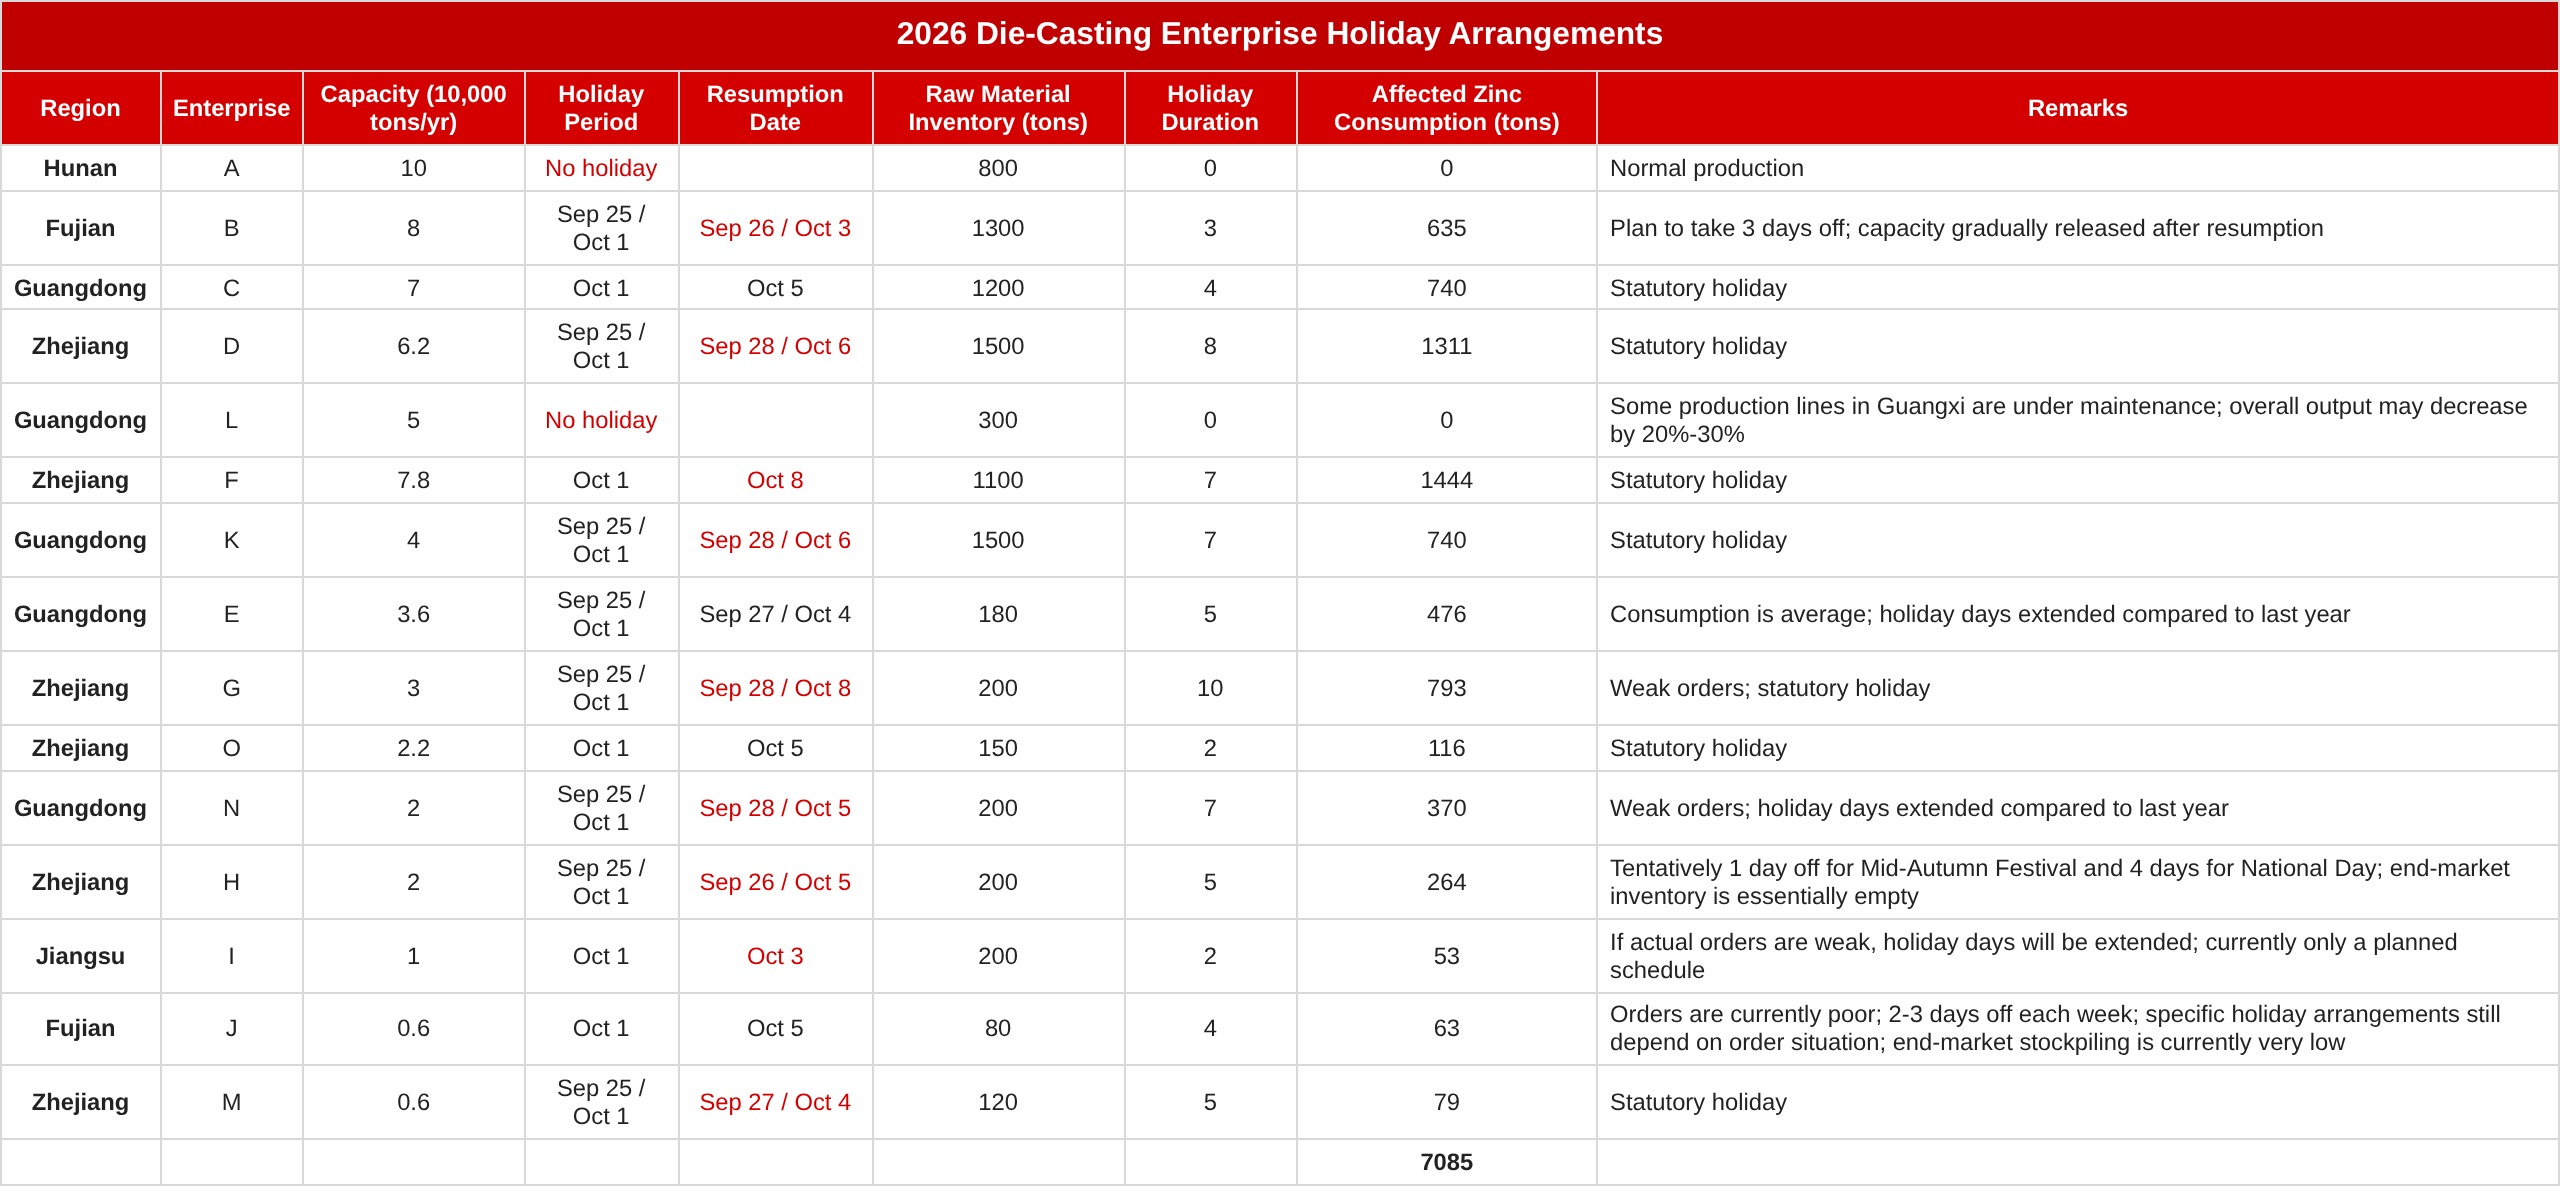
SMM surveyed a total of 15 die-casting zinc alloy enterprises regarding their holiday arrangements, with a combined capacity of 630,000 mt and an affected zinc consumption of 7,085 mt.According to SMM, the holiday duration for these enterprises during the National Day and Mid-Autumn Festival holidays ranged from 0 to 10 days, averaging 4.6 days, up 0.2 days YoY from 4.4 days last year. The extended holiday duration was primarily due to high prices during the month, which weakened end-use consumption, with insufficient new orders across all segments and low pre-holiday stockpiling willingness and volumes among end users. On top of the statutory holidays, some plants proactively extended their holiday duration based on order conditions; some enterprises also indicated that if orders remain weak, the actual holiday period would be further extended beyond current plans. Additionally, some manufacturers took advantage of the holiday window to schedule production line maintenance, with expectations for production cuts despite no full shutdown.
Zinc oxide:
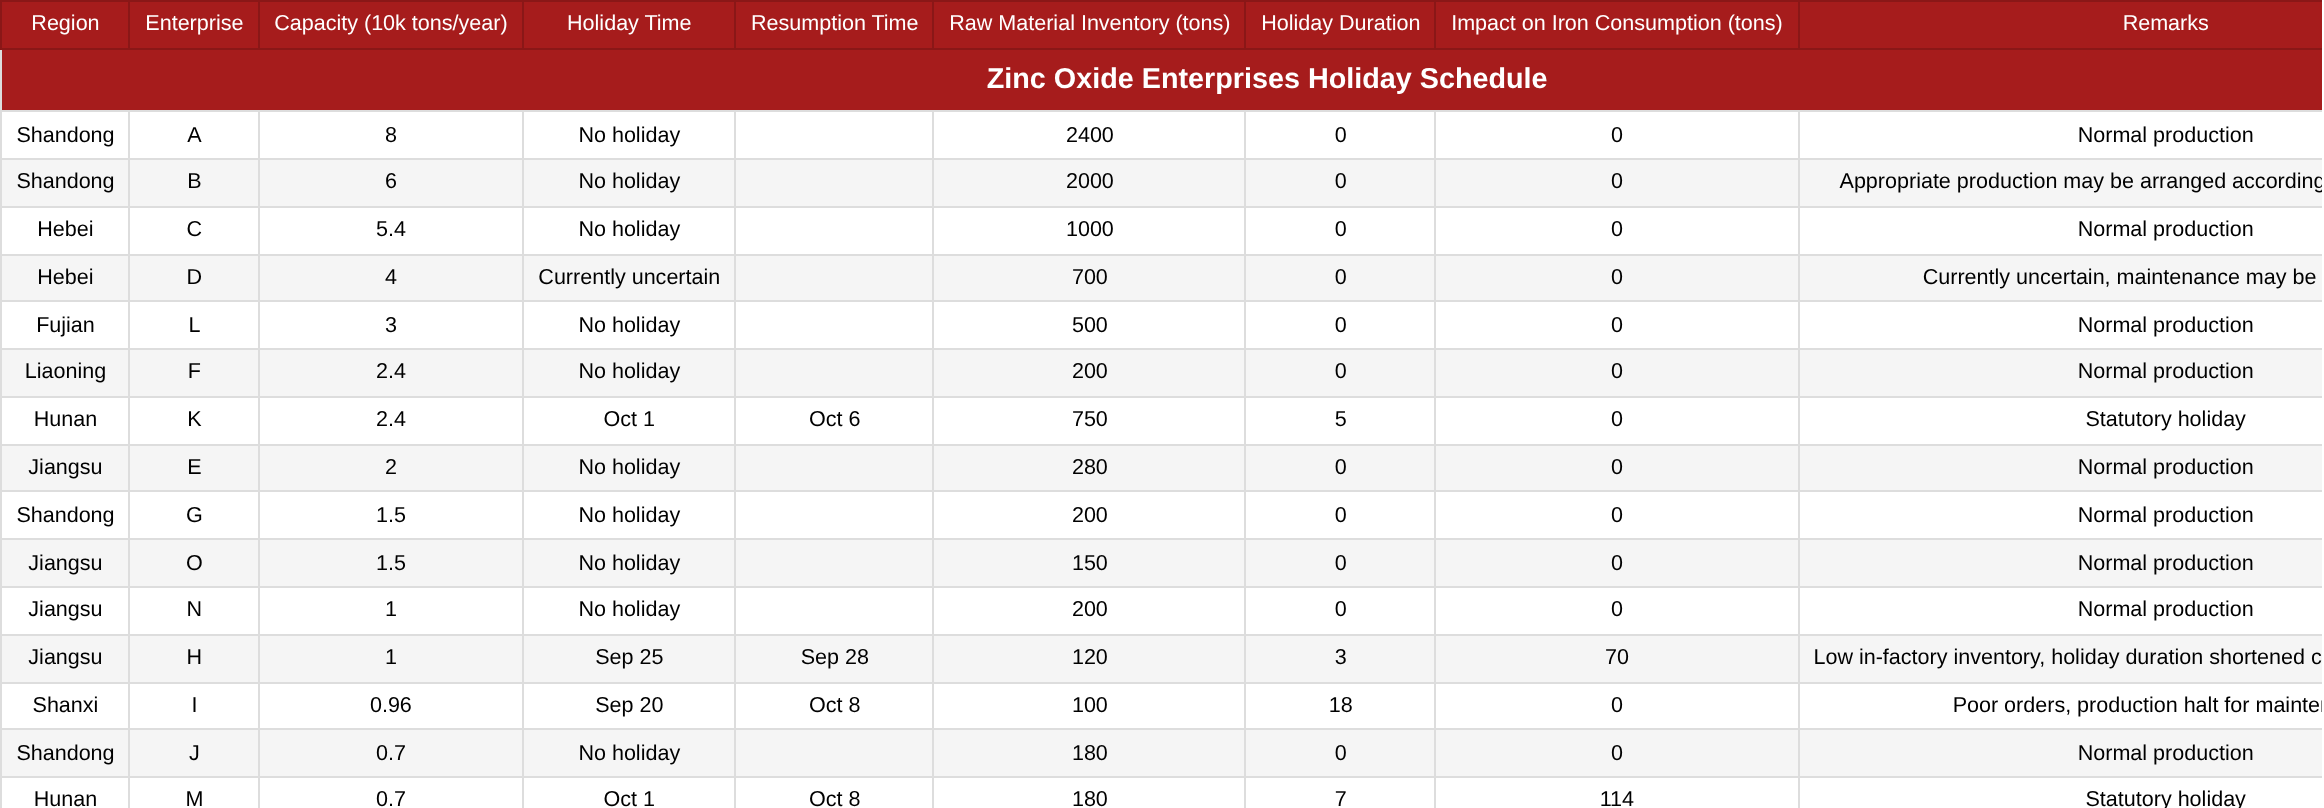
For zinc oxide, SMM also surveyed 15 zinc oxide enterprises regarding their holiday arrangements, with a combined capacity of 405,600 mt and an affected zinc consumption of 184 mt.Due to the production process characteristics of zinc oxide, most zinc oxide enterprises in the market maintained normal production, except for a few with holiday arrangements. From the perspective of recent end-use consumption, the zinc oxide downstream showed no notable highlights: tire enterprises extended their holiday duration YoY during the dual festivals; end-use demand in the ceramics sector remained weak; orders for electronic-grade zinc oxide were generally stable; feed-grade zinc oxide demand recently recovered, driven by the peak season. Most enterprises maintained normal production, with some manufacturers flexibly controlling output based on orders; a few enterprises arranged production halts for maintenance due to weak orders, while others had maintenance expectations. A small number of enterprises had low in-factory inventory and shortened their holiday duration compared with last year.
(The above information is based on market collection and a comprehensive assessment by the SMM research team, and is provided for reference only. This article does not constitute direct investment research advice. Clients should make decisions prudently and should not use this as a substitute for independent judgment. Any decisions made by clients are not related to SMM.)