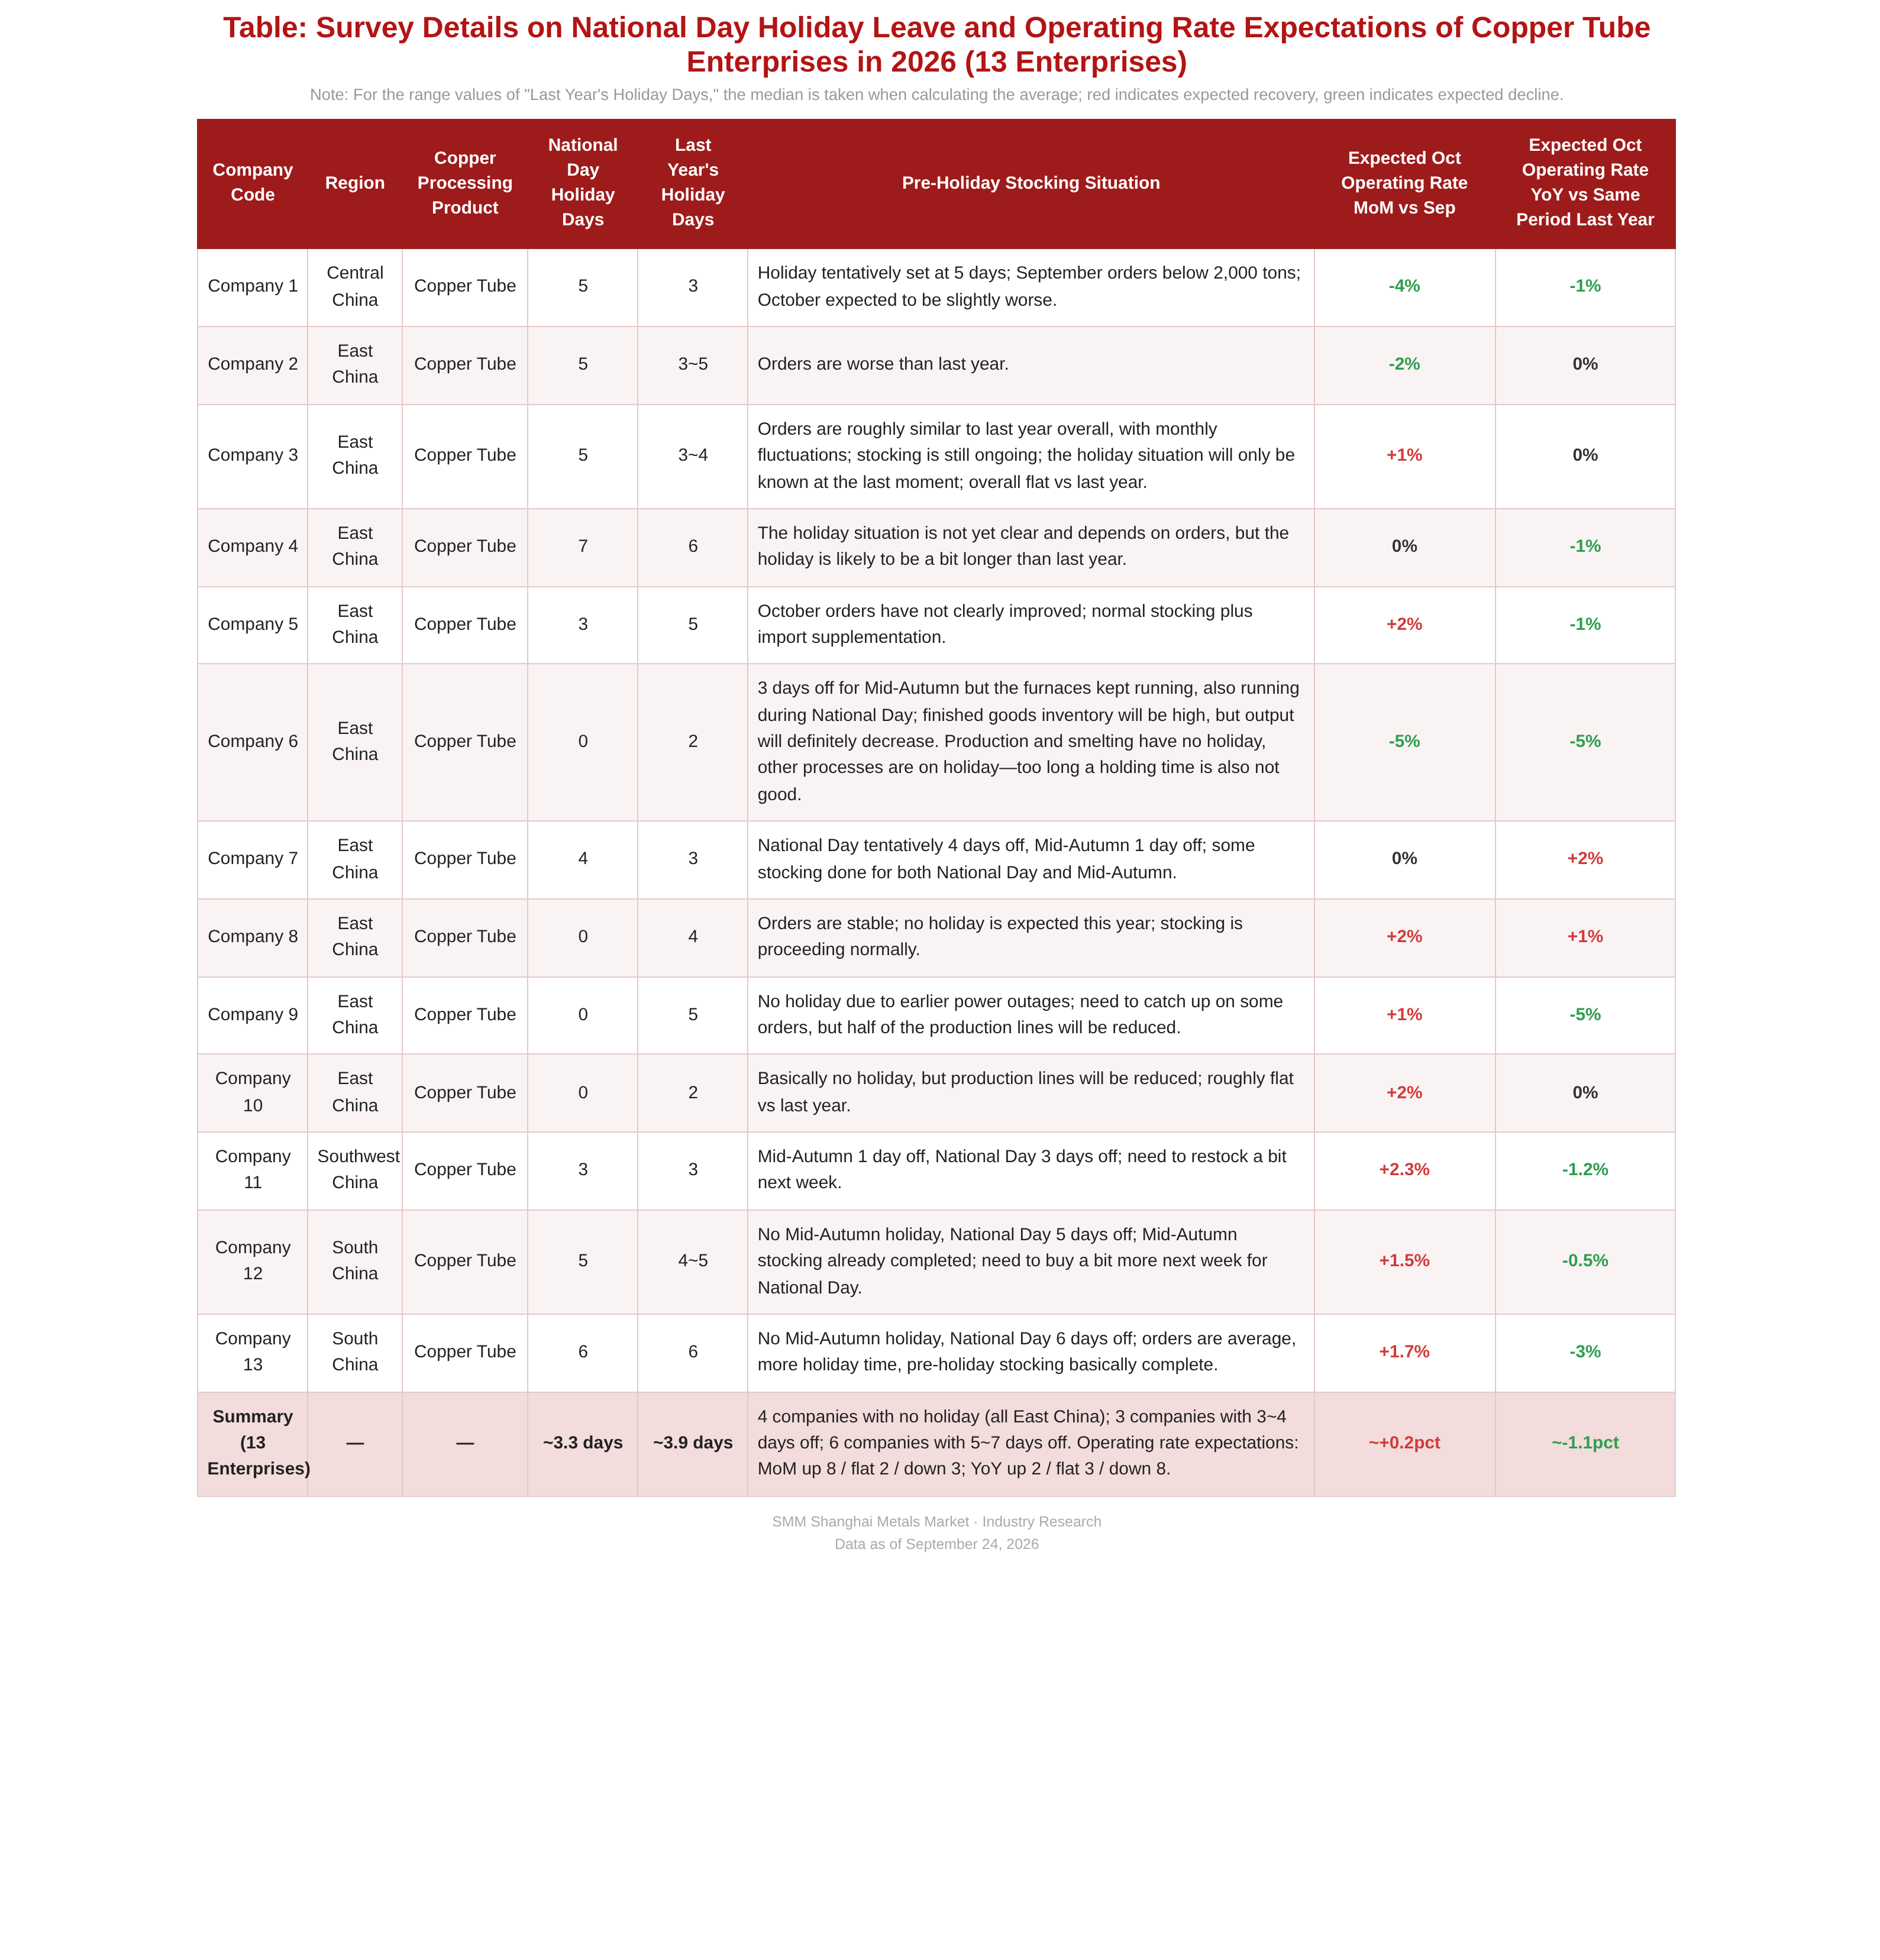
In previous years, the "September-October peak season" marked the start of the new refrigeration year, with copper pipe & tube market orders and operating rates both notably strong. Last October was once regarded as the most sluggish "October peak season" for copper pipe & tube operating rates in recent years. This year, against the backdrop of narrowing YoY declines in air-conditioner production schedules and October production schedules turning positive YoY, the holiday arrangements of the 13 copper pipe & tube enterprises surveyed by SMM were overall tighter than last year—four east China enterprises maintained production during the National Day holiday without days off, and the sample average holiday duration was about 3.3 days, roughly 0.6 days shorter than last year. The October operating rate of the copper pipe & tube industry is expected to stabilize MoM, with the YoY decline narrowing significantly, but orders have yet to show substantive improvement, and the strength of the "October peak season" remains to be verified.
1. Holiday Duration
SMM surveyed a total of 13 copper pipe & tube enterprises (9 in east China, 2 in south China, 1 in central China, and 1 in southwest China). This year's National Day holiday arrangements showed clear divergence: the sample average holiday was about 3.3 days, 0.5-0.6 days shorter than last year (about 3.9 days, estimated using the midpoint of the range), contrasting with last year's situation where "most enterprises increased holiday days by 1-3 days."
Specifically: four east China enterprises (Enterprises 6, 8, 9, and 10) did not take National Day holidays. Among them, Enterprise 9 rushed to meet deadlines to make up orders due to earlier power outages affecting production (running production lines at half capacity), Enterprise 8 maintained normal production with stable orders, and Enterprises 6 and 10, while not taking holidays, reduced production lines and controlled output, with smelting operations generally kept warm without shutdowns. Three enterprises (Enterprises 5, 7, and 11) took 3-4 days off, with Enterprise 5 shortening its holiday by 2 days compared with last year. Six enterprises (Enterprises 1, 2, 3, 4, 12, and 13) took 5-7 days off, with the two south China enterprises taking 5 and 6 days respectively, and Enterprise 4 tentatively scheduled for a full 7 days, 1 day more than last year. Most enterprises indicated that the final holiday duration would still need to be adjusted based on actual order conditions in the last few trading days before the holiday. During the Mid-Autumn Festival holiday (September 25-27), most enterprises maintained normal production or took only 1-3 days off, and some south China enterprises did not take the Mid-Autumn holiday, having completed stockpiling in advance.
2. Pre-Holiday Stockpiling
Copper prices continued to hit record highs before the holiday: LME copper prices stood above $14,000/mt (intraday high of $14,635/mt touched on September 8), and the most-traded SHFE copper contract traded near 108,000 yuan/mt. China's social inventory of copper cathode fell to a multi-year low of around 90,000 mt, with spot copper cathode maintaining a premium structure. Historically high raw material prices have significantly raised the capital cost of stockpiling. Coupled with most enterprises reporting that September orders were roughly flat or slightly weaker YoY, pre-holiday stockpiling was generally cautious and driven mainly by firm orders: large enterprises relied on long-term contracts and imported supply to replenish raw material inventory (e.g., Enterprise 5 "normal stockpiling plus import replenishment"); small and medium-sized enterprises purchased as needed, with most completing pre-Mid-Autumn Festival stockpiling and planning to restock small volumes before the National Day holiday depending on orders (e.g., Enterprise 12 "Mid-Autumn stockpiling is already complete, and we will still buy a little more for the National Day holiday next week"). In addition, enterprises in parts of east China that had earlier faced power-related production restrictions rushed to deliver orders before the holiday, front-loading raw material procurement accordingly.
III. Market Conditions
In terms of operating rates, the average operating rate of the copper pipe & tube industry in August was 62.87%, down 1.22 percentage points MoM and down 2.83 percentage points YoY, with the decline continuing to narrow and signs of an off-season bottom gradually emerging. The average operating rate of the copper pipe & tube industry in September is expected to be 63.88%, up 1.01 percentage points MoM but down 3.80 percentage points YoY. OEMs continued their strategy of production control and destocking, with raw material restocking willingness still at a low level. However, as the decline in air conditioner production schedules narrows, upstream copper pipe & tube procurement demand is expected to gradually recover.
On the end-use side, according to the latest ChinaIOL production schedule report, total household air conditioner production schedules in September were 9.75 million units, down 7.7% YoY: domestic sales schedules were 5.39 million units, down 9.4% YoY, with the decline narrowing sharply from 24.1% in August, supported by a low base in the same period of 2025; export schedules were 4.36 million units, down 11.7% YoY, with exports in the seasonal off-season. Total household air conditioner production schedules in October were 11.45 million units, turning positive with 0.7% YoY growth, with domestic sales schedules up 16.4% YoY and export schedules up 6.9% YoY, both turning positive—on the one hand, overseas dealers started Black Friday stockpiling earlier, front-loading orders to October after accounting for shipping time; on the other hand, the base in the same period of 2025 was relatively low. However, it should be noted that current production schedule expectations have still not returned to the peak levels of 2024, markets outside China still face certain inventory and competitive pressures, and the domestic sales recovery is driven more by a low base than by a reversal in end-use demand.
IV. Market Sentiment Outlook
Based on the expectations of 13 enterprises: 8 expect October operating rates to rebound slightly MoM from September (+1 to +2.3 percentage points), 2 expect them to remain flat, and 3 expect a pullback (-2 to -5 percentage points), with a simple average of about +0.2 percentage points MoM, suggesting the industry operating rate may stop falling and stabilize. On a YoY basis, only 2 expect levels above the same period last year, 3 expect flat, and 8 expect YoY declines, with a simple average of about -1.1 percentage points YoY, a notable narrowing from the industry-wide YoY decline of -3.80 percentage points in September, though the absolute level remains below the same period last year.
Overall, with air-conditioner production schedules turning positive in October and Black Friday stockpiling orders being front-loaded, the direction of marginal improvement in copper pipe & tube demand is gradually being established, and the tightening of holiday arrangements also indirectly confirms that orders on hand at some enterprises are improving MoM; however, enterprises generally report that October orders have not yet clearly improved (e.g., Enterprise 5 said "October orders have not clearly improved," and Enterprise 1 said "September orders were less than 2,000 mt, and October is expected to be slightly worse"), and with historically high copper prices suppressing stockpiling and new orders, the strength of the "October peak season" recovery is expected to be mild, with the industry closer to "weak stabilization" than a "strong rebound." In addition, the impact of the US tariff hike on imported copper pipe & tube is still unfolding, with copper pipe & tube exports from China and Thailand to the US remaining at low levels and capacity at local US copper pipe & tube plants continuing to ramp up, meaning the export side's contribution to Q4 operating rates remains constrained. After the holiday, close attention should be paid to the actual fulfillment of air-conditioner production schedules and the pace of destocking of pre-holiday stockpiling inventory.
V. Enterprise Survey Details