In a survey conducted ahead of the 2026 National Day holiday, SMM investigated and summarized holiday production schedules and pre-holiday stockpiling at 20 major copper cathode rod enterprises in China, with a combined capacity of 7.66 million mt/year. Overall, copper cathode rod enterprises had more production downtime during this year's holiday than last year. The specific survey findings are as follows:
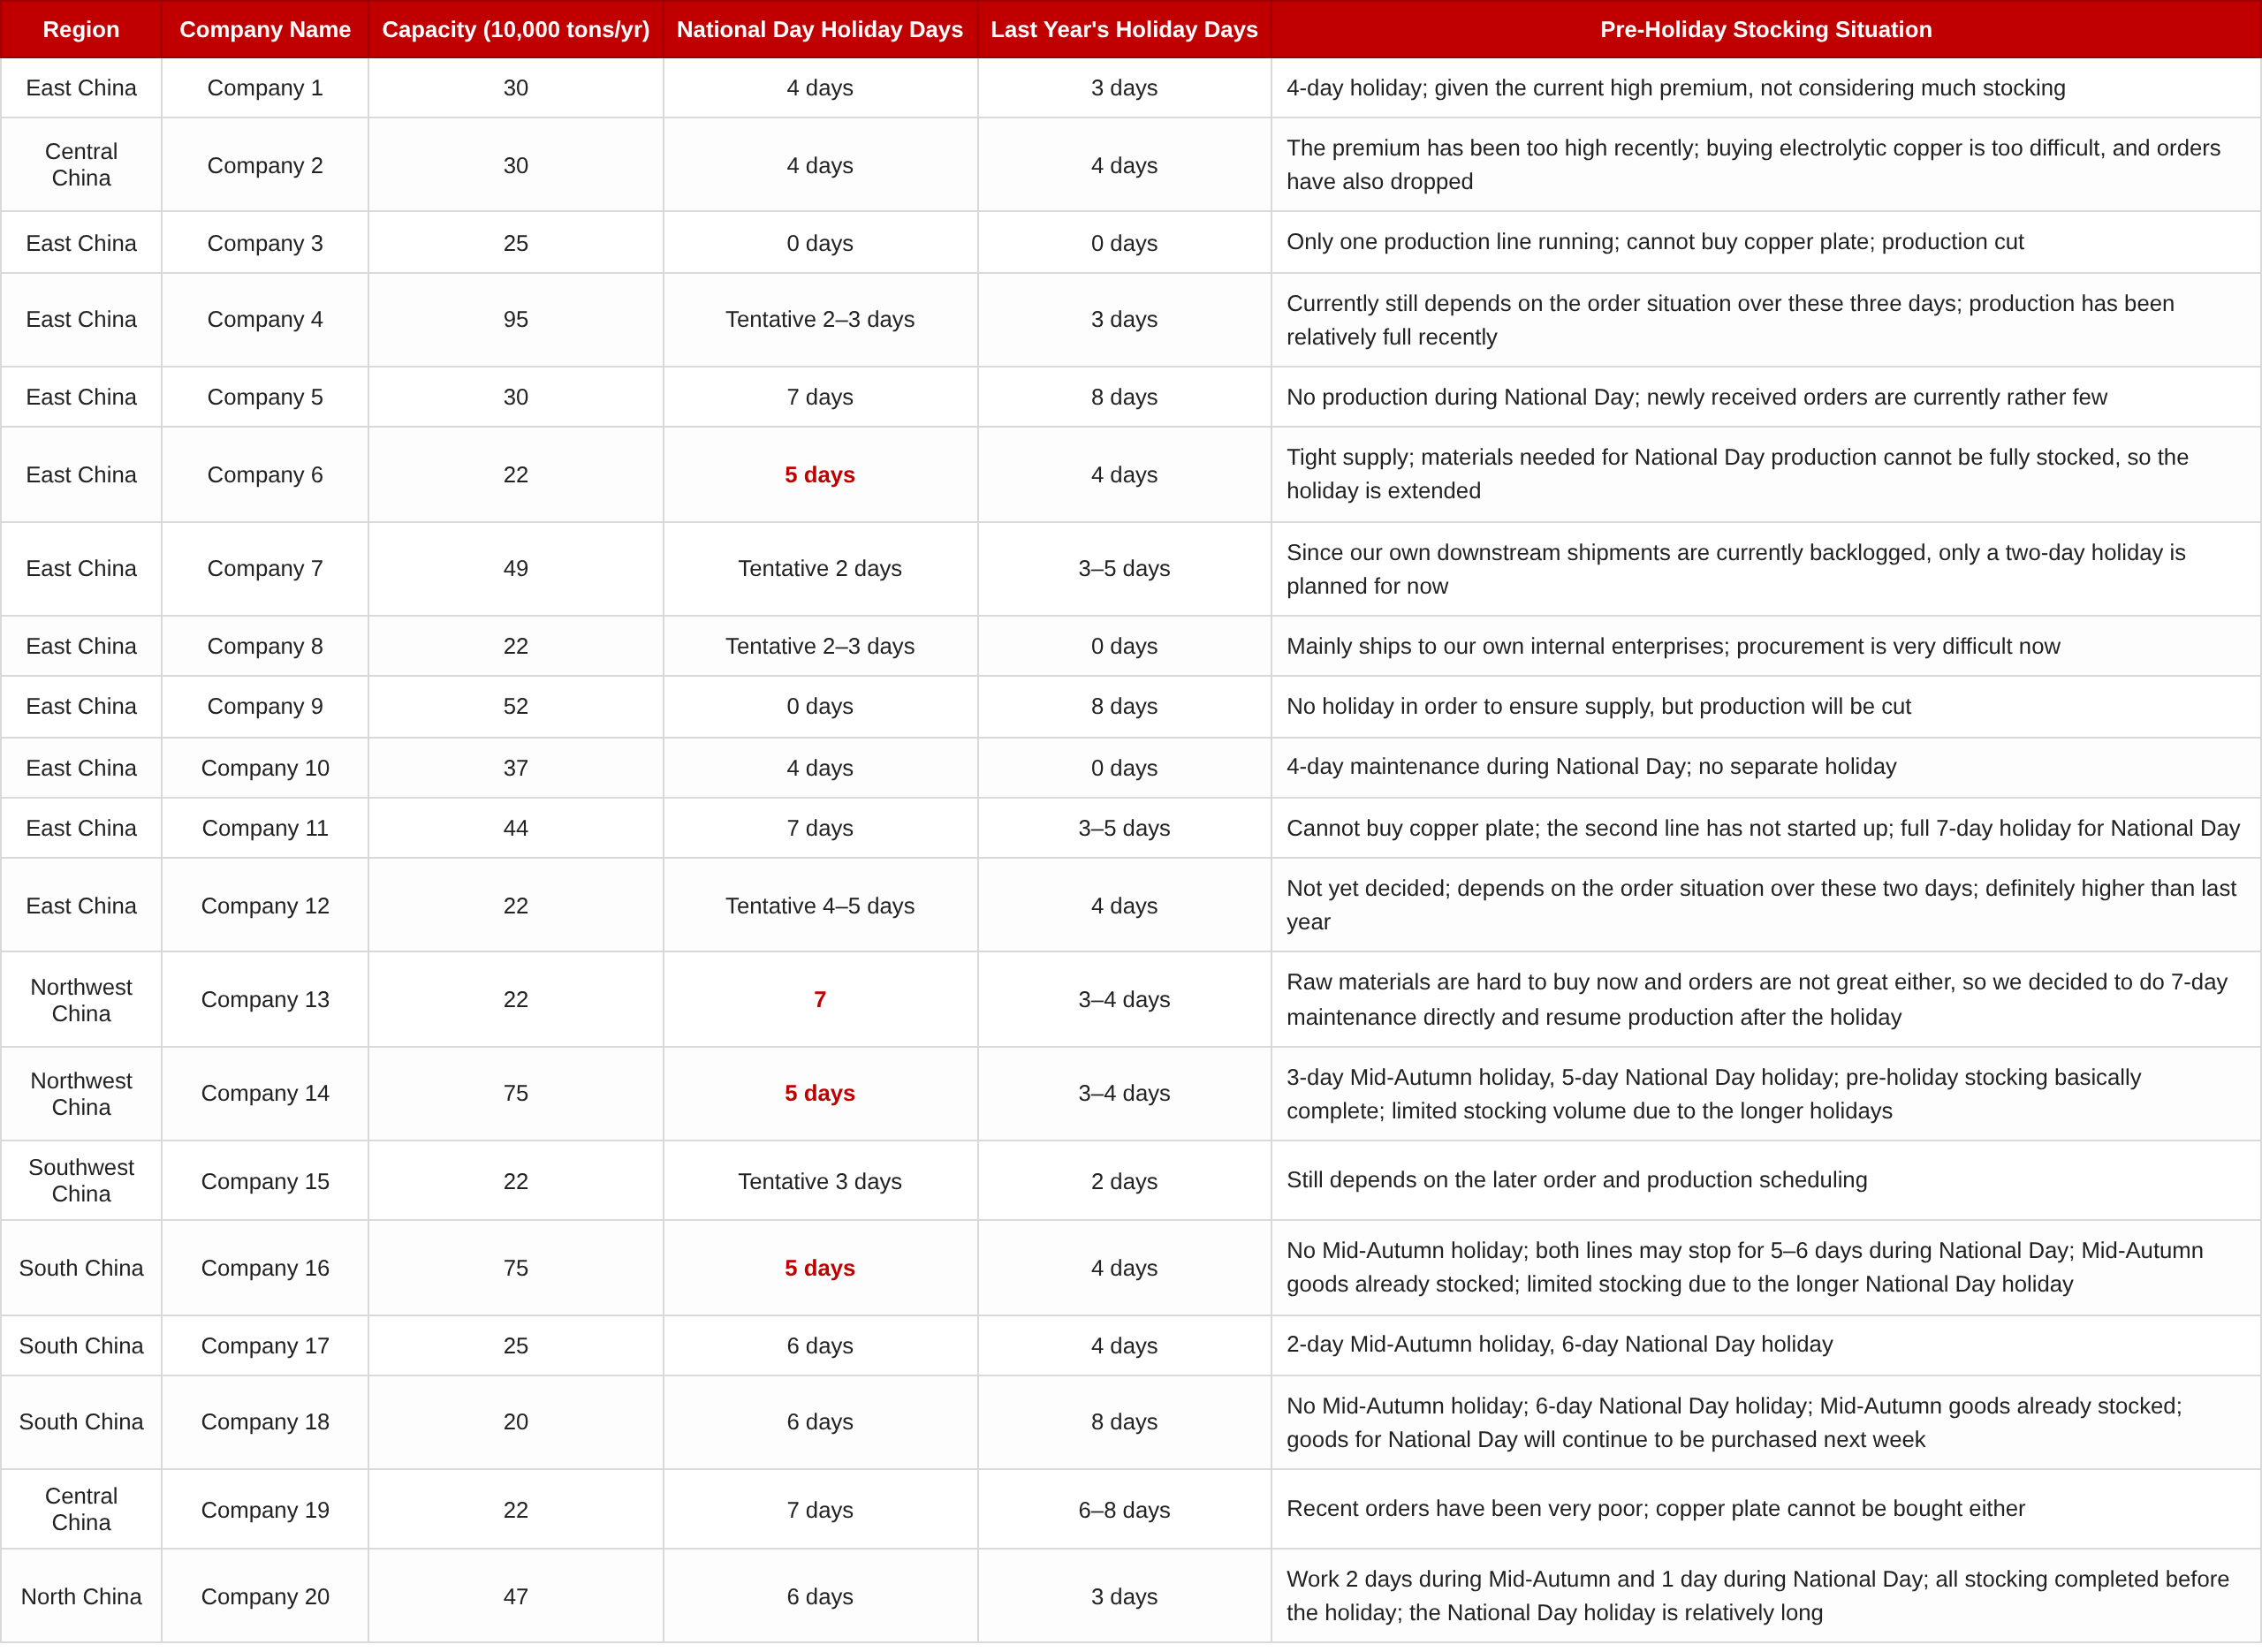
According to SMM analysis, copper prices fluctuated at highs in the early part of this year, continuously suppressing downstream purchasing demand. Just before the holiday, copper prices pulled back sharply, triggering a concentrated release of downstream rigid demand. New orders at copper cathode rod enterprises increased significantly, and at that time, enterprises generally expected holiday downtime to be shortened. However, as the holiday approached, spot copper cathode supply became increasingly scarce, spot premiums kept rising, and raw material procurement became more difficult. In addition, downstream wire and cable and enamelled wire enterprises found it hard to accept high premiums, and stockpiling sentiment weakened notably. As a result, holiday downtime increased rather than decreased, and the production pace slowed YoY.
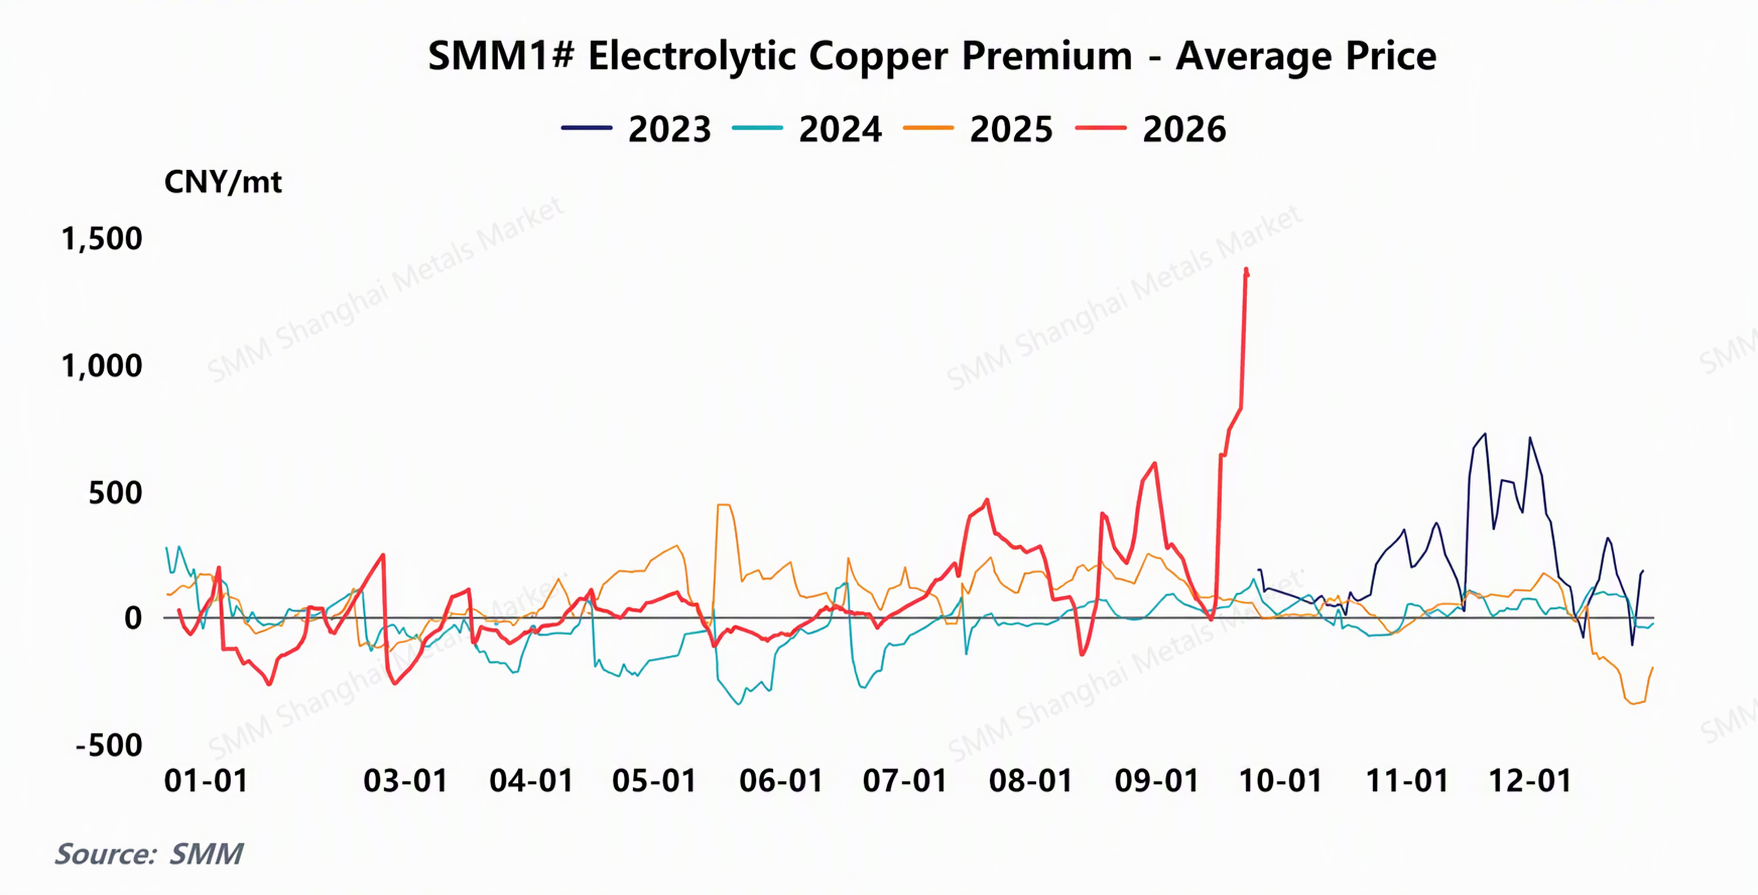
Regarding pre-holiday stockpiling, spot copper cathode supply was tight and spot premiums shot up, while high copper prices put significant capital pressure on copper cathode rod enterprises. Coupled with a notable decline in new orders, raw material stockpiling sentiment weakened accordingly. Downstream wire and cable and enamelled wire enterprises had already restocked intensively when copper prices pulled back sharply earlier. Approaching the holiday, their stockpiling pace slowed down due to high copper prices and high premiums. In addition, downstream demand showed no clear recovery, and holiday downtime was basically flat YoY.
Based on records from the same sample last year, the average holiday downtime for the 2025 National Day survey sample was 4.05 days, while the average downtime for the same sample during the 2026 National Day holiday was 4.4 days, up 0.35 days YoY.
Compared with last year and previous years, copper cathode rod enterprises performed well in Q1 2026, driven by a pullback in copper prices and sluggish secondary rod production. Subsequently, copper prices continued to rise, exerting more obvious pressure on orders and production schedules. Combined with current high premiums, wire and cable enterprises showed lower pre-holiday stockpiling enthusiasm than last year, and new orders were limited as the holiday approached. Based on current downstream demand and order production schedules, enterprises expect demand in October to lack clear signals of a peak-season recovery and hold a cautious attitude toward October consumption expectations. Future production pace will be dynamically adjusted according to copper prices and changes in downstream new orders.
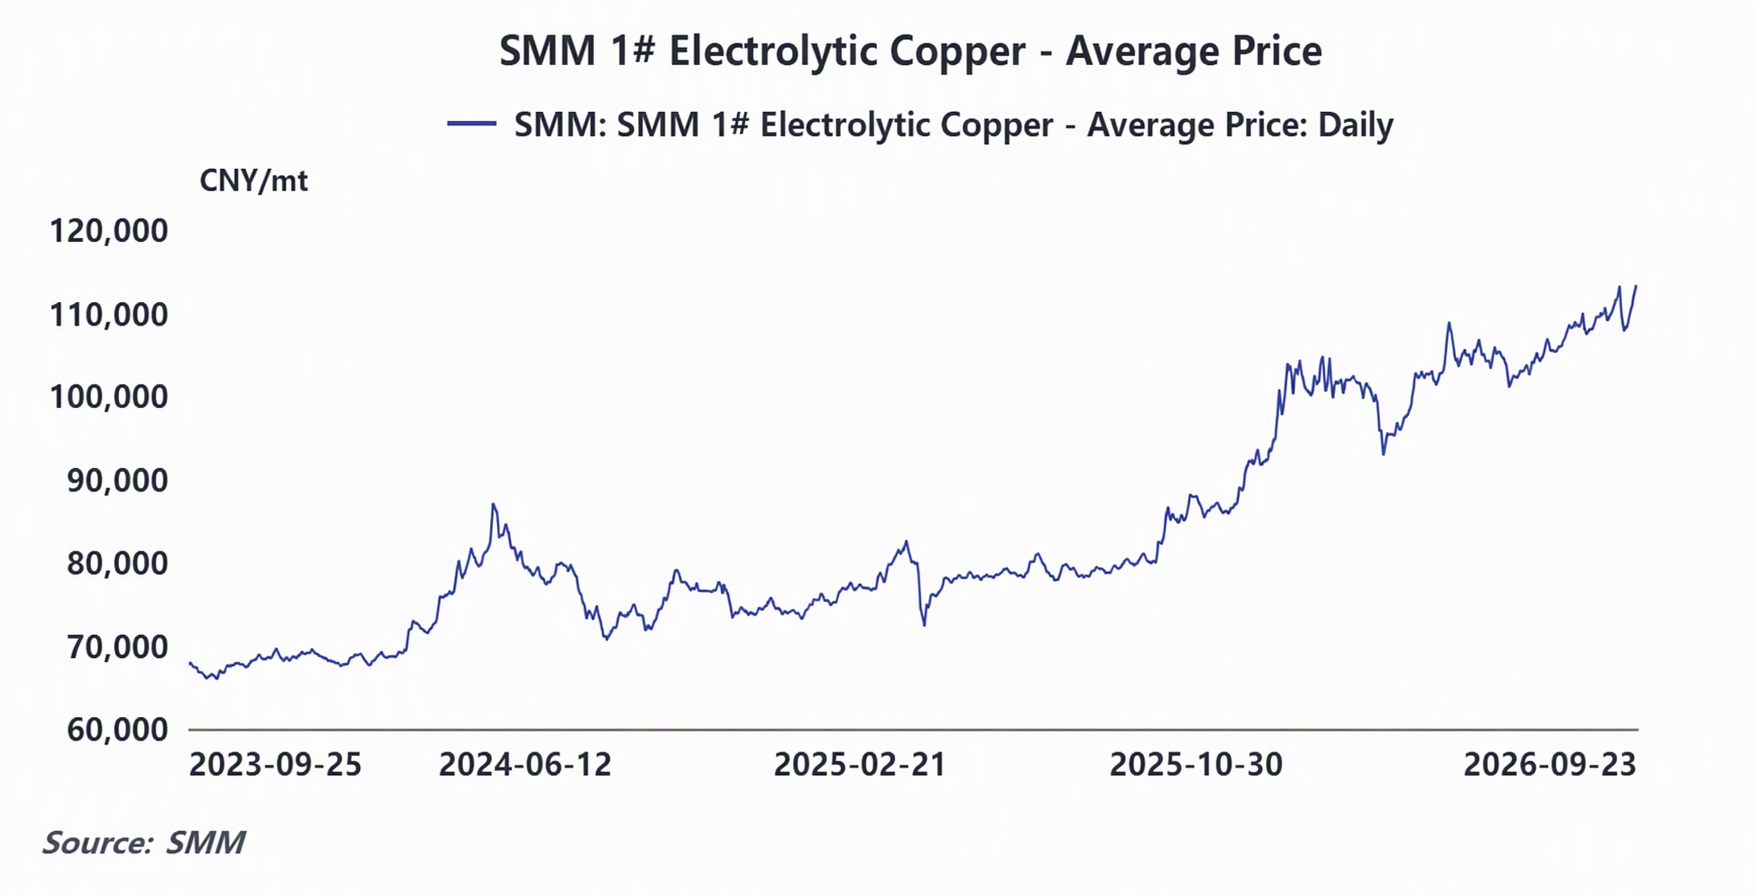
Looking ahead to October, affected by holiday downtime, multiple enterprises indicated that operating rates would decline MoM in October. From the consumption side, consumption performance is weak under high copper prices, making a peak-season performance unlikely, and it also shows a weaker trend compared with the same period last year. Accordingly, the operating rate of copper cathode rod enterprises in China is expected to decline MoM in October 2026 and fall below the level of the same period last year. Given the current high level of uncertainty and with several working days remaining before the National Day holiday, enterprises will continue to monitor the subsequent trend in spot premiums and order performance. The average holiday duration for the same sample during the 2026 National Day holiday is tentatively set at 4.4 days.SMM will continue to follow up and provide updates on the actual production schedules and order conditions of copper cathode rod enterprises after the holiday, as well as the specific consumption trends and forecasts for October.