SMM, September 23: August exports remained at the third-highest level of the year, with markets outside the USup 2.8% MoM, as overseas demand shifted from single-point US-driven growth to multi-regional support from Southeast Asia, Northeast Asia, and Europe.
In August 2026,China's LFP exports totaled 10,151.86 mt, down 3,001.4 mt from July,a decline of 22.82% MoM. This marked the second consecutive monthly decline after hitting a year-to-date high of 15,379.6 mt in June. Cumulative exports from January to August reached 71,958.109 mt, with overseas markets overall remaining in a high-growth range.
US exports halved, driving the August decline
The biggest change in August came from the US.China's LFP exports to the US totaled 2,767.3 mt, down 53.7% from 5,972.529 mt in July, a monthly decline of 3,205.175 mt.
The August decline was primarily driven by the pullback in the US market, rather than a synchronized weakening of global demand. The reduction from the US alone exceeded the overall market's net decline of 3,001.4 mt.Excluding the US, exports to other markets totaled 7,384.5 mt in August, up 2.84% from July.The US market may be undergoing inventory digestion following earlier concentrated stockpiling, while also being affected by local battery capacity expansion and supply chain policy changes, with monthly procurement pace slowing noticeably.
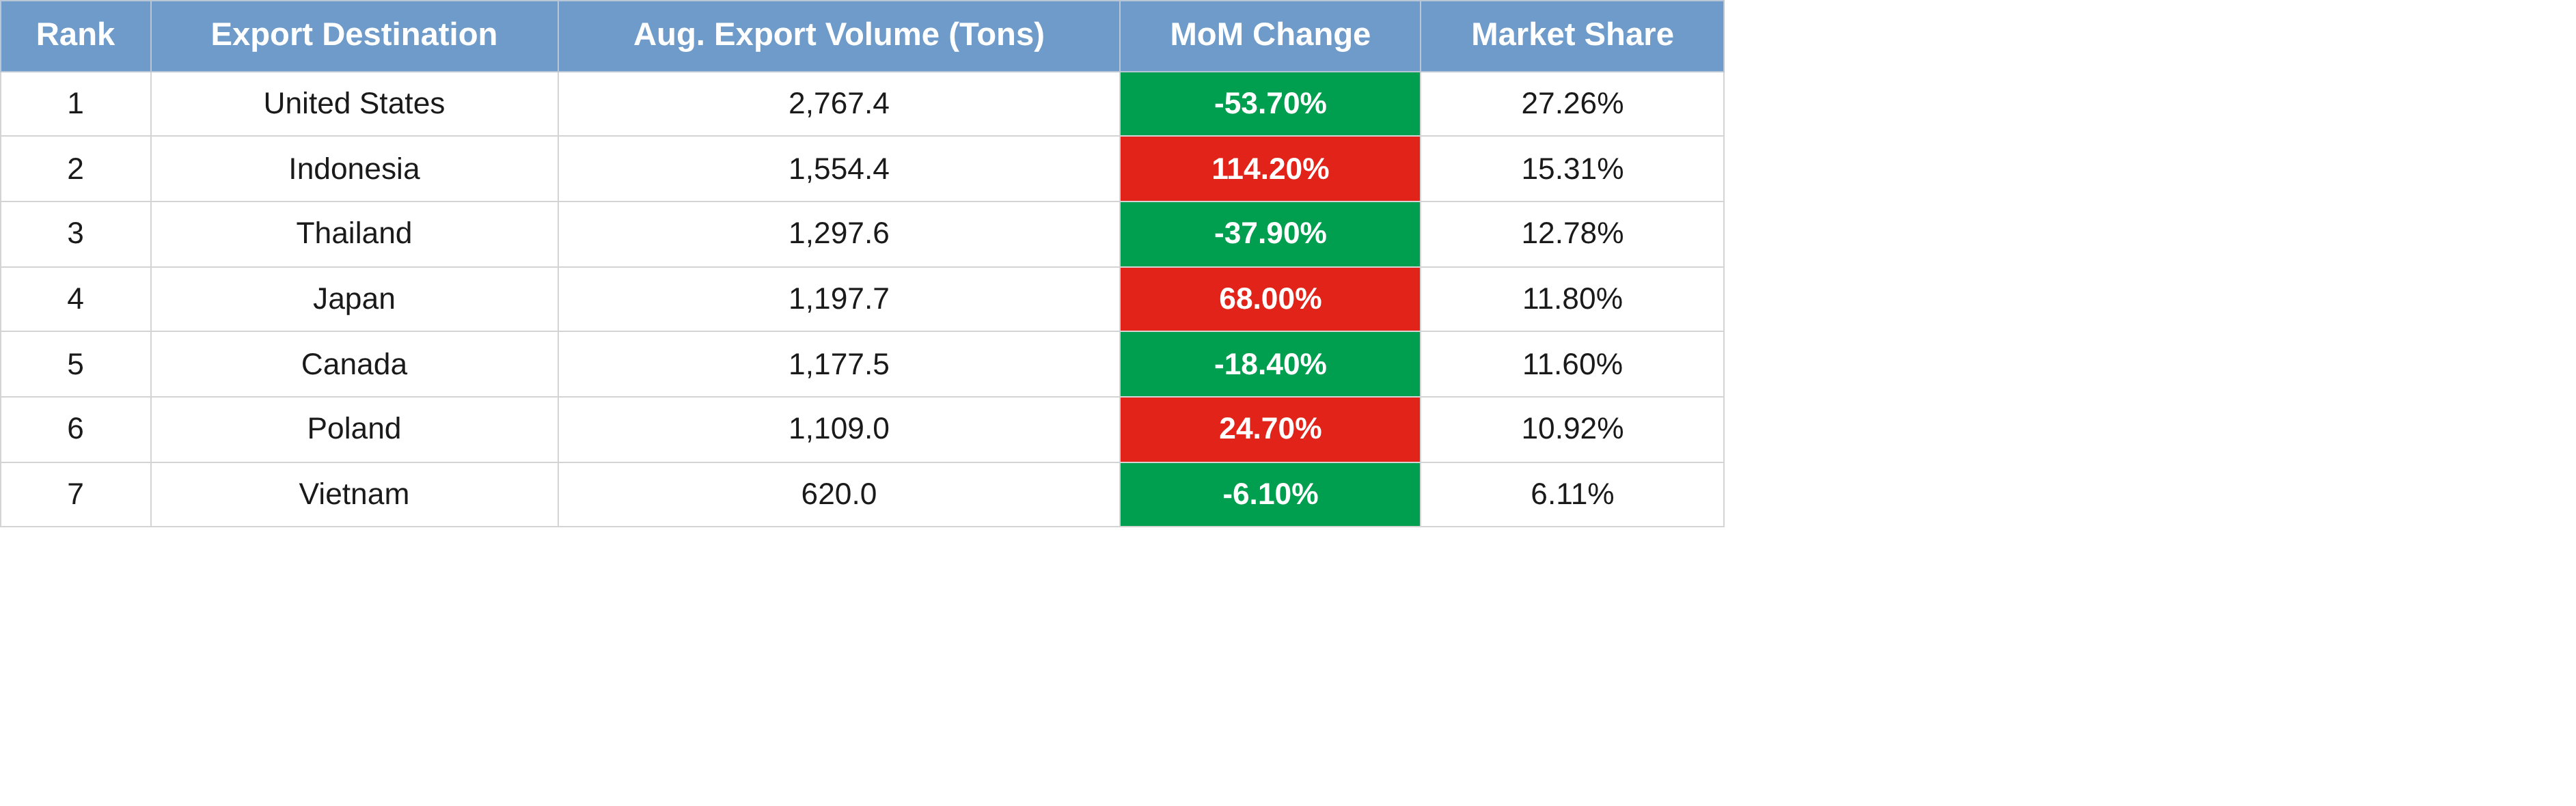
The top six export destinations accounted for89.67%of total August exports. Market concentration remained high, but the regional structure has shifted significantly - combined exports to North America fell from 7,415.9 mt in July to 3,944.9 mt, down 46.8% MoM, with its share dropping from 56.38% to 38.86%.Meanwhile,the Northeast Asia market comprising Japan, South Korea, and Taiwan, China grew 71.9% MoM, with its market share rising from 6.62% to 14.74%.
Indonesia jumps to second place; REPT Battero's 8 GWh base likely the main demand source
Indonesia was the largest growth market in August. China's LFP exports to Indonesia increased from 725.614 mt in July to 1,554.4 mt, up 114.2% MoM, a monthly increase of 828.786 mt, making it the second-largest export destination for the first time.
Based on project commissioning time and material demand, this round of export growth is most likely related to the commissioning and ramp-up of REPT Battero's battery cell and ESS manufacturing base in Indonesia. REPT Battero officially unveiled its first overseas manufacturing base in Indonesia in May 2026. According to SMM survey, the first phase of the base is designed to produce 8 GWh of EV and ESS batteries and systems annually. At full capacity, the corresponding LFP demand is approximately 17,600 to 20,000 mt per year, equivalent to a monthly average of about 1,400 to 1,700 mt.
Indonesia's average monthly imports from June to August were 1,588.8 mt, with August imports of 1,554.4 mt, corresponding to battery cell capacity of approximately 7.63 to 8.67 GWh.
Japan's imports rise significantly; lithium battery production demand may be released in concentrated fashion
Japan imported 1,197.7 mt of LFP in August, up 484.8 mt from July, an increase of 68% MoM, making it the second-largest source of incremental growth for the month. LFP exported to Japan likely mainly enters local lithium battery production, with end-use applications including vehicle batteries, residential and industrial and commercial ESS, and backup power supply.
Poland's exports surpass 1,000 mt; European ESS industry chain demand rises
Poland's imports reached 1,109 mt in August, up 24.7% MoM, accounting for 10.92% of total monthly exports.Poland is an important battery manufacturing base in Europe. Poland's imports have remained at relatively high levels, likely related to local ESS battery line material preparation, product validation, and utility-scale energy storage project deliveries. However, the customs destination country may also be a regional production or logistics node, with some materials ultimately serving other European markets.
Thailand, Canada, and Vietnam remain a stable base
Thailand imported 1,297.6 mt in August, down 37.9% MoM, but remained the third-largest export market.In recent years, Thailand has continued to attract NEV, battery pack, and ESS capacity, forming a relatively complete downstream application market.
Canada imported 1,177.5 mt in August, down 18.4% MoM, but maintained a thousand-ton scale for consecutive months.The country is advancing energy storage supply chain development and battery manufacturing localization, leading to large-scale material imports.
Vietnam imported 620 mt in August, down 6.1% MoM, remaining generally stable.The LFP battery cell project planned by Gotion High-tech and VinES in Ha Tinh Province, Vietnam has a designed annual capacity of 5 GWh, making it a representative LFP battery project in the region. This project, along with the expansion of Vietnam's NEV industry, provides a potential long-term demand base for Chinese LFP materials.
H2 likely to consolidate at highs; export destinations continue to diversify
From July to August 2026, China's average monthly LFP exports reached 11,652.6 mt, 43.7% higher than the H1 monthly average.Therefore, even with the August pullback from July, the overall H2 export baseline remains significantly higher than H1. Overseas battery and energy storage projects typically procure materials according to equipment commissioning, client certification, production line ramp-up, and project delivery periods, making monthly exports susceptible to concentrated shipments of large orders. June exports doubled MoM, followed by consecutive declines in July and August, reflecting the high volatility characteristic of project-based exports.
Looking ahead to September-December, the US will remain the biggest variable affecting total volumes. If US inventory digestion ends and procurement resumes, monthly exports could rebound significantly; if the US remains in a destocking phase, markets such as Indonesia, Japan, Poland, Thailand, and Vietnam will provide important support. Based on an average monthly export estimate of 9,000 to 11,000 mt over the final four months, China's full-year 2026 LFP exports could reach approximately 108,000 to 116,000 mt, with H2 volumes still expected to be significantly higher than H1.
Overall, the August export decline was primarily a structural cooling caused by the pullback in the single US market, rather than a broad weakening of overseas demand. More notably, export growth is gradually shifting from US-led to multi-regional support across North America, Southeast Asia, Northeast Asia, and Europe. As Chinese battery companies such as REPT Battero build battery cell and ESS capacity overseas, LFP exports are also extending from traditional trade demand to supporting overseas factory operations. The future focus of industry competition will no longer be just export volumes, but also overseas client certification, localized manufacturing, supply chain coordination, and trade compliance capabilities.
SMM New Energy Research Team
Wang Cong 021-51666838
Feng Disheng 021-51666714
Yang Chaoxing 021-20707860
Wang Zihan 021-51666914
Wang Jie 021-51595902
Chen Bolin 021-51666836
Wang Yizhou 021-51595909
Xu Mengqi 021-20707868
Hu Xuejie 021-20707858
Lin Ziya 021-51666902
Yang Le 021-51595898
Li Yisha 021-51666730
Wang Zhaoyu 021-51666827
Xiao Wenhao 021-51666872
Zhang Jing 021-51666878