Copper prices bottomed out over the past two weeks, after opening lower with a gap for several consecutive sessions under the twin bearish pressures of "uncertainty over US copper tariffs" and "the US Fed's September rate hike being delivered." As copper prices retreated from highs, downstream order growth was notable, and premiums had already been quietly rising. With supply disruptions in copper cathode intensifying, downstream buyers were forced to accept the "three highs" market conditions amid just-in-time procurement and pre-holiday stockpiling sentiment.
The logic flow for this round of market moves is as follows:
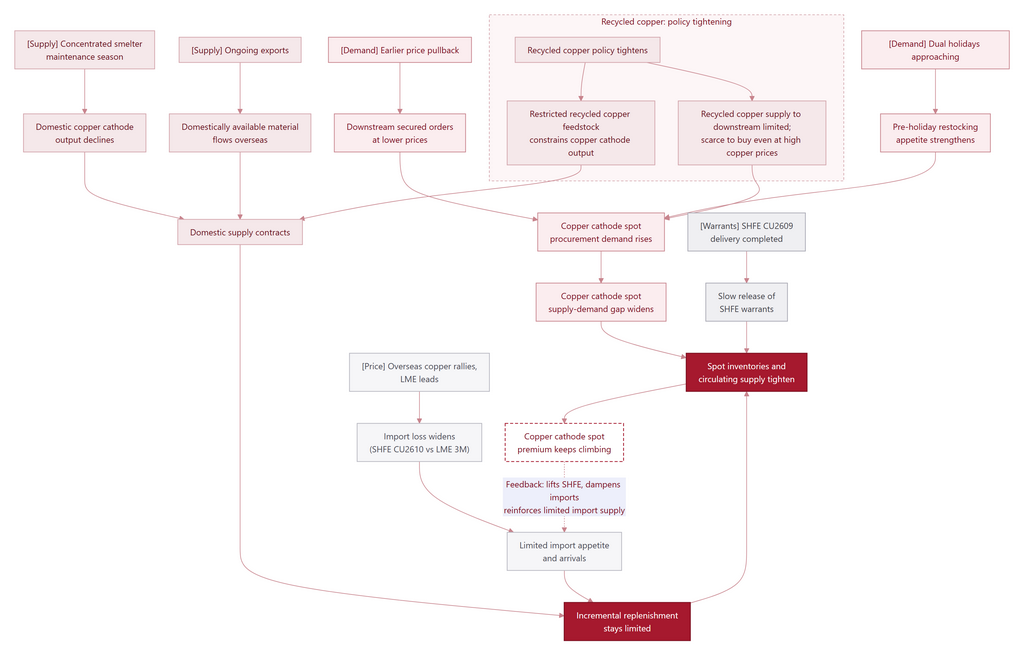
Looking ahead to the pre-holiday period, Shanghai spot copper premiums have already been pushed above 1,000 yuan/mt. Cargoes from large smelters across various regions have largely been pre-booked by downstream buyers, and domestic copper arrivals during the Mid-Autumn Festival and National Day holidays are expected to be relatively limited.
On the import side, cargoes available to flow into China were limited earlier, but some shipments have yet to arrive at port due to port congestion and are expected to arrive this week and around the National Day holiday. It is worth noting that the SHFE copper forward contract still maintains a negative price spread of more than 1,000 yuan/mt against LME 3M copper, which theoretically discourages exports. Meanwhile, with domestic spot premiums elevated, smelters have relatively limited willingness to export as well. Although spot imports currently show some profitability, the actual import profit margin is relatively small because spot premiums are difficult to lock in ahead of time. Attention should also be paid to whether canceled cargoes from LME warehouses in Asia will flow to China.
Domestic spot premiums are expected to stay high before the National Day holiday. After the holiday, the market will gradually shift toward delivery logic, and spot premiums may face pressure from elevated nearby BACK (inverted futures spread). However, open interest in the SHFE copper 2610 contract remains high, while actual trading days in October are limited, leaving relatively tight time for position reduction before the last trading day. The nearby BACK spread still has room to widen further.
Once the market rolls into the 2611 contract, the elevated price spread may partially shift into spot premiums, and spot premiums against the 2611 contract are expected to remain at relatively high levels. Considering factors such as smelter maintenance and production cuts, spot premiums in October may even have further upside potential, and market participants should be wary of volatility risks in an environment of high premiums and wide futures spreads.