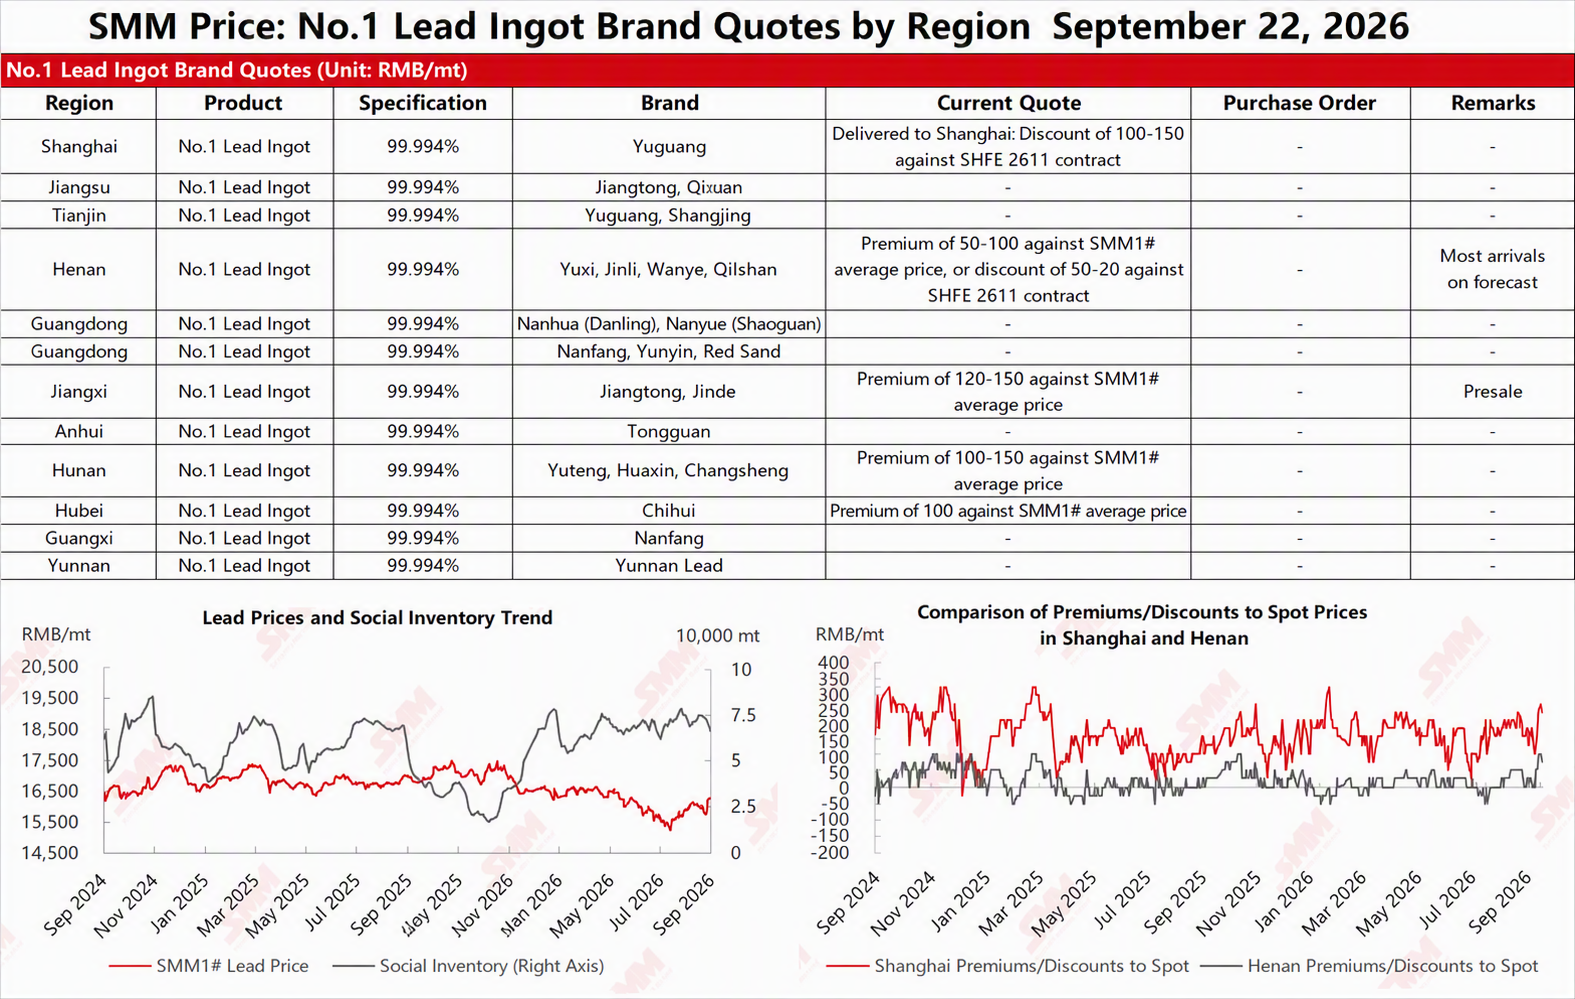
SMM September 22: In the Shanghai market, Chihong lead was quoted at 16,545-16,615 yuan/mt, at premiums of 100-150 yuan/mt against the SHFE 2611 lead contract. SHFE lead remained strong, and most suppliers sold along with market trends. Meanwhile, the tightness of primary lead smelters' ex-works cargoes continued to ease, with high-premium quotes slightly lowered. Mainstream production area quotes were at premiums of 50-120 yuan/mt against the SMM #1 lead average price on an ex-works basis. In secondary lead, many smelters cut or halted production, and operating enterprises held prices firm while selling. Mainstream production area secondary refined lead quotes ranged from a discount of 100 yuan/mt to a premium of 25 yuan/mt against the SMM #1 lead average price on an ex-works basis. Downstream enterprises made just-in-time procurement, while others mostly stayed on the sidelines, resulting in moderate spot market transactions.
Today, the SMM #1 lead price rose by 50 yuan/mt from the previous trading day. The spot tightness in Henan eased slightly, with a small number of current-month spot quotes emerging in the market. Suppliers actively quoted and sold, while also pre-selling October cargoes. Spot order quotes were at discounts of 50-20 yuan/mt against the SHFE 2611 lead contract on an ex-works basis, with no improvement in transactions. In Hunan, smelters sold along with market trends, with spot order quotes maintained at premiums of 100-150 yuan/mt against the SMM #1 lead average price on an ex-works basis, and actual transactions leaned toward premiums of 100 yuan/mt or below. In Jiangxi and Anhui, smelters' spot order quotes were at premiums of 120-150 yuan/mt against the SMM #1 lead average price on an ex-works basis, with some being pre-sales of October cargoes. With lead prices elevated, downstream enterprises mostly held a wait-and-see attitude, while suppliers actively quoted and sold. The scarcity of spot lead improved slightly, and some downstream players waited for new monthly long-term contracts to begin, resulting in weak spot market transactions.
Data source statement: Except for publicly available information, all other data are processed by SMM based on public sources, market communication, and SMM's internal database models, and are for reference only and do not constitute decision-making advice.