The average price of SMM 10-12% high-grade NPI fell WoW by 33.1 yuan/nickel unit to 1,062.4 yuan/nickel unit (ex-factory, tax included), and the average Indonesia NPI FOB index price fell WoW by $4.06/nickel unit to $137.08/nickel unit. This week, the high-grade NPI market continued to drift lower overall, with the tug-of-war between longs and shorts intensifying.
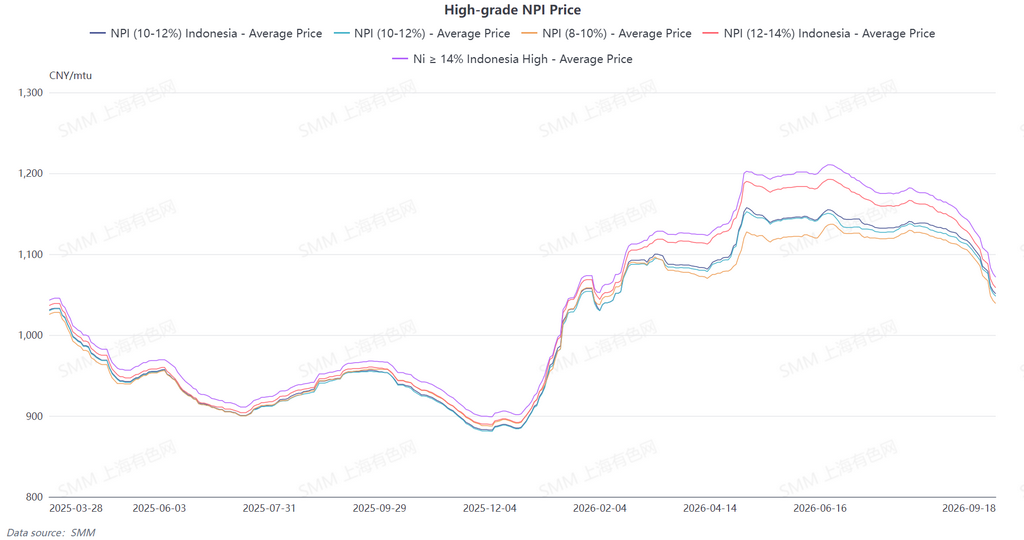
Supply side, port inventories rose and market supply was ample, with some traders continuing panic selling. Upstream holders had cost floors, and quotes diverged, with some sticking to prices near cost levels, but low-priced cargoes kept emerging. Demand side, downstream steel mills generally held sufficient inventory and showed weak purchase willingness, continuously lowering their bid prices. Some enterprises delayed or even suspended spot purchase plans. As prices kept falling, downstream buying sentiment remained cautious, and high-priced cargoes faced significant resistance in closing deals. The price spread between buyers and sellers was hard to narrow, with only scattered small spot transactions concluded. Overall market liquidity was weak, market pessimism intensified, and participants' expectations for the market bottom kept moving lower. Views in the market diverged: some participants believed there was still downside for prices, while some upstream players and traders thought prices were gradually approaching the bottom, with expectations of prices stopping falling and stabilizing emerging. The market was still waiting for transactions to confirm bottom support, and a clear recovery was unlikely in the short term.
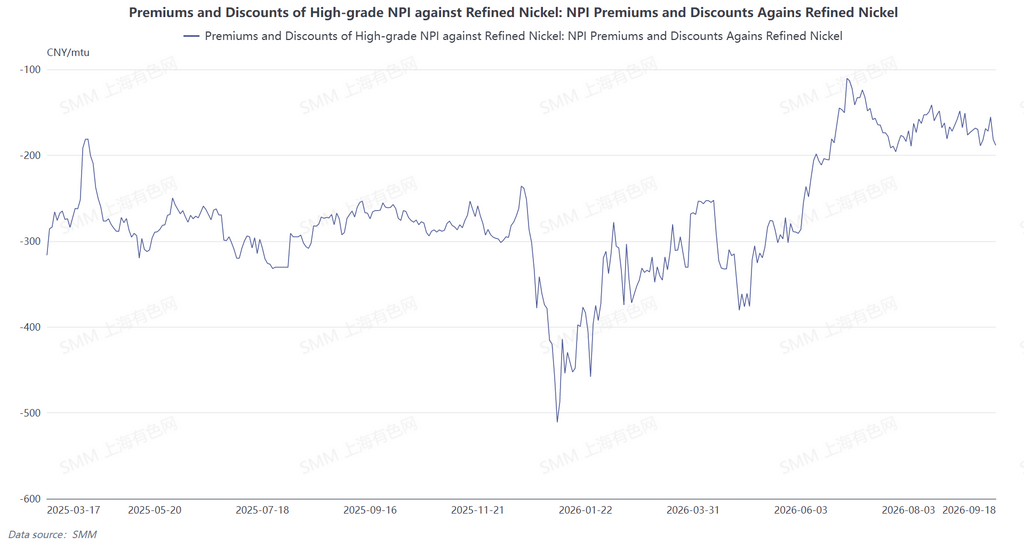
From the perspective of NPI-to-high-grade nickel matte conversion, the discount of high-grade NPI relative to refined nickel was 173.3 this week, with the discount narrowing slightly. This week, refined nickel futures and NPI spot prices fell in tandem, with similar declines and limited fluctuations in the price spread. Looking ahead to next week, under the current fundamental structure, the discount of high-grade NPI relative to refined nickel is unlikely to widen significantly, which is still not enough to drive conversion of NPI to high-grade nickel matte. NPI still offers higher profitability by comparison.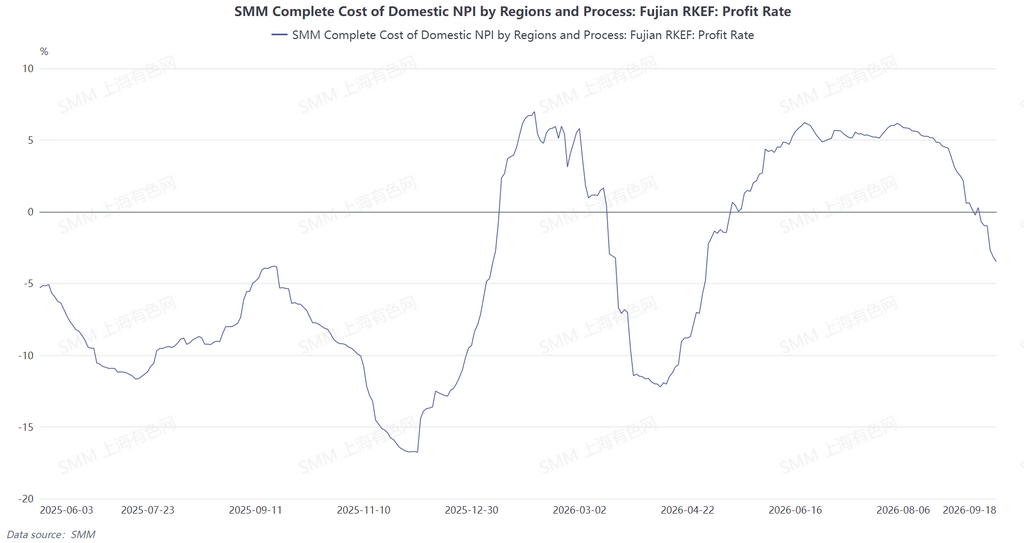
This week, prices of nickel ore, coke, and other ore and auxiliary materials used in domestic high-grade NPI smelting were generally stable. In Indonesia, raw material costs edged down along with nickel ore prices, but the slight decline in raw material costs was not enough to offset the continued pullback in high-grade NPI spot prices. Affected by falling prices, smelting profit margins in both China and Indonesia narrowed simultaneously, and both regions have now shown marginal losses, with smelters facing rising production pressure.