This week, mainstream quotations of chloroplatinic acid and palladium chloride in China edged up over the weekend while weekly average prices declined. The market has halted its prior downtrend and entered a range-bound consolidation at low levels. Weak raw material prices have consolidated the price bottom; spot shipment volumes have picked up markedly, and downstream purchasing appetite has improved steadily. The automotive end market shows divergent performance. Domestic vehicle sales can only see limited seasonal recovery, while rising oil prices curb domestic demand for fuel vehicles. Overseas complete vehicle exports have become the key marginal driver for rising platinum group compound demand, lending important support to market fundamentals.
Price Trend: Mild Weekend Rebound amid Low-level Consolidation
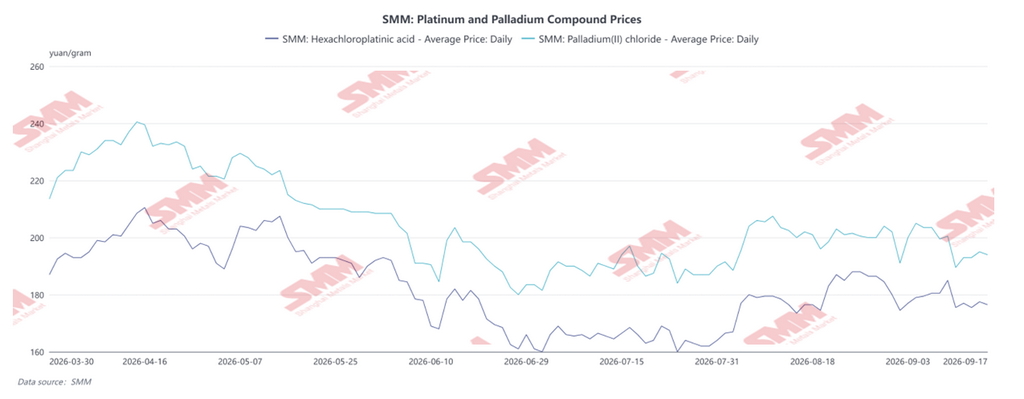
The two major platinum group compounds posted slight gains towards the week-end, with weekly average prices falling, highlighting an overall stabilizing market. In terms of specific figures, chloroplatinic acid rose modestly to 176.5 CNY/g on Friday, up 1 CNY/g or 0.6% from 175.5 CNY/g a week earlier. Palladium chloride saw a stronger rebound, quoted at 194.0 CNY/g on Friday, gaining 4.5 CNY/g or 2.4% versus 189.5 CNY/g in the prior week.
Weekly average prices remain trapped in the earlier low zone with no full-scale rebound in sight. The weekly average of chloroplatinic acid stood at roughly 176.6 CNY/g, below last week’s 180.2 CNY/g. Palladium chloride averaged 193.8 CNY/g this week, also lower than the previous reading of 199.3 CNY/g. Overall, chloroplatinic acid and palladium chloride have undergone sufficient corrections and are now in a tight bottom consolidation phase. Room for sharp near-term declines is limited, and the mild late-week uptick signals gradual improvement in market sentiment.
Spot Supply & Demand: Weaker Feedstock Underpins Low Prices; Trading Activity Improves
Trading sentiment in the platinum group compound spot market improved visibly this week, with shipments accelerating notably compared to the past two weeks. Mild falls in raw material costs have solidified the low-price foundation for compounds. Price froth has largely dissipated, boosting cost competitiveness and drawing concentrated spot purchases from downstream end-users with rigid demand.
The overall supply-demand balance continues to improve. Producers have stabilized quotations and are willing to offer discounts to clear stocks, gradually easing inventory pressure. After a period of wait-and-see inventory building, downstream buyers have released restocking demand, and purchasing sentiment keeps improving. Market activity has risen steadily, reversing the previously sluggish trading environment. Driven by low prices and mandatory restocking, the sector has entered a phase of low-level stabilization and recovering transactions.
End-user Demand: Limited Domestic Seasonal Recovery; Overseas Exports as Core Marginal Driver
As the primary downstream sector for platinum group compounds, the automotive industry directly shapes market performance. The vehicle market displayed a split pattern this week: soft domestic demand paired with robust overseas sales. Domestically, while a sequential quarterly recovery is expected for the auto industry in September and October, fuel vehicle output and sales are only projected to inch up with limited upside. Meanwhile, climbing oil prices directly suppress fuel vehicle consumption and dampen consumer willingness to buy cars. This caps overall domestic automotive demand and prevents a sharp rise in platinum group compound consumption.
Against the muted seasonal recovery at home, exports of finished vehicles to overseas markets represent the most important marginal growth source for platinum group compound demand. Faced with headwinds in the domestic auto market, automakers continue to expand overseas presence. Steady growth in export orders offsets weak domestic consumption, providing stable support for platinum group compound consumption in automotive catalysts and acting as the core engine for demand recovery.
Market Outlook
In the near term, China’s chloroplatinic acid and palladium chloride markets will maintain low-level range-bound movement, with low probability of extreme price swings. Raw material prices are set to stabilize, and continuous restocking from downstream rigid demand will underpin the market bottom, keeping spot trading active. Demand will remain bifurcated: the domestic auto market will deliver a modest seasonal upturn with limited incremental demand, while resilient overseas vehicle exports will continuously supply marginal demand to support gradual price recovery for platinum group compounds.
All told, backed by overseas export demand, the platinum group compound market will gradually exit its bottom consolidation range. Prices may trend upward slowly, and the overall market will follow a pattern of “moderate gains amid oscillatory recovery”.