SMM, September 17:
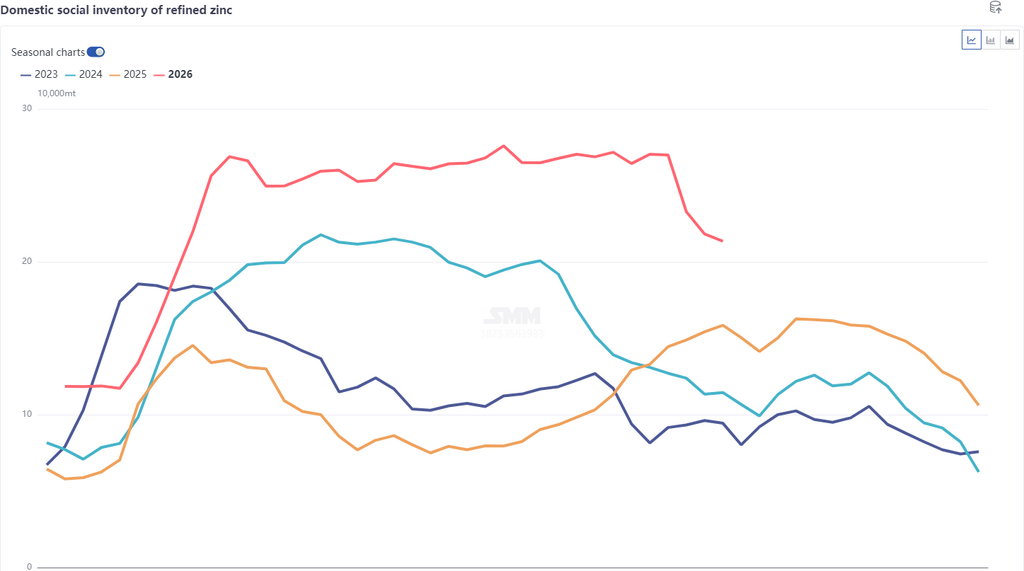
Since late August, China's visible social inventory of refined zinc has declined from 270,000 mt to 213,500 mt, showing a sustained pullback overall. Entering September, the social inventory destocking accelerated. By region, Shanghai and Tianjin saw the most pronounced inventory pullbacks. As of September 17, Shanghai's zinc ingot inventory stood at 75,300 mt and Tianjin's at 83,800 mt, making these two regions the main contributors to the nationwide destocking. What are the specific reasons for the notable decline in China's inventory?
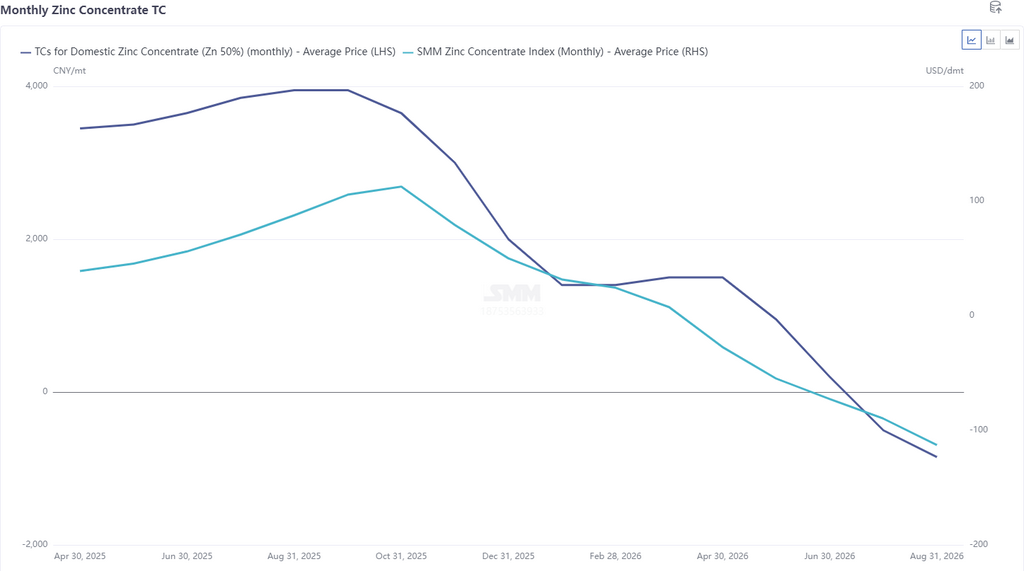
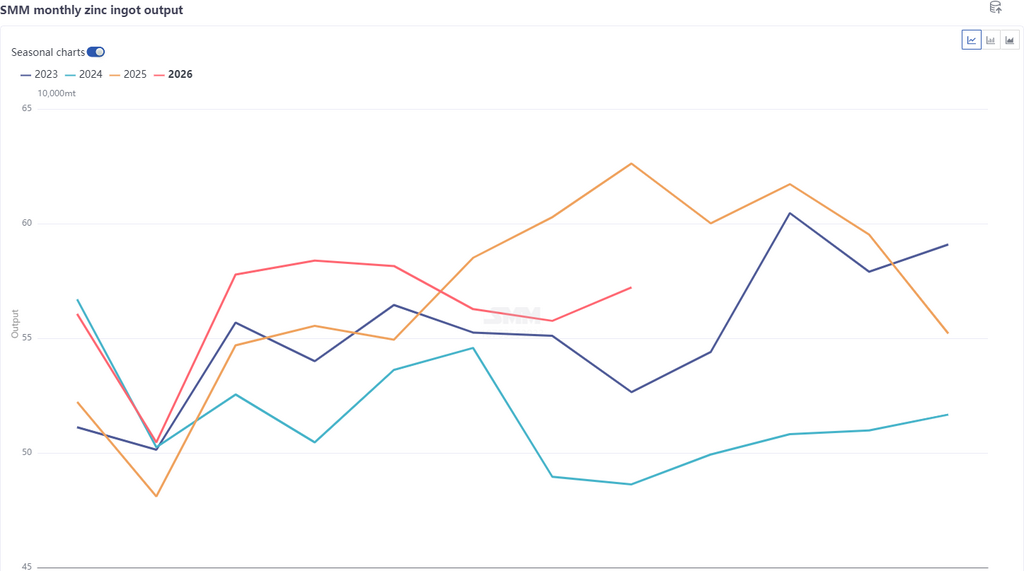
From the supply side, zinc ore raw materials remained tight. Domestic zinc concentrate TCs fell to below -2,000 yuan/mt in metal content, and imported TCs dropped to a historical low of below -$120/dmt, constraining smelting output. Combined with seasonal maintenance, China's refined zinc production declined MoM, leaving the supply side with insufficient support.
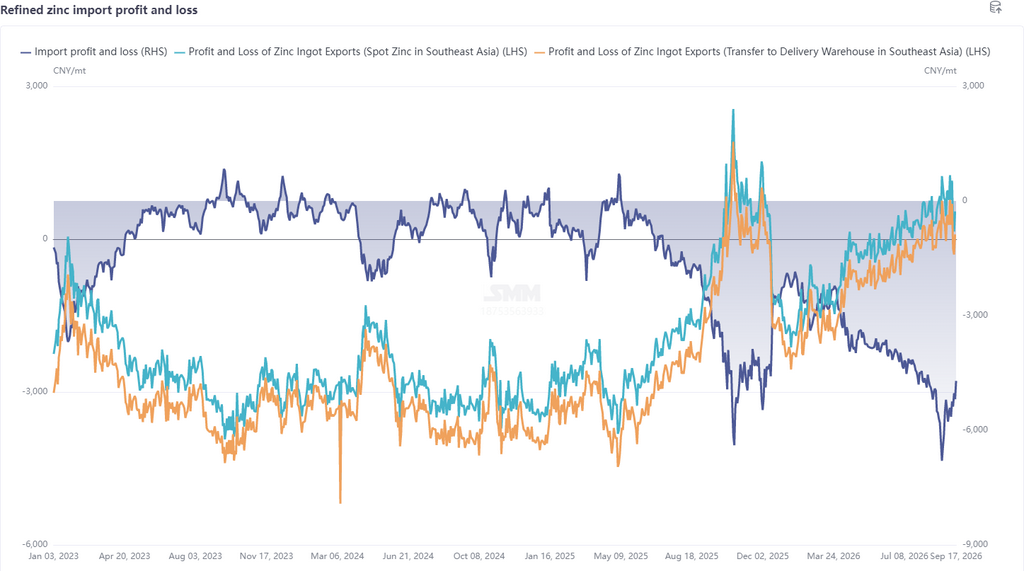
In terms of imports and exports, since the beginning of this year, with the overseas market outperforming the domestic market, the import window for zinc ingots in China has remained closed, and imported zinc ingots have suffered severe losses, with bonded goods transfers being the main activity and imports being minimal. On the export side, as the SHFE/LME zinc price ratio continued to decline, the delivery window for exporting refined zinc to Southeast Asia opened in August. Domestic smelters and traders became more active in exporting, and the large volume of zinc ingot exports accelerated the decline in inventory.
Demand side, operating rates in downstream galvanizing, zinc alloy, and zinc oxide sectors are expected to improve MoM in September, though the MoM growth is relatively limited, and the destocking contribution from orders is also limited. However, with zinc prices retreating from highs recently, downstream fear of high prices has eased somewhat. Coupled with the upcoming dual holidays, enterprises have stepped up bargain stockpiling, spot trading activity in the trade market has increased, suppliers have been selling smoothly, and warehouse spot pickup volume has risen, driving continued digestion of visible inventory in recent days.
Market outlook: In the short term, MoM improvement during the zinc peak season remains expected. If downstream end-user orders are released and downstream pickup volume stays at a high level, China's social inventory still has room for further destocking. However, two key variables warrant attention: first, the magnitude of refined zinc supply growth after smelter maintenance concludes; second, the reduction in zinc ingot exports driven by changes in import profit margins. Considering that smelter production in October is expected to increase MoM, China's export volume in October is unlikely to surpass September, and October coincides with the National Day holiday, with more enterprises on holiday, the likelihood of a slight increase in zinc ingot social inventory is relatively high.