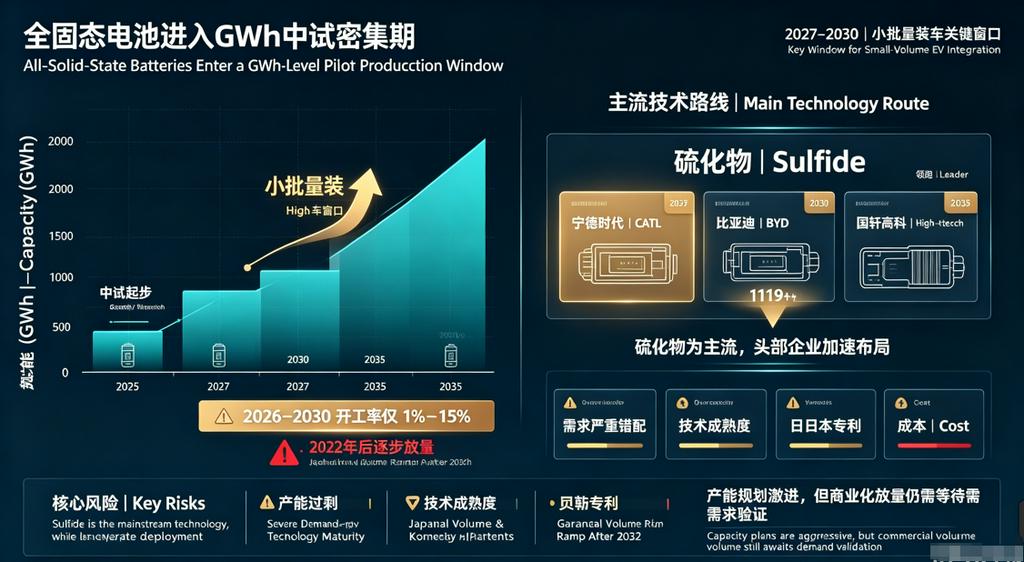
Key points: All-solid-state batteries have entered an intensive GWh pilot production period, with 2027–2030 as the key window for small-batch vehicle installation. Planned capacity is expected to exceed 1,119 GWh by 2035, but the utilization rate from 2026 to 2030 will be only 1%–15%, indicating a severe demand mismatch, with volume ramp-up only gradually beginning after 2032. Sulfide is the mainstream route, with CATL, BYD, Gotion High-tech, and others leading; risks lie in overcapacity, technology maturity, Japanese and South Korean patents, and cost.
Notes:
The solid-state battery capacity analysis is divided into Part 1 and Part 2. Part 1 covers solid-liquid batteries, and Part 2 covers solid-state batteries. As a transitional route toward solid-state batteries, solid-liquid batteries will also exist for a long time; for now, they are analyzed within the solid-state battery system. Solid-liquid batteries include gel-state batteries, solid-liquid hybrid batteries, quasi-solid-state batteries, and semi-solid-state batteries. For batteries with a liquid electrolyte mass proportion of 5%–20%, a solid electrolyte framework is added to constrain a small amount of liquid electrolyte.
Solid-State Battery Capacity Analysis (Part 1): Solid-Liquid Batteries as the Vanguard — A Transitional Route with Both Supply and Demand Booming
Solid-State Battery Capacity Analysis (Part 2): Solid-State Battery Pilot Production Deployed Intensively — Capacity Planning and Demand Mismatch
This article is Part 2: the capacity status of solid-state batteries, i.e., all-solid-state batteries.
Data: This capacity data is based on enterprises' capacity planning and SMM demand model analysis. Medium- and long-term data, in particular, relies on the SMM demand model.
Final data shall be subject to the capacity data officially released by enterprises.
1. Industry Stage: From Laboratory to GWh Pilot Production; 2027–2030 Is the Key Window
According to the table statistics, solid-state batteries (mainly all-solid-state) have moved from laboratory R&D into an intensive construction period for pilot lines. From 2024 to 2026, multiple all-solid-state pilot lines and experimental lines have been commissioned or completed. Representative companies include CATL, BYD, Gotion High-tech, Qingtao, WeLion, CALB, EVE Energy, Farasis Energy, Tailan New Energy, and others.
Typical milestones:
CATL: Hefei 5 GWh sulfide all-solid-state pilot line was commissioned in May 2025; Phase I of the Yibin all-solid-state base was commissioned in July 2026, with single-cell energy density exceeding 500 Wh/kg.
BYD: Shenzhen Pingshan 2 GWh sulfide all-solid-state pilot line was commissioned in February 2026, with yield stable at 82%; the first-phase 20 GWh mass production line in Chongqing Bishan is planned to start in Q3 2026, with small-batch vehicle installation in Q1 2027, and a long-term plan of 100 GWh.
Gotion High-tech: Hefei 0.2 GWh all-solid-state experimental line was completed in May 2025; the 2 GWh mass production line is expected to enter equipment commissioning by the end of 2026 and begin small-batch production in 2027.
Qingtao Energy: Kunshan 0.1 GWh all-solid-state pilot line has been commissioned.
WeLion New Energy: Shenzhen Pingshan 0.6 GWh all-solid-state small-scale trial base, with plans to achieve all-solid-state mass production around 2027.
CALB: Changzhou 0.2 GWh solid-state battery pilot production capability.
EVE Energy: Chengdu base Phase I 60 Ah completed in December 2025; Phase II 100 MWh annual capacity is to be delivered in December 2026.
Farasis Energy: Ganzhou 0.2 GWh sulfide all-solid-state pilot line; 60 Ah cells have been sampled to robot customers.
Tailan New Energy: Hubei Qianjiang 3.5 GWh all-solid-state battery project was completed in June 2026, with Phase I at 0.5 GWh.
Sunwoda: 0.2 GWh sample line; 400 Wh/kg polymer all-solid-state battery, with vehicle installation validation planned for completion in 2026.
Overall, 2025–2026 is a period of intensive pilot line landing, 2027 will enter small-batch vehicle installation validation, and around 2030 the goal is large-scale mass production.
2. Capacity Planning: Exponential Expansion, Exceeding 1,100 GWh by 2035
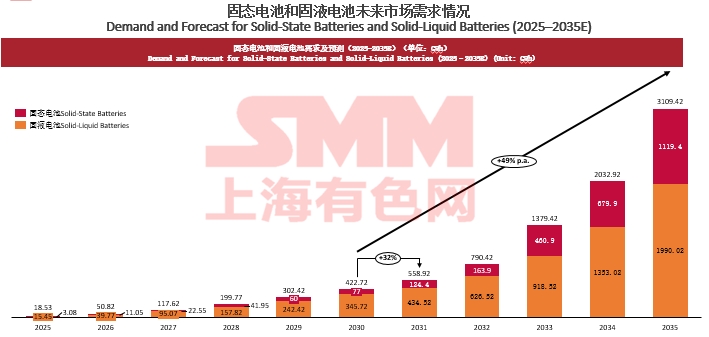
According to the summary data in the table, planned solid-state battery capacity will grow from 3 GWh in 2025 to 1,119 GWh in 2035, showing exponential expansion:
Solid-state battery capacity will grow from 3 GWh in 2025 to 77 GWh and 1,119 GWh in 2030 and 2035, respectively.
Among this, planned capacity will jump significantly after 2033, mainly from the long-term plans of BYD's Bishan base, CATL's Yibin base, Tailan's Qianjiang project, WeLion, Qingtao, and others. However, it should be noted that these figures are mostly corporate planned capacity, and actual implementation is constrained by multiple factors such as yield, equipment, capital, and customer validation.
3. Demand and Utilization Rate: Severe Short-Term Mismatch, Gradually Matching Only After 2033
Compared with capacity planning, the release of solid-state battery demand clearly lags, and capacity expansion may replicate the model of liquid lithium batteries.
From 2026 to 2030, the utilization rate of solid-state batteries will be only 1%–15%, indicating that capacity planning far exceeds short-term actual demand. A large number of pilot lines and experimental lines are in the validation stage and have not yet formed effective shipments. The utilization rate will rise to 28% in 2031, jump to 69% in 2032, and stabilize at 73%–89% after 2033. This means that the true large-scale volume ramp-up of solid-state batteries may occur after 2032–2033, creating a certain time gap with the industry's widely expected "large-scale production by 2030."
4. Technology Routes: Sulfide as the Mainstream, with Oxide / Polymer / Composite in Parallel
The solid-state battery technology landscape shows a pattern of "sulfide as the mainstream, with multiple routes in parallel."
Sulfide route: CATL, BYD, Gotion High-tech, Sanwei Battery, Jiugong New Energy, Zhongke Yuanben, Enpower, etc. Sulfide electrolytes have high ionic conductivity, but poor air stability, high cost, and patent barriers concentrated in Japan and South Korea.
Oxide route: Some companies adopt oxide composite routes, such as Qingtao and WeLion.
Polymer route: Sunwoda, Shenlan Huize, Solid Ion Energy, etc.
Composite route: Shandong Chuanglu adopts a "sulfide + oxide + polymer" composite route and claims cost reduction of 80%–90% compared with pure sulfide.
Halide / sulfide-halide composite: EVE Energy adopts a sulfide-halide composite solid electrolyte.
Overall, sulfide is the most watched main route for all-solid-state batteries, but it is the most difficult to engineer; composite routes have become an important exploration direction for cost reduction and interface improvement.
5. Corporate Landscape: Top Battery Makers + New Forces + Automakers in Three-Way Competition
Solid-state battery players can be divided into three categories.
Top battery makers: CATL, BYD, Gotion High-tech, CALB, EVE Energy, Farasis Energy, Sunwoda, etc. They have strong capital and customer resources, but are cautious in choosing technology routes.
Solid-state battery new forces: Qingtao, WeLion, Tailan, Enpower, Heyuan Lithium Innovation, Xinjie Energy, Jinyu New Energy, Jiugong New Energy, etc. They focus on niche solid-state battery tracks, and some have already achieved pilot production or small-batch delivery.
Automakers and cross-industry players: Dongfeng Motor, Chery, Geely, SAIC, and others are positioning in solid-state batteries through in-house development or cooperation to gain a say in next-generation power batteries.
In terms of regional distribution, Jiangsu, Anhui, Guangdong, Zhejiang, Sichuan, Shandong, and Henan are concentrated areas for solid-state battery projects. Hefei in Anhui, Suzhou/Changzhou in Jiangsu, Shenzhen/Zhuhai in Guangdong, Huzhou/Hangzhou in Zhejiang, and Yibin/Chengdu in Sichuan have formed industrial clusters.
6. Risks and Challenges: Overcapacity, Technology Maturity, Patents, and Cost
Overcapacity risk: The utilization rate from 2026 to 2030 will be extremely low, and a large amount of planned capacity may be delayed or canceled.
Insufficient technology maturity: All-solid-state batteries still face core issues such as solid-solid interfaces, operating pressure, cycle life, and intrinsic material stability. Robin Zeng of CATL once said that the technology maturity of all-solid-state batteries is only TRL-4.
Patent barriers: Core patents for sulfide electrolytes are dominated by Japanese and South Korean companies, and Chinese companies face FTO risks when going overseas.
High cost: The current cost of all-solid-state batteries is far higher than that of liquid batteries, and cost reduction depends on the localization of lithium sulfide, electrolytes, and equipment.
Long automotive-grade validation cycle: From sampling to designation may take 18–36 months, validation costs are high, and automakers are cautious in acceptance.
7. Conclusion
Solid-state batteries are in a stage of "intensive pilot line landing and the eve of mass production." Capacity planning is aggressive, but short-term demand is severely insufficient, and utilization rates remain low. 2027–2030 is a key window for technology validation and small-batch vehicle installation, and only after 2032 is large-scale volume ramp-up expected. Enterprises need to view capacity planning rationally, focus on core technology breakthroughs, cost reduction, and customer validation, and avoid blind expansion.
**Note:** For further details or inquiries regarding solid-state battery development, please contact:
Phone: 021-20707860 (or WeChat: 13585549799)
Contact: Chaoxing Yang. Thank you!