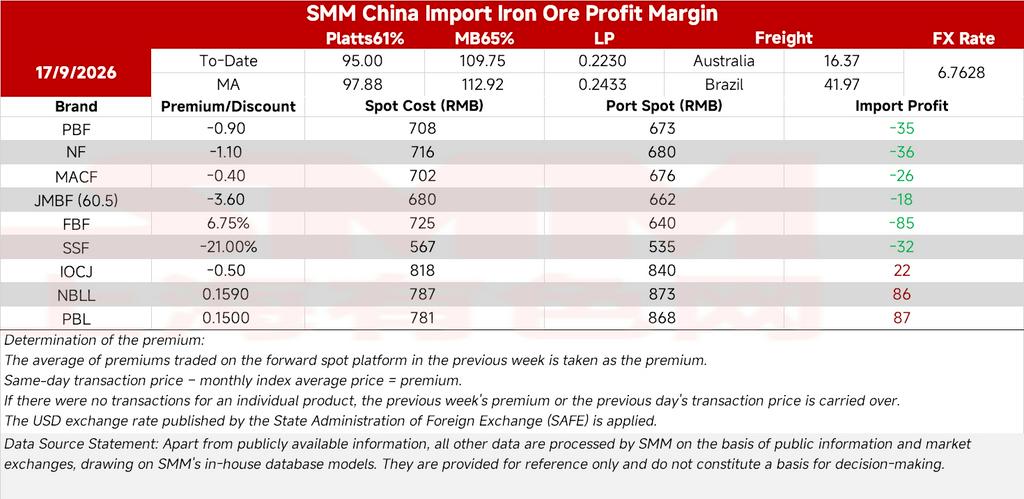
The average imported iron ore margin recovered from -13.18 yuan/mt to -3.97 yuan/mt this period, helped by lower Australian freight rates, a stronger yuan against the US dollar and softer seaborne premiums.
SMM survey data showed mill losses deepening and end-use demand still weak, prompting more blast furnace maintenance. As of 16 September, the blast furnace operating rate across 242 mills tracked by SMM stood at 88.93%, down 0.15 percentage point week on week. Average daily hot metal output at sample mills fell 3,700 mt to 2.3991 million mt. Some mills have begun pre-holiday restocking, however, and overall iron ore demand still lends support to prices.
Iron ore prices face resistance in both directions and are likely to stay range-bound in the near term. Imported margins are likely to remain negative until end-use demand improves.